
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dutch Bros (BROS) Could Be 43% Undervalued On Unicorn Blood Launch
Dutch Bros (BROS) turned a long-running secret menu favorite into a headline product by adding the Unicorn Blood drink to its official Halloween 2026 lineup, giving investors a fresh seasonal data point to watch.
For context, Dutch Bros shares trade at US$41.16, with a 7 day share price return of 10.41% that comes after a 90 day share price decline of 37.76% and a 1 year total shareholder return decline of 26.63%. The Halloween Unicorn Blood launch therefore lands as the market reassesses shorter term momentum against a much stronger 3 year total shareholder return of 68.41%.
Scan for other consumer stocks that are turning cult favorites into growth stories by exploring our curated list of 20 high quality undiscovered gems while Dutch Bros tests Unicorn Blood on the main stage.
After a sharp 7 day rebound on top of longer term declines, Dutch Bros now asks a simple question of anyone circling the stock: Does the current valuation still leave more upside than downside from here?
Most Popular Narrative: 43% Undervalued
Against the last close of $41.16, the most followed Dutch Bros thesis points to a fair value of $72.00. The Unicorn Blood launch therefore lands against a narrative that already treats the stock as trading at a sizeable discount while expansion, margins, and execution do the heavy lifting in the background.
The main factor that has to go right is that Dutch Bros converts its high leadership bench, food and energy platforms, and dense real estate pipeline into new shops that maintain current contribution margins despite higher coffee and occupancy costs.
The current valuation implies the market is discounting Dutch Bros’ progress on revenue and EBITDA guidance, shop growth, and digital engagement, which leaves the share price below what this narrative views as a fair reflection of those fundamentals.
See why 83 investors see Dutch Bros as 43% undervalued.
Result: Fair Value of $72.00 (UNDERVALUED)
Still, the bullish Dutch Bros story runs into two clear pressure points if wage and ingredient costs keep grinding higher or if planned shop openings slip.
Find out about the key risks to this Dutch Bros narrative.
Another View: Dutch Bros Through a P/E Lens
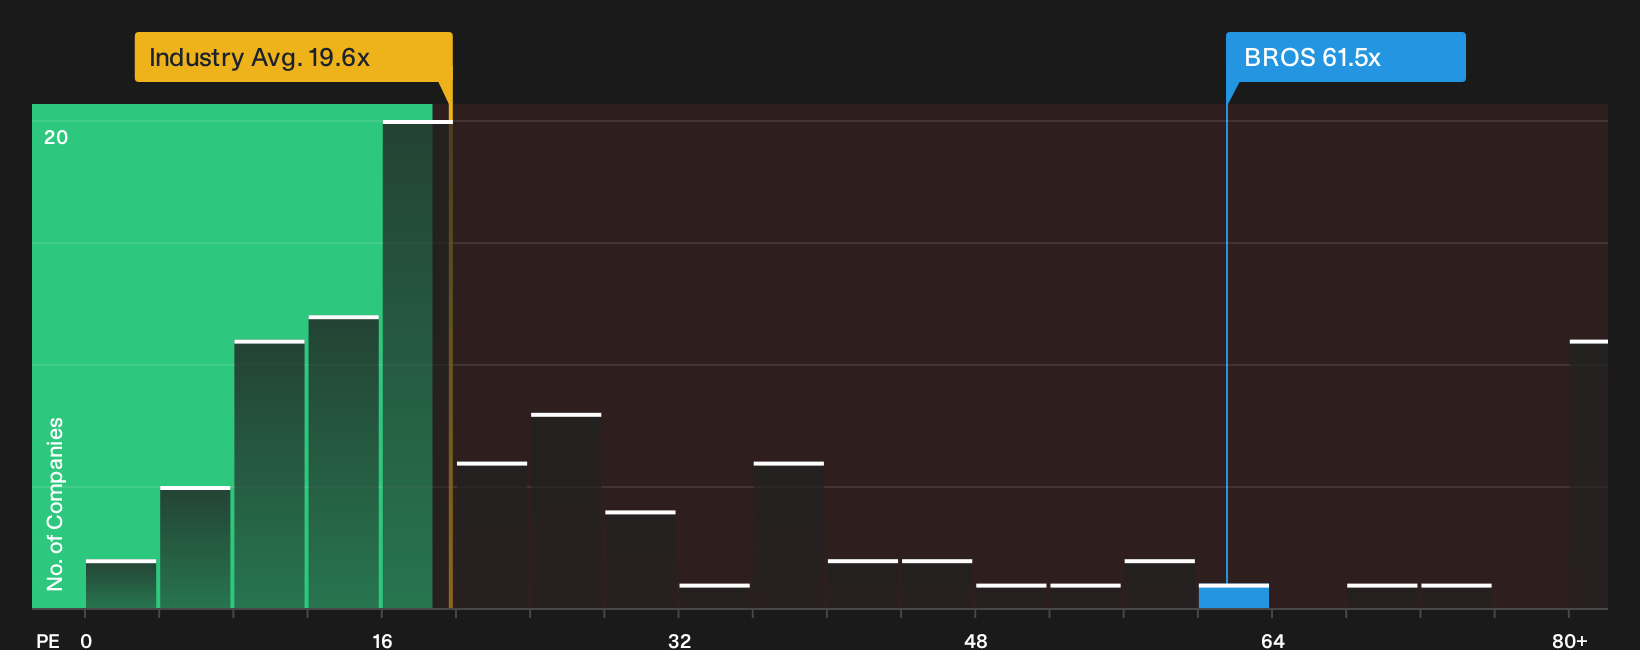
The first Dutch Bros story leans on a fair value of $72.00 and a 43% discount. A simple earnings multiple paints a sharper picture of the trade off. The stock changes hands at a P/E of 61.5x, while the fair ratio is 27.1x, the Hospitality industry sits at 19.6x and peers average 41x. That gap points to real valuation risk if sentiment slips or execution stumbles. Are you comfortable paying that kind of premium to the sector and to the fair ratio for this Halloween thesis?
To see how those earnings multiples stack up against the assumptions sitting behind them, take a closer look at our valuation breakdown for Dutch Bros, starting with See what the numbers say about this price — find out in our valuation breakdown..
Visual context on P/E helps here too, so it is worth lining Dutch Bros up directly against the broader Hospitality group through
Next Steps
If this all feels cautiously optimistic, use that tension as a reason to move quickly and review the details yourself. Then compare the potential upside with the pressure points by examining the 3 key rewards.
Looking for more Dutch Bros style investment ideas?
Do not stop at Dutch Bros. If you want a broader watchlist, use the Simply Wall St screener to find other stocks that fit your playbook.
- Target quality at a discount by scanning for companies that combine resilience with attractive pricing through the 33 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Dial down portfolio stress and concentrate on steadier performers by filtering opportunities via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com