
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BlackRock Stock And 2 Credit Plays For Higher Rate Markets
AI infrastructure spending is grabbing headlines, yet the real story for many investors sits in the credit markets, where rising yields, wider spreads, and pressure on tech valuations are quietly reshaping who controls the lending power. This backdrop can create openings for listed private credit and specialty lenders exposed to these trends. This article walks through three such stocks and how recent news might be working in their favour.
The three stocks covered next are a small sample from this corner of credit markets, and the full screen surfaced 23 more listed private credit and specialty lenders with equally compelling narratives that are not included in the article.
If you want to move past headlines and identify and analyze the highest conviction listed private-credit and specialty lender ideas, head straight into the Listed Private-Credit & Specialty Lenders to Corporate Borrowers screener.
Altamir (ENXTPA:LTA)
Altamir gives you listed access to private equity style exposure to leveraged corporate finance, a different angle on the private credit theme that still ties your capital to the health of small and mid sized borrowers.
Altamir is a Paris based private equity investment vehicle that backs small and mid cap businesses directly and through funds, generating €14 million from private equity activity and carrying a market value of about €817 million.
"There is a risk that Altamir's current valuation assumes a continued robust rebound in private equity exits and elevated exit multiples, yet the global IPO window remains closed and overall economic growth in developed markets is still weak. If exit opportunities remain limited outside of M&A, future realized gains may be lower than implied, impacting revenue and earnings growth."
What happens to Altamir's margins and payout potential if one key pressure on portfolio exit timing does not ease as quickly as many expect?
If that risk-reward tradeoff intrigues you, read the full narrative for Altamir to see how Altamir's exit timing, leverage, and payout story could be decoupling.

Tokyo Century (TSE:8439)
Tokyo Century is a ¥1,277.9b market cap specialist in leasing and financing for equipment, vehicles, infrastructure and renewable energy, giving it clear exposure to the private credit theme as corporates seek non bank funding for capital intensive projects. Reported segment data currently groups most income within internal adjustments.
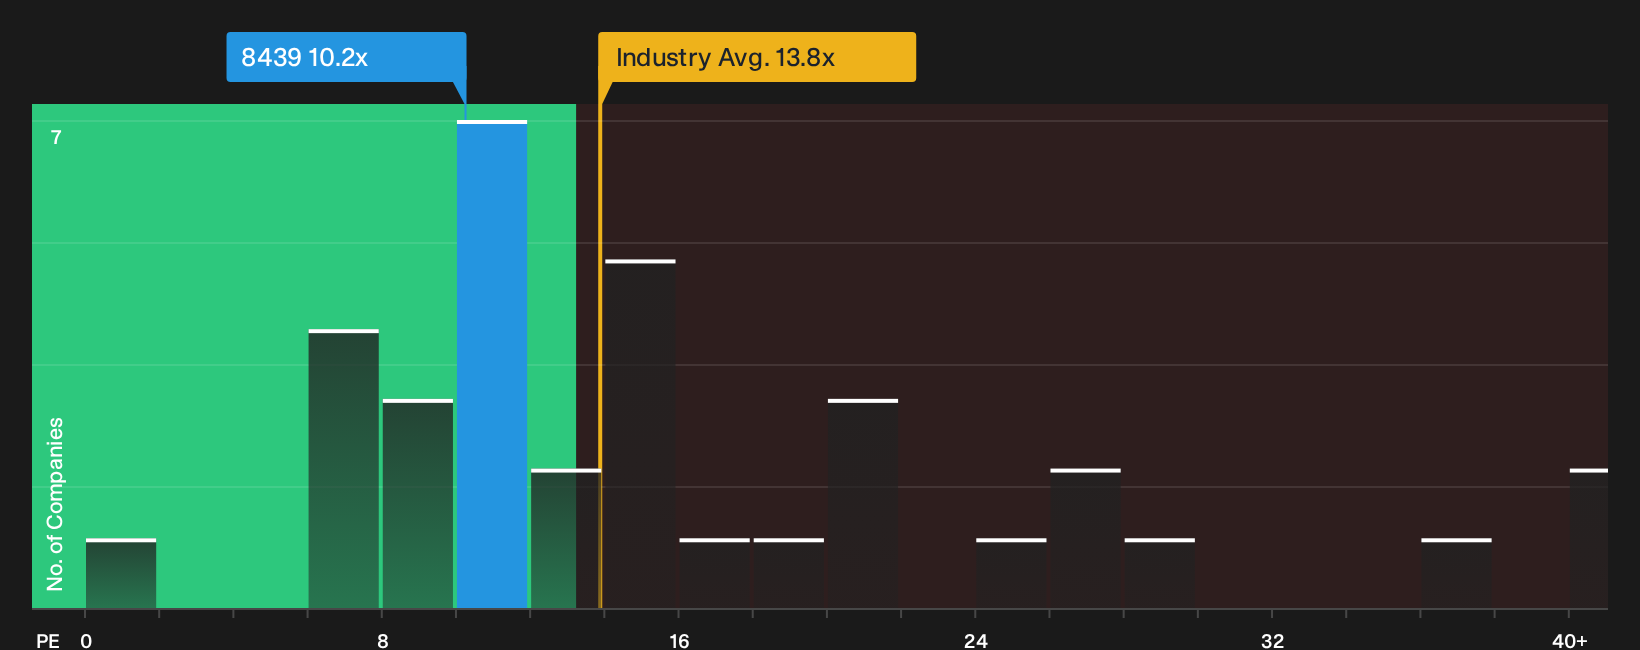
Tokyo Century provides listed exposure to corporate leasing and specialty finance tied to equipment, autos, infrastructure and renewable energy projects. These areas rely heavily on lenders rather than deposits when borrowing costs rise. Earnings momentum, a P/E around 10.2x and a 3.47% yield highlight the risk that a single funding pressure could tighten at an inopportune time.
That funding risk is only half the story, and the 4 key rewards and 2 important warning signs (1 is major!) shows how Tokyo Century’s valuation and income profile could be pulling in different directions.
BlackRock (BLK)
BlackRock taps into the Listed Private-Credit & Specialty Lenders to Corporate Borrowers theme through its credit and private-credit strategies, yet its real pull for you is as a global asset manager tying those lending activities to fee income, scale, and technology.
BlackRock runs a global asset management franchise across public and private markets, earning all of its US$28.5b in revenue from the Asset Management Business and carrying a market value of about US$184b.
For investors watching how private credit plugs into the AI buildout and wider corporate borrowing, BlackRock offers something different to pure lenders, a broad fee platform that can channel capital into those deals while spreading risk across ETFs, alternatives, and technology services.
"Expansion of BlackRock's private markets platform, including infrastructure and private credit fundraising that reached $68b over the 12 months to Q3 2026, positions the company to keep shifting revenue toward higher fee alternatives, which can support base fee growth and earnings over time."
What really matters now is how pressure on funding costs and client demand shapes whether that higher fee mix actually feeds through to long term margins.
If that mix shift is what you care about next, read the full narrative for BlackRock to see how BlackRock's fee engine could be accelerating or stalling from here.

Curious About What You Might Be Missing?
Fresh ideas move first. By the time momentum is obvious, early entry points may no longer be available. Review these under the radar for now opportunities and consider how they might fit your strategy.
- Explore potential income streams before yields are affected by additional interest through a curated set of 217 dividend fortresses built to keep payouts front and center.
- Monitor where AI demand may be contributing to the next leg of infrastructure spending with a focused pool of 55 AI infrastructure stocks that could be entering a new phase.
- Identify resilience while others chase hype by reviewing 231 resilient stocks with low risk scores that prioritize balance sheet strength and downside control.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com