
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tokyo Seimitsu (TSE:7729) Draws AI Demand Focus, Is The Premium Already Too High?
Analysts have recently turned the spotlight on Tokyo Seimitsu (TSE:7729) as AI related demand and higher sales expectations draw fresh attention to the semiconductor equipment specialist and its current market valuation.
The share price tells a mixed story. Tokyo Seimitsu has pulled back sharply in the very short term, with the 1 day share price return down 2.63% and the 7 day share price return down 14.69%. However, the year to date share price return of 52.28% and 1 year total shareholder return of 74.53% still point to strong momentum, supported by longer term total shareholder returns of 164.30% over three years and 351.70% over five years.
Compare Tokyo Seimitsu's AI equipment story with other potential beneficiaries by scanning our hand picked list of 55 AI infrastructure stocks across the semiconductor and hardware supply chain.
Tokyo Seimitsu looks like a solid AI equipment play on the surface, yet the recent surge and short term pullback raise a sharper issue. Is this quality business still sensibly priced today, or has enthusiasm gone too far?
Price-to-Earnings of 27.2x: Is it justified?
Tokyo Seimitsu now trades on a richer P/E than both its domestic semiconductor peers and the broader industry. This points to the market paying a premium for the ¥17,565 share price compared with earnings.
The P/E ratio compares what investors are willing to pay today with the business's current profits per share. For chip equipment makers like Tokyo Seimitsu, this measure often reflects how the market views the durability of demand cycles, order visibility, and the quality of existing earnings rather than just near term headlines.
Analysts currently view Tokyo Seimitsu as expensive on this yardstick. The current P/E of 27.2x sits above the peer average of 24.3x and also above the JP Semiconductor industry average of 20.6x, which indicates the stock is priced more aggressively than many local rivals. The estimated Fair P/E of 22.8x is also below the current level. This gap indicates the valuation could move closer to that lower multiple if expectations cool.
Explore the SWS fair ratio for Tokyo Seimitsu.
Result: Price-to-Earnings of 27.2x (OVERVALUED)
Still, the premium on Tokyo Seimitsu could be vulnerable if AI equipment demand normalises faster than expected, or if chip capital spending guidance softens.
Find out about the key risks to this Tokyo Seimitsu narrative.
Another View Using The SWS DCF Model
The P/E premium is only one lens. Our DCF model, which estimates the present value of Tokyo Seimitsu's projected cash flows, points to a value of ¥13,118 per share versus the current ¥17,565 level. That result suggests the stock screens as overvalued on this framework. So which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
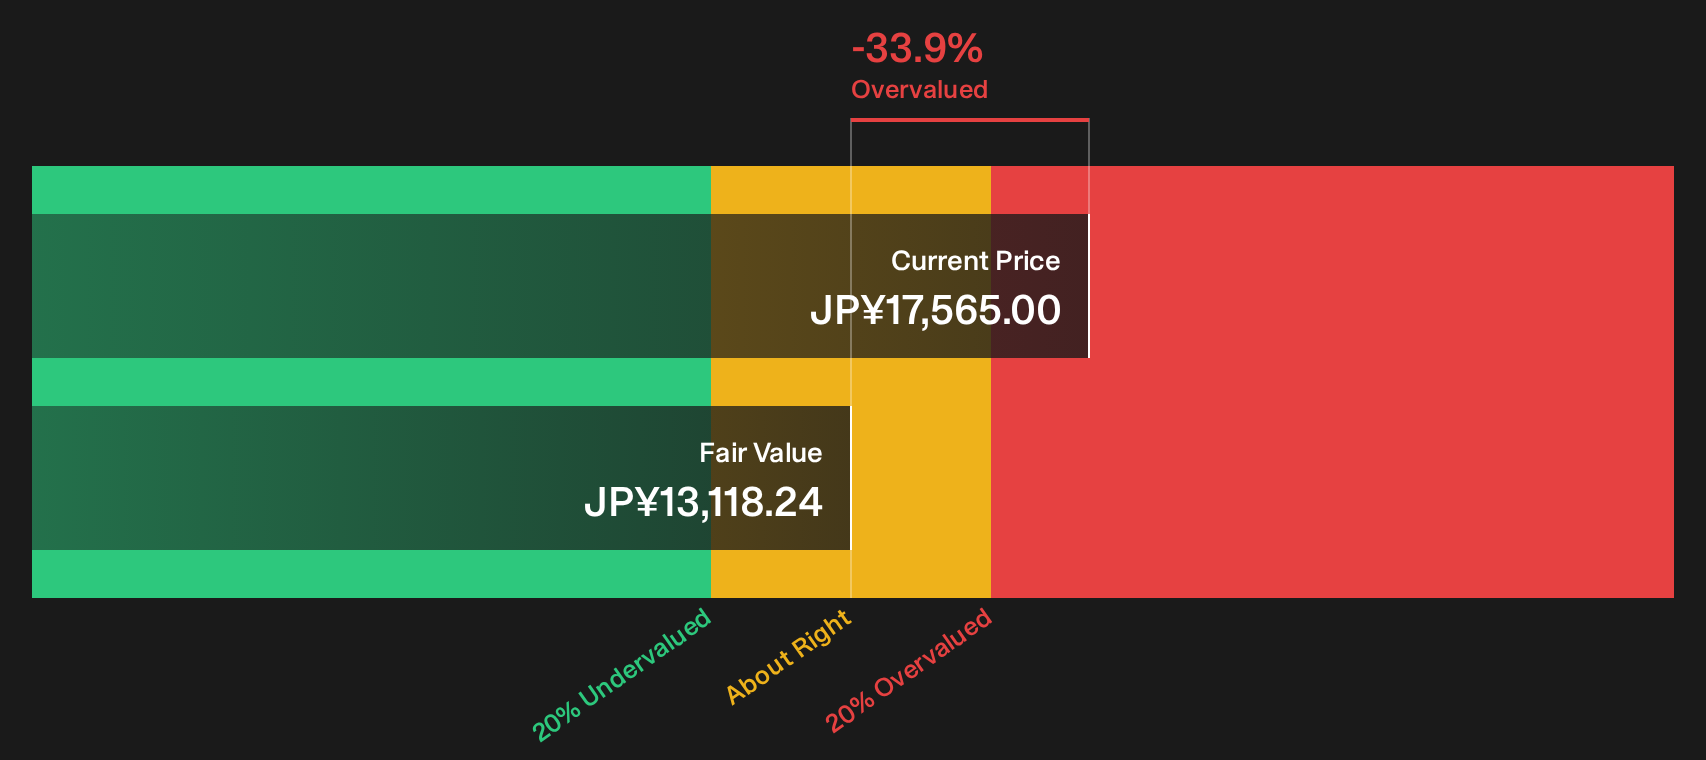
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Seimitsu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Tokyo Seimitsu's valuation can make it hard to know what matters most. Act quickly, review the full risk and reward profile, and decide where you stand with 2 key rewards and 1 important warning sign
Hunting For More Ideas Beyond Tokyo Seimitsu?
Do not stop your research with Tokyo Seimitsu. Broader context across sectors and styles can sharpen judgment and reveal opportunities that a single stock simply will not show.
- Target resilient cash generators and scan a 13 high quality undervalued stocks that blend solid fundamentals with prices that many investors may be overlooking.
- Build steadier income potential and review a 29 dividend fortresses that focuses on companies offering higher yields with a focus on durability.
- Strengthen your downside protection and comb through a 22 resilient stocks with low risk scores that highlights businesses with more robust balance sheets and risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com