
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Backlog Driven Cash Flow Growth Altering The Investment Case For American Superconductor Stock?
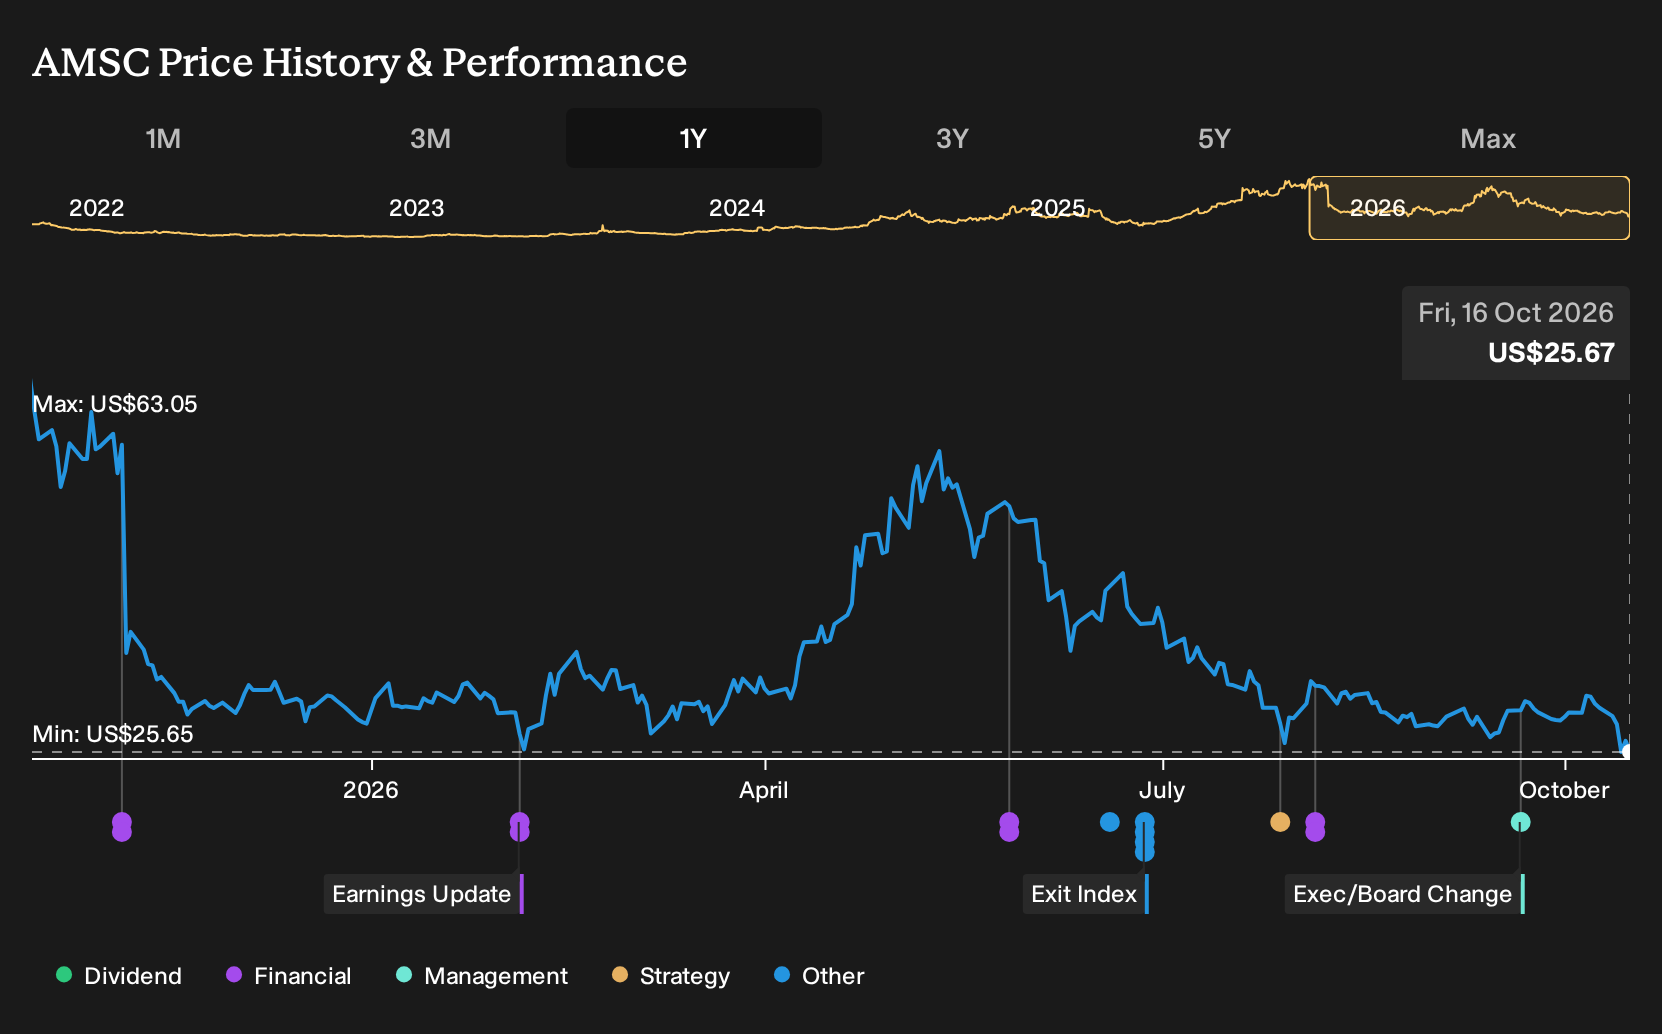
- American Superconductor has attracted fresh attention after commentary highlighted expectations for stronger cash generation from large grid and renewable equipment orders, supported by a sizable backlog.
- An interesting angle is how investor focus has shifted to whether American Superconductor can turn bulky grid and materials projects into steadier, recurring cash flows.
- We will examine how American Superconductor's investment narrative is influenced by expectations for sustainable cash flow growth from its power grid backlog.
Scan opportunities that follow the same grid and electrification theme as American Superconductor by comparing hand-picked 42 power grid technology and infrastructure stocks with what you see developing in AMSC's order book and backlog.
American Superconductor Investment Narrative Recap
To own American Superconductor, an investor needs to believe that its grid and wind hardware can translate a large backlog into consistent, repeatable cash generation rather than lumpy project income. The recent focus on cash flow expectations through the early 2030s mainly sharpens attention on execution, not the underlying grid and electrification theme itself.
The key short term swing factor is whether order timing and product mix keep factory utilization high enough to support the current cost base. The biggest risk sits on the other side of that coin. If one off semiconductor or energy orders fade and utilization normalizes, margins and earnings quality could look far less robust.
With no new formal announcements disclosed alongside this move in American Superconductor, the most relevant reference point is still the existing commentary around its backlog and project mix. Investors are effectively treating that pipeline as the bridge between today’s lumpy projects and the aspiration for steadier cash inflows.
That puts execution squarely in focus. The grid and materials equipment already on order needs to convert into on time deliveries, clean collections, and repeat customer demand. Any stumble in integrating higher margin technologies, managing R&D and SG&A, or balancing exposure to cyclical sectors like semiconductors could quickly test the current bullish cash flow narrative.
American Superconductor's narrative projects US$487.7 million revenue and US$75.3 million earnings by 2029. This implies 17.7% yearly revenue growth and an earnings decline of US$58.5 million from US$133.8 million today.
Uncover why American Superconductor's fair value indicates a 155% potential upside to its current price before that valuation gap starts to close.
Exploring Other Perspectives
You might read the excitement around American Superconductor and focus on backlog quality, yet the most bearish analysts worry more about delay risk. They were pencilling in about US$507.4 million in revenue and US$54.0 million in earnings by 2029, far below today. That paints a cooler story. Use that gap as a prompt to explore several competing views before reacting to the latest news.
Explore 4 other American Superconductor fair value estimates, including one that suggests it could be worth just $38.04!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Superconductor research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Superconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Superconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Superconductor?
If the American Superconductor story has sharpened your thinking about grids, cash flow quality, and risk, it can help to line that up against other opportunities using the Simply Wall St Screener.
- Focus on quality at a reasonable price by scanning a curated set of 33 high quality undervalued stocks that combine fundamentals with a margin of safety.
- Prefer resilience over excitement and compare American Superconductor with 32 resilient stocks with low risk scores that score well on business stability and financial risk.
- If balance sheet strength is a priority for you, broaden your watchlist with a list of solid balance sheet and fundamentals (25 results) to see which companies pair financial flexibility with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com