
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
New GaN Power Chip Launch Might Change The Case For Investing In Renesas Electronics Stock
- Renesas Electronics recently introduced its first 100 V E-mode GaN-based discrete power transistors, aimed at efficiency focused, high power density uses such as AI data centers, humanoid robotics, factory automation and solar microinverters, with packages designed to drop into existing silicon MOSFET layouts.
- The new low voltage GaN family targets up to 40 to 70% lower switching losses and roughly double power density, giving Renesas Electronics a way to address tighter energy budgets and space constraints in AI infrastructure and industrial systems while keeping a silicon compatible footprint.
- We will look at how Renesas Electronics' investment narrative is shaped by this low voltage GaN push into AI power architectures.
Scan beyond Renesas Electronics and review hand picked power and AI infrastructure plays with the 55 AI infrastructure stocks that could benefit from similar efficiency focused hardware shifts.
Renesas Electronics Investment Narrative Recap
To own Renesas Electronics, you need to believe the company can turn its heavy R&D and SG&A spending into durable earnings from AI infrastructure, automotive and industrial chips. The new low voltage GaN launch supports that broader push into AI power, but the key near term driver still looks like execution on AI data center design wins rather than this single product family.
The biggest operational risk remains that elevated investment and the patent dispute around GaN devices weigh on margins if AI and infrastructure sales do not ramp as planned. This GaN expansion helps validate Renesas Electronics' technology roadmap but does not by itself change that risk reward balance in the short term.
The most relevant recent move is Renesas Electronics' broader build out of GaN based power devices for AI data center architectures, with 100 V and 650 V products already sampling and management planning mass production in mid 2027. The new 100 V E mode GaN FETs plug directly into that roadmap by targeting efficiency focused AI power stages and industrial supplies.
For you as a shareholder, the link between the earlier GaN sampling plan and this low voltage expansion is whether Renesas Electronics can convert a wider GaN portfolio into higher content per AI accelerator system. Execution risk stays elevated because of the ongoing patent case and high spending, but each incremental GaN release gives the business more tools to compete for those sockets.
Renesas Electronics' current analyst narrative points to revenues of ¥2,030.5b and earnings of ¥433.4b by 2029, built on an assumed 11.0% yearly revenue growth rate and an earnings uplift of about ¥92.5b from earnings today of ¥340.9b.
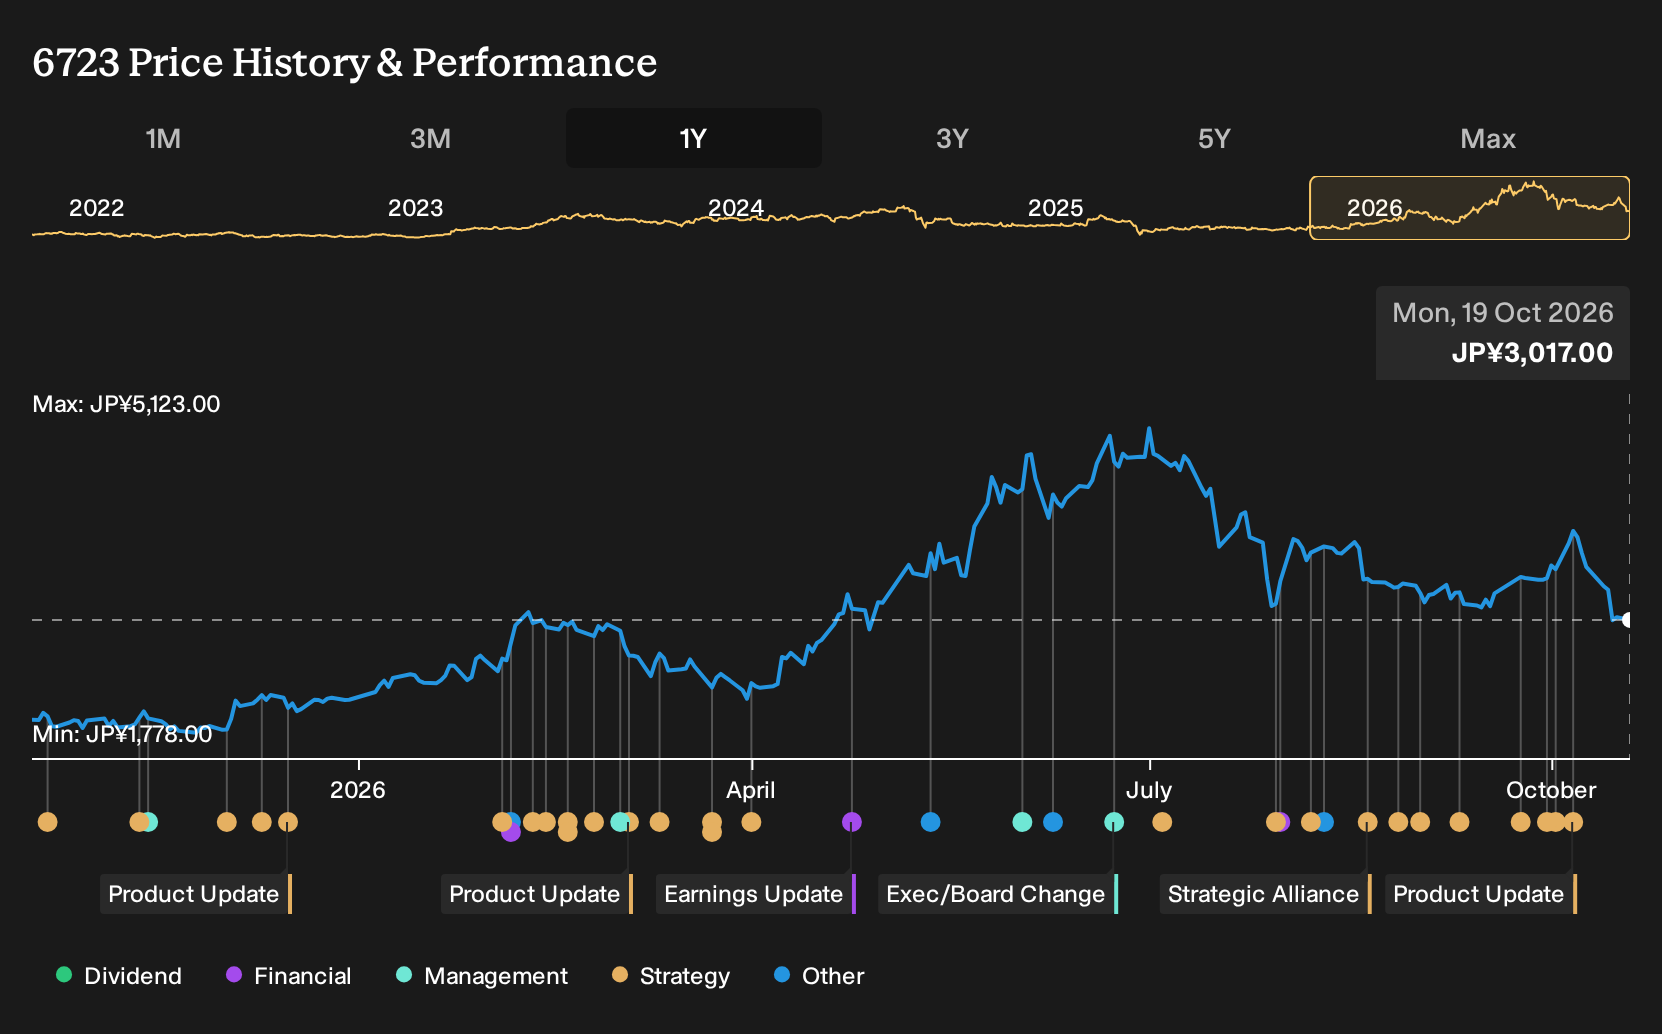
Uncover why Renesas Electronics' fair value indicates a 67% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One sharp contrast in the Renesas Electronics story is capacity risk. The most cautious analysts worry that large AI focused capex and the Takasaki transition create room for underused factories. Before this GaN news, their models sat around ¥1,681.1b in 2029 revenue and ¥323.7b in earnings. This is a much lower bar that could shift if sentiment changes.
Explore 2 other Renesas Electronics fair value estimates, including one that suggests as much as 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Renesas Electronics research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Renesas Electronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renesas Electronics' overall financial health at a glance.
Looking for more investment ideas beyond Renesas Electronics?
If the Renesas Electronics story has you thinking more broadly about where to put fresh capital, it can help to line it up against other candidates that fit different risk and income profiles.
- For investors who want potential upside without paying up for quality, scan a curated pool of companies trading below many fundamental estimates through the 13 high quality undervalued stocks.
- If capital preservation sits high on your list, narrow your search to businesses with sturdier financial footing and lower risk scores using the 22 resilient stocks with low risk scores.
- When you are hunting for fresh ideas with solid fundamentals that are not yet widely followed, cast a wider net with the 73 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com