
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed ASUSTeK Computer's Run? What Holders Had To Believe
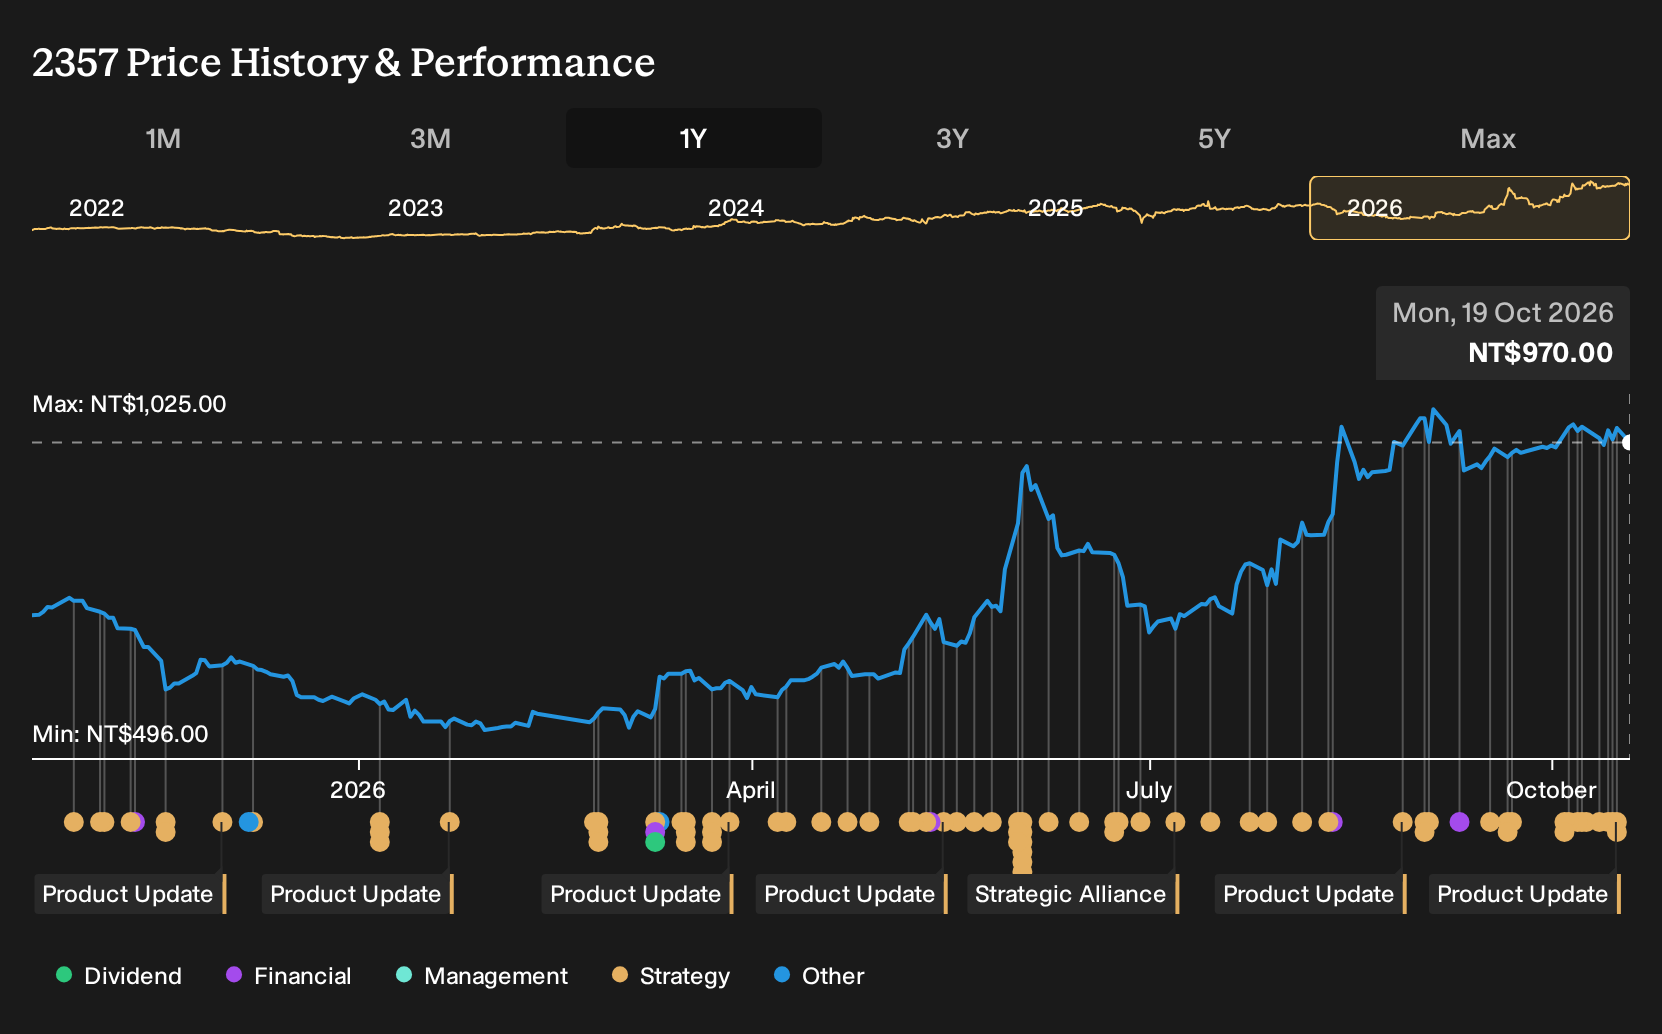
The ASUS ROG G1000 desktop, built around AMD’s Ryzen 9 9950X3D and NVIDIA’s RTX 5080, shows how ASUSTeK Computer leaned hard into high-end gaming and creator hardware during the year. Holding ASUSTeK Computer over the past year would have returned 50.0%, including dividends. If you had been deciding back on 19 October 2025, what would you have needed to believe about AI PCs, gaming demand and ASUS’s margins for that outcome to seem reasonable?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind ASUSTeK Computer. Zero in on 194 high quality undervalued stocks for companies trading below our estimates.
The Two Stories ASUSTeK Computer Investors Had To Weigh
The shares cost NT$687 at the start, so anyone looking at ASUSTeK Computer then had to pick between two very different but plausible stories.
The bullish Narrative put Fair Value at NT$856, assuming AI PCs, RTX 50 series demand, and emerging market expansion would support revenue growth of 15.4% a year and justify a 15.2x P/E on assumed 2028 earnings.
The bearish view set Fair Value at NT$615, arguing that cloud services, tougher Chinese competitors, and hardware commoditisation would cap annual sales growth at 9.5% and compress the assumed 2028 P/E to 8.7x.
What The Results Changed For ASUSTeK Computer
ASUSTeK Computer rolled out the ROG G1000 desktop and new creator focused ProArt laptops, which leaned toward the bullish story about premium AI PCs and gaming hardware. At the same time, total revenue reached NT$257,731.987 million in Q2 2026 and net income came in at NT$19,047.836 million, with net margin at 7.4%. The evidence cut both ways.
The lesson is simple. When a thesis hangs on AI hardware and margins, you track product launches alongside net margin and profit per quarter to see if the story is actually turning into cash.
What ASUSTeK Computer’s Price Already Assumes
ASUSTeK Computer now trades at NT$968 after a 50.0% gain over the past year. The selected Narrative’s Fair Value sits below that level, because it treats today’s valuation as already crediting the group with effective scaling of AI servers, premium PCs and commercial hardware.
Anyone paying today’s price effectively assumes ASUS can keep its higher margin mix intact while growing AI infrastructure and premium PCs. The Narrative examines how that belief holds up if memory inflation, tight CPU supply and stockpiling put pressure on earnings and cash generation.
"The main requirement is that ASUSTeK Computer maintains its higher margin mix in gaming, AI infrastructure and commercial PCs while component costs and supply constraints persist. The current valuation suggests the market is already pricing ASUSTeK Computer for successful scaling of AI infrastructure, a premium PC mix and commercial expansion, despite memory inflation risks and consumer PC headwinds."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Where ASUSTeK’s Demand Flows Next
ASUSTeK’s push into AI PCs and gaming rigs leans on one thing. Those machines must move data quickly inside data centers.
The same hunger for speed appears when cloud providers build AI clusters. They look for networking gear that can handle dense, chatty workloads.
One specialist focuses on Ethernet based switches and software built for that job. Its operating system links many ports into a single, programmable fabric.
As AI builds become larger and more complex, tight network control could matter more. It leaves a different angle on the AI hardware story you just followed.
One Narrative has already put a figure on it. → Uncover the company trading 27% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com