
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Microchip Technology (MCHP) Could Be 32% Undervalued Following AI And Automotive Expansion
Microchip Technology (MCHP) has been busy on the product and partnership front. Recent announcements span automotive software with Elektrobit, new space-grade power devices, and PCIe Gen 6 data center hardware introductions.
Despite this stream of product and partnership announcements, Microchip Technology’s share price has moved more modestly, with the stock up 13.56% on a year to date share price basis and a 12.99% total shareholder return over the past year. This suggests solid but not surging momentum as investors weigh new growth avenues against existing risks.
Spot emerging peers riding the same AI data center and automotive themes as Microchip Technology by scanning our hand picked 55 AI infrastructure stocks.Microchip Technology’s shares have climbed, yet the gap between the current US$73.85 price and published fair value estimates remains wide. Is that discount pointing to opportunity, or reflecting unresolved risk in the story ahead?
Most Popular Narrative: 32% Undervalued
Microchip Technology’s most followed valuation storyline pegs fair value at $108.64, well above the last close at $73.85. This puts the current discount under a spotlight for anyone tracking AI, aerospace and industrial exposure together.
Microchip Technology is seeing structural expansion in data center and AI infrastructure exposure, with total data center revenue expected to increase from about US$591 million in 2025 to roughly US$1 billion in 2026 and PCIe Gen6 design wins, including an estimated US$100 million annual program starting in 2027, which together point to a larger contribution to future revenue.
See why 57 investors see Microchip Technology as 32% undervalued.
The narrative framework uses an 11.88% discount rate and arrives at a fair value of $108.64. This is materially above both the last close and the $72 output from the SWS DCF model that values only projected cash flows. That gap reflects how much weight this storyline puts on higher margin mix from data center, aerospace and defense, and edge AI, compared to a cash flow model that is more tightly tied to current profitability and existing capital intensity.
Result: Fair Value of $108.64 (UNDERVALUED)
Still, Microchip Technology carries elevated inventories and ongoing write offs, and external foundry and packaging constraints could restrict how much AI and aerospace demand actually turns into revenue.
Find out about the key risks to this Microchip Technology narrative.
Another View On Microchip Technology’s Valuation
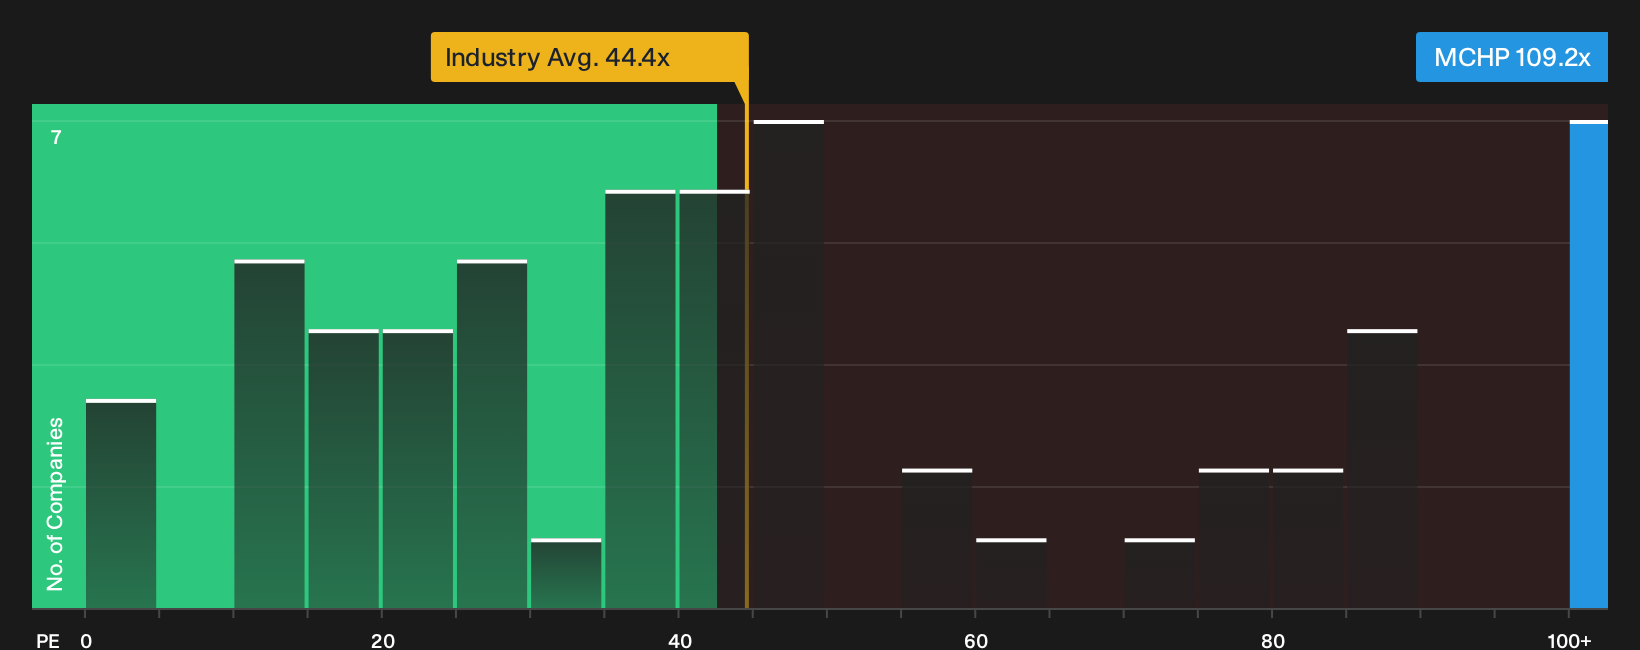
That 32% “undervalued” storyline looks very different through the P/E lens. Microchip Technology trades on roughly 109x earnings, compared with about 44x for the US Semiconductor group and a fair ratio of 35x. That spread points to meaningful valuation risk if sentiment or forecasts slip.
For a closer look at how those earnings multiples stack up in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Microchip Technology so far. If the push and pull between risks and rewards feels unresolved, review the underlying data, consider both sides, and form your own view using the balance of 3 key rewards and 2 important warning signs
Looking for more Microchip Technology style investment ideas?
You have Microchip Technology on your radar already, so do not stop there. Use the Simply Wall Street Screener to uncover more focused opportunities that fit your style.
- Target potential mispricing by scanning a curated set of 33 high quality undervalued stocks that pair quality fundamentals with discounted market expectations.
- Prioritize income and resilience by reviewing a group of 8 dividend fortresses that combine high yields with robust underlying businesses.
- Dial down portfolio stress by focusing on 32 resilient stocks with low risk scores designed to limit downside according to Simply Wall Street's risk scoring.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com