
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Analyst Scrutiny Change Sirius XM Stock Narrative
- Sirius XM Holdings is under closer analyst review after years of roughly flat revenue, a projected step down in free cash flow margins, and weaker returns on invested capital, alongside a renewed content push such as a two year extension for Jeff Lewis Live on Radio Andy.
- The tension between a large installed car audience and fewer clearly profitable expansion options highlights how heavily Sirius XM Holdings now leans on content stickiness and digital monetization to defend cash generation.
- We will now look at how Sirius XM Holdings' investment narrative is affected by tighter free cash flow margins and softer returns.
Compare Sirius XM Holdings' content dependent model with other media and subscription players that score well on cash generation and balance sheets using the curated list of solid balance sheet and fundamentals (25 results).
Sirius XM Holdings Investment Narrative Recap
To own Sirius XM Holdings today, you need to believe the large in-car audience, steady but slow-moving top line, and audio advertising ambitions can together support decent cash generation even as free cash flow margins tighten. The key near-term swing factor remains execution on digital engagement and ad monetization while keeping churn low in a market that favors on-demand streaming rivals.
The biggest risk is that both subscription and advertising revenue streams keep softening, with subscriber erosion and high debt making it harder to protect earnings if sentiment worsens. The latest analyst scrutiny around flat revenue and weaker returns on invested capital mostly sharpens focus on that existing risk rather than creating a new one.
The recent two-year extension for Jeff Lewis Live on Radio Andy captures what matters operationally for Sirius XM Holdings right now. Management is doubling down on exclusive, personality-driven programming that keeps long-tenured subscribers listening in the car and nudges them toward the app and companion plans instead of drifting entirely to competing streaming services.
This kind of renewal does not reset the financial story on its own. It is one tile in a larger mosaic of content investments, digital features, and cost programs that together could influence whether the audio advertising platform, including podcasting and broader off-platform listening, becomes a material earnings contributor or whether revenue pressure and spectrum monetization risk stay front of mind.
Sirius XM Holdings' current analyst script points to revenues of US$9.2b and earnings of US$1.2b by 2029, based on an assumed 2.1% yearly revenue growth rate and an earnings increase of about US$320m from US$880m today.
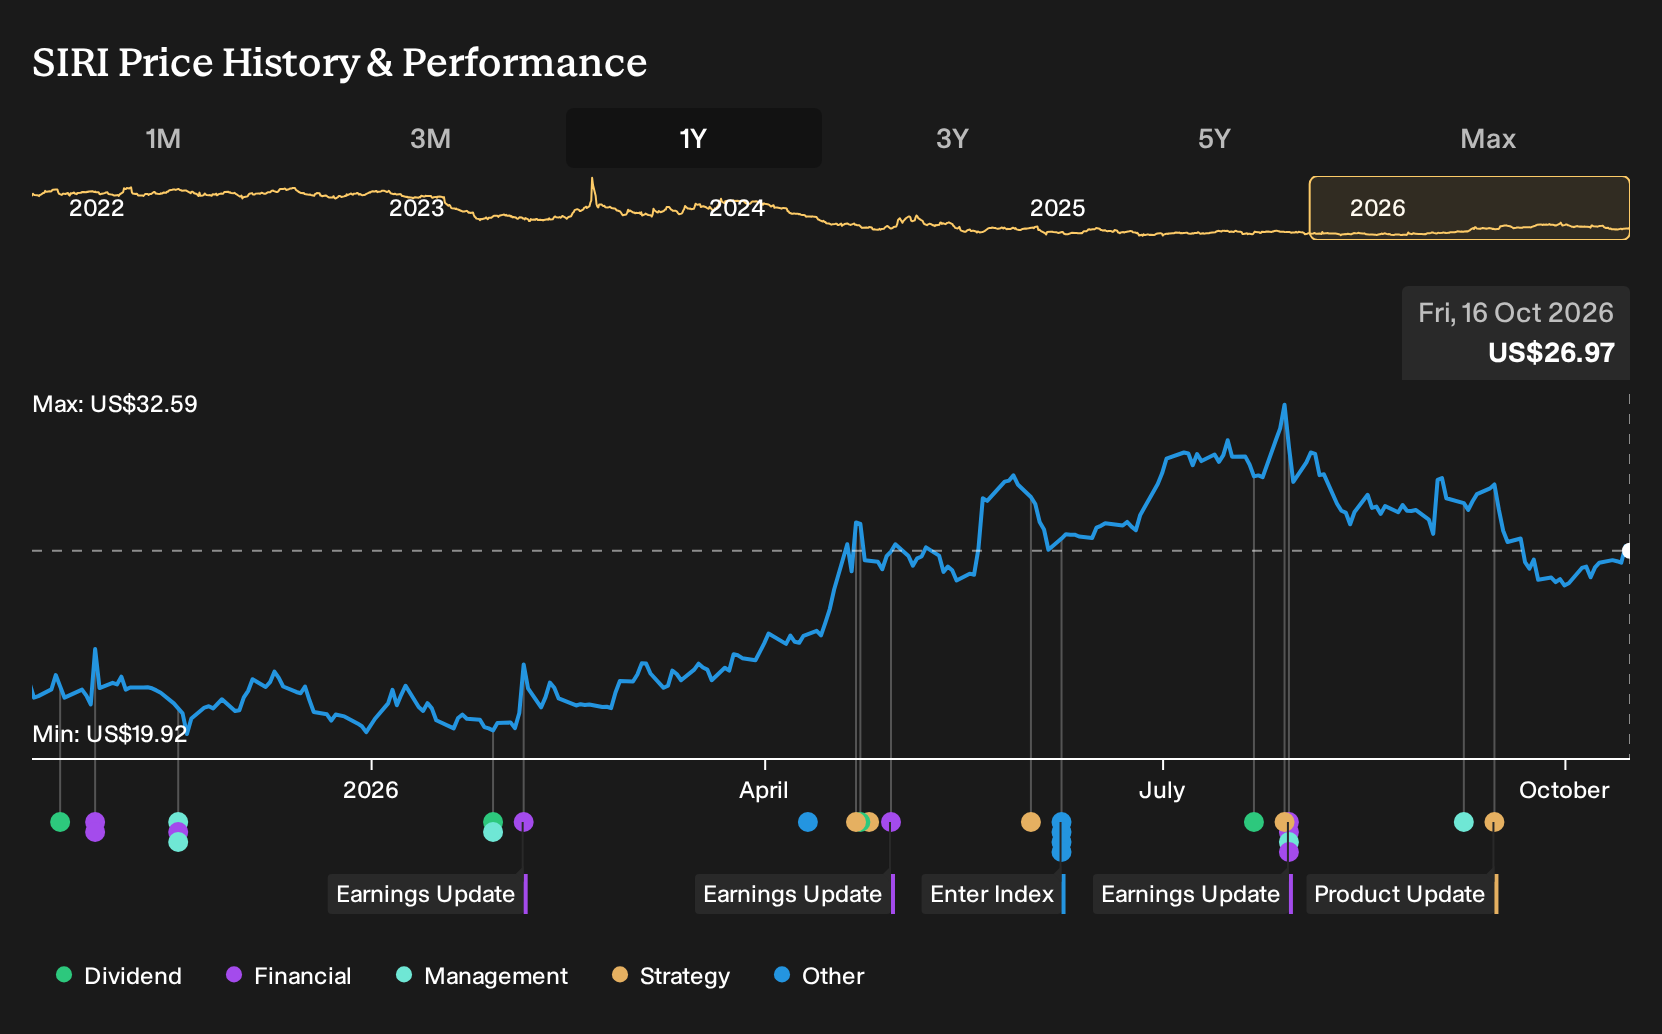
Uncover why Sirius XM Holdings' fair value indicates a 23% potential upside to its current price, which could narrow quickly as sentiment shifts.
Exploring Other Perspectives
One alternate angle on Sirius XM Holdings puts spectrum monetization at the center. Bullish analysts were sketching out revenue of about US$10.3b and earnings near US$1.3b by 2029, tied partly to that 35 MHz asset. Those projections came before this content renewal, so your own view might shift as the story evolves.
Explore 7 other Sirius XM Holdings fair value estimates, including one that suggests up to 70% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sirius XM Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sirius XM Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sirius XM Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Sirius XM Holdings?
If the Sirius XM Holdings story has sharpened your thinking about cash generation, risk and capital allocation, you can use that same lens to compare other potential opportunities using the Simply Wall St Screener.
- If you want potential mispricings backed by solid fundamentals, start with a curated group of 33 high quality undervalued stocks that combine quality with attractive valuations.
- If capital preservation and steadier profiles matter more to you, consider a 32 resilient stocks with low risk scores that filters for businesses with more resilient risk profiles.
- If you enjoy hunting for earlier stage opportunities with stronger balance sheets and cleaner financials, take a look at a focused 14 elite penny stocks with strong financials list that screens for financial strength first.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com