
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Affirm Holdings (AFRM) Stock Dropped, What Is Behind The Latest Attention?
Affirm’s Antom partnership reshapes the pay over time story
Affirm Holdings (AFRM) just flipped a new switch on its growth narrative, rolling out its pay over time checkout service across Antom’s U.S. merchant network as part of a fresh partnership.
Affirm Holdings has ridden a volatile path to its current US$74.01 share price, with a 30-day share price return of 3.93% but a 7-day decline of 5.88% as traders weigh this Antom rollout against a three-year total shareholder return of roughly 3x and a five-year total shareholder loss of 53.76%. This suggests that long term holders have experienced both strong momentum phases and sharp reversals as sentiment around growth potential and risk has shifted.
Scan other pay-over-time players with similar momentum and risk profiles by reviewing the hand picked 33 high quality undervalued stocks, which may sit at more conservative valuations than Affirm Holdings.
The Antom deal has pushed Affirm Holdings back into the spotlight, yet the share price still trails average analyst targets while internal models flag a premium to intrinsic value. Where does fair value actually sit in that gap?
Most Popular Narrative: 25% Undervalued
Affirm Holdings is priced at $74.01 while the most followed narrative anchors fair value at $99.23. This creates a wide valuation gap that the Antom rollout now tests against analyst conviction and long term unit economics.
Rapid growth and strong engagement with Affirm Card, an actively invested product moving toward high attach rates and greater offline usage, expands Affirm's addressable market beyond online retail, diversifies revenue streams, and drives higher frequency of transactions, which should accelerate GMV and contribute to margin improvement.
See why 52 investors see Affirm Holdings as 25% undervalued.
Result: Fair Value of $99.23 (UNDERVALUED)
Still, the narrative around Affirm Holdings could be knocked off course if a large merchant partner walks away or if competition squeezes margins on 0% APR products.
Find out about the key risks to this Affirm Holdings narrative.
Another View: SWS DCF model points to less upside
Affirm Holdings might look undervalued against the $99.23 narrative fair value, yet the SWS DCF model paints a cooler picture. On that cash flow view, estimated worth sits at $61.60 per share, which places today’s $74.01 quote in overvalued territory. Which yardstick do you trust more?
For a closer look at how cash flow assumptions drive that result, Look into how the SWS DCF model arrives at its fair value.
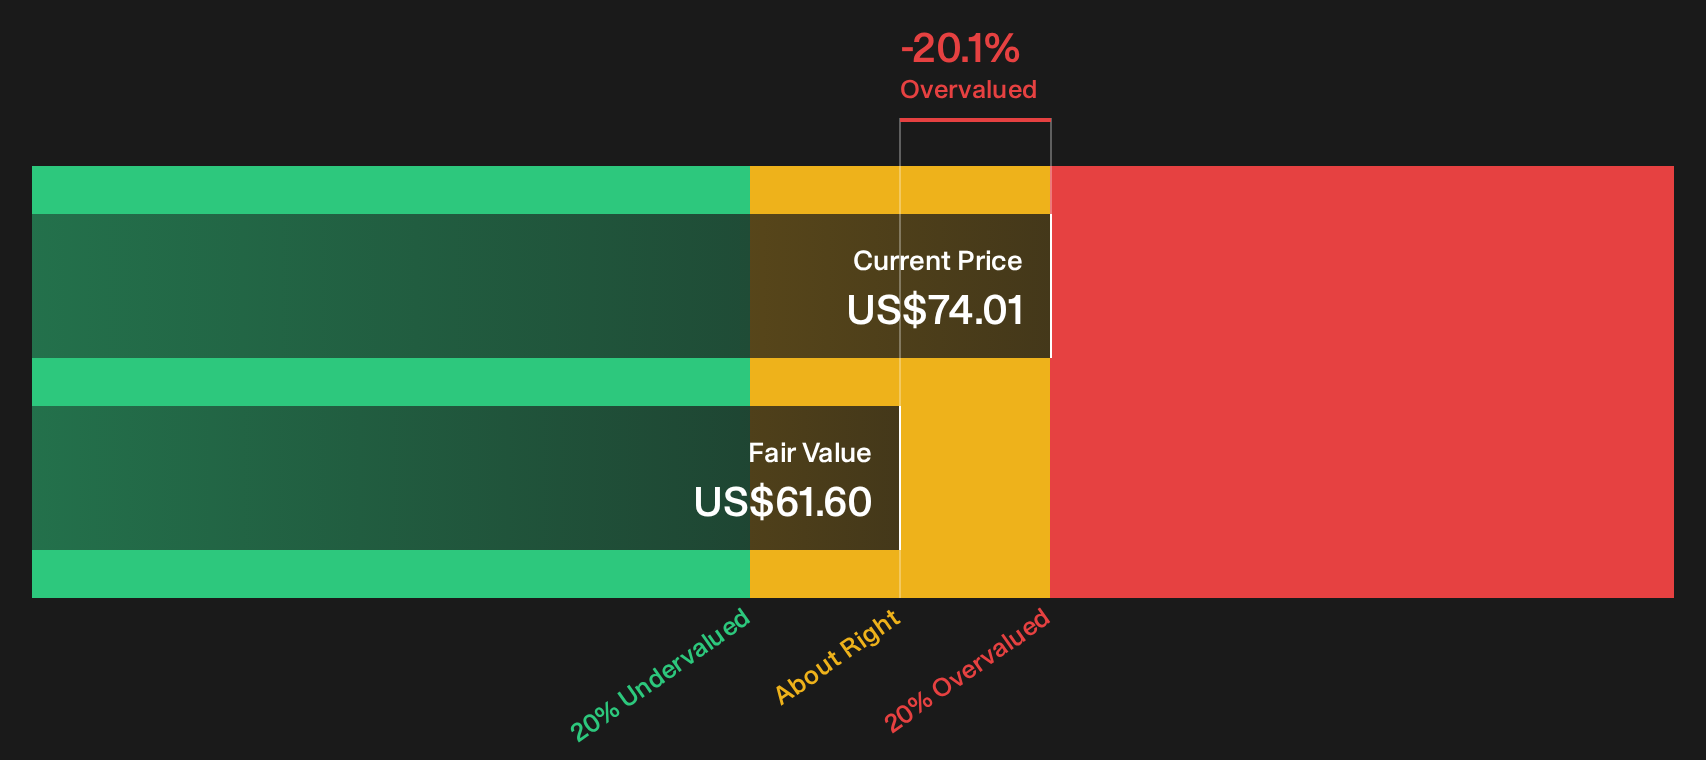
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Affirm Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Affirm Holdings story today or just competing playbooks. Move fast, examine the same data, then weigh the 5 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Affirm Holdings?
If Affirm Holdings has you rethinking what belongs in your portfolio, do not stop here. Broaden your watchlist with a few targeted screens that surface very different kinds of opportunities.
- Hunt for mispriced potential by scanning the 33 high quality undervalued stocks, which pair strong fundamentals with more restrained valuations than high profile growth stories.
- Build dependable cash flow into your holdings by reviewing the 8 dividend fortresses, which focus on higher yielding businesses aiming to maintain their payouts.
- Dial down volatility risk by filtering through the 32 resilient stocks with low risk scores to highlight companies with sturdier balance sheets and more stable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com