
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Andritz Bulls Got Right
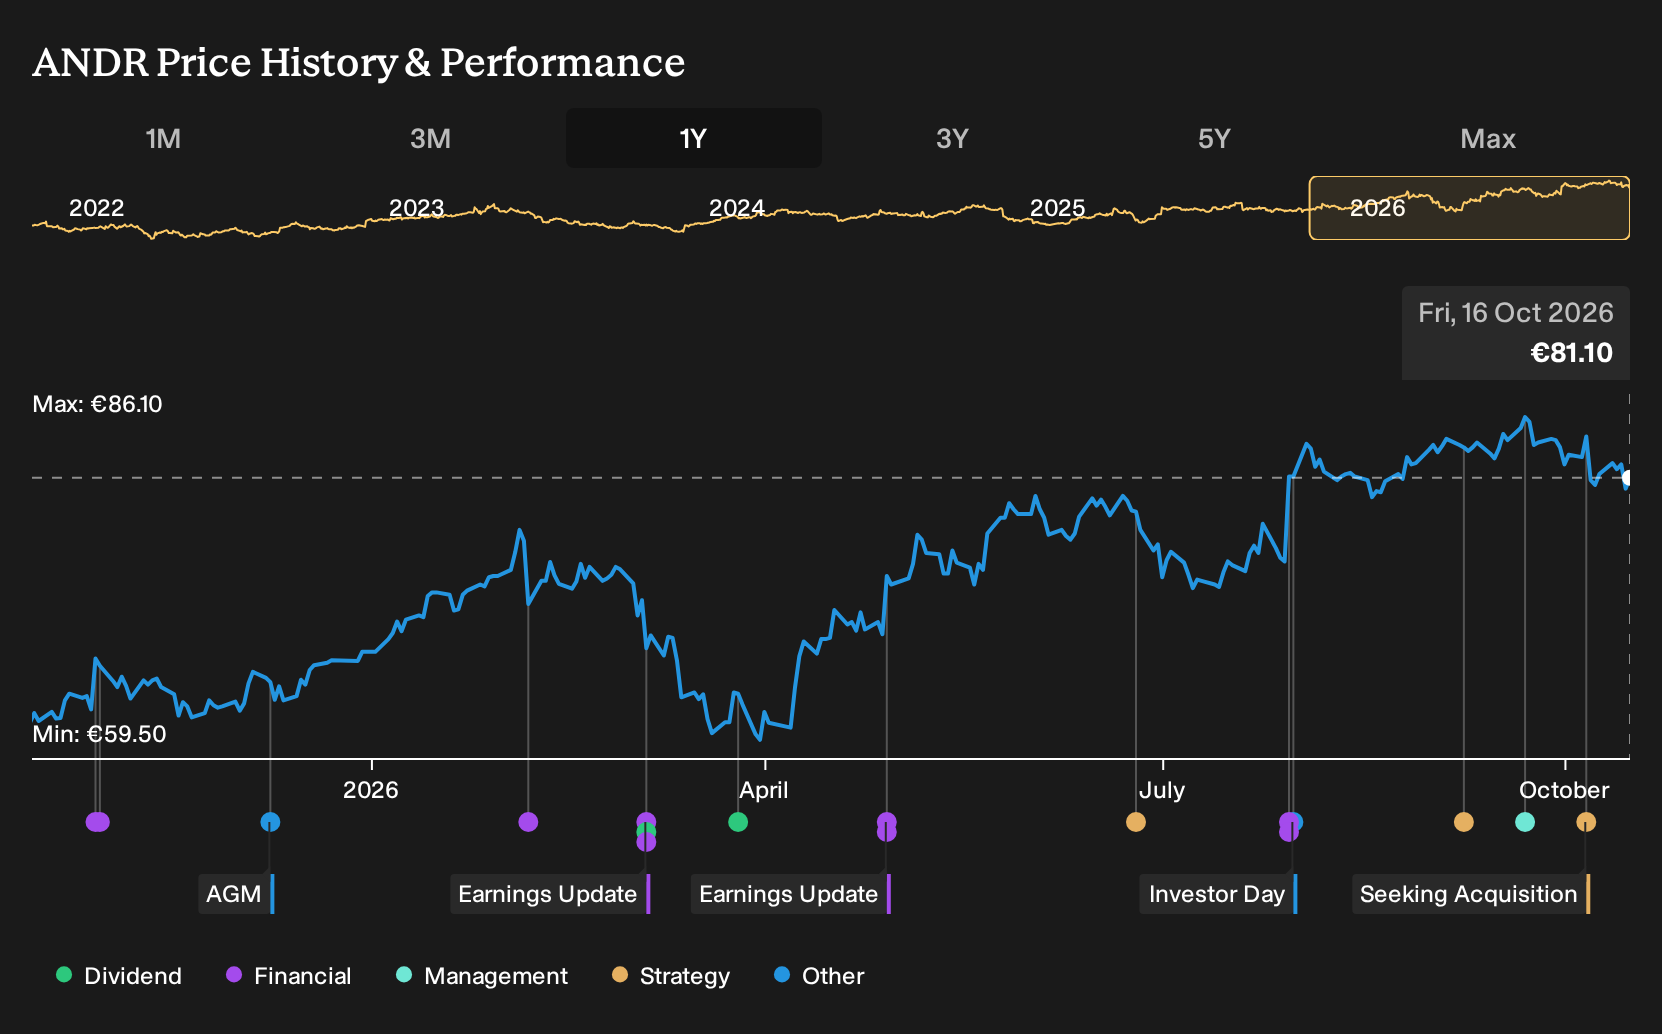
Analysts argued fiercely over Andritz in late 2025, even as its order backlog and service mix on one side and legacy hydropower and pulp exposure on the other pointed in opposite directions. Holding Andritz over the past year would have returned 37.2%, including dividends. If you had been weighing those bullish and bearish reports back on 16 October 2025, what should you have focused on to judge whether that payoff was worth the risk?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The move put Andritz in the middle of this trade. Scan 42 power grid technology and infrastructure stocks for other companies exposed to it.
The Two Stories Andritz Investors Had To Weigh
The shares cost €61.7 at the start of the period, and anyone looking at Andritz then had to pick between two very different stories that both sounded reasonable.
On the optimistic side, the Simply Wall St Narrative pointed to a Fair Value of €70.56 supported by strong order intake, a record €10.4b backlog and a bigger contribution from services at 44% of revenue.
The cautious view put Fair Value at €43 and stressed the risk that legacy hydropower and pulp offerings might lag new automation and environmental technologies while compliance and restructuring costs pressed on margins.
What The Evidence Did To The Andritz Argument
The Q2 2026 report showed Andritz with revenue of €2,050.7m and net income of €109m, both above Q2 2025, which backed the optimistic case that the backlog could convert into higher sales and profit. The small slip in net margin from 5.4% to 5.3% and an executive board change in Environment & Energy kept the cautious thesis alive. Overall, the evidence cut both ways.
The whole debate hinged on whether higher order books and services would translate into cleaner profitability. When you look at another industrial stock, check that rising backlog and sales show up in stable or improving net margin, not just higher revenue.
What You Would Be Paying For In Andritz Today
Today Andritz trades at €81.1 after a 37.2% gain over the past year, and the selected Narrative’s Fair Value sits above that market price based on its own assumptions.
The argument leans heavily on backlog, higher service share and automation as future profit drivers, so you would need to judge whether sustained execution on higher margin services and digital projects still looks realistic.
"The record €12.9b group order backlog in H1 2026, with roughly half tied to longer cycle Hydropower projects, gives Andritz multi year visibility on equipment revenue and follow on service work that can feed into future earnings. Hydropower’s strong order intake of €1.9b in Q1 2026 and 82% year on year growth in H1 2026, alongside management’s ambition to grow grid solutions and synchronous condensers from about €300m toward €1b of revenue over time, point to a larger energy related revenue base and a richer mix for margins."
The price and this Narrative do not agree. → Uncover what this Narrative says Andritz is actually worth
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 35% below our estimate - targets a fast-expanding middle class with digital retail lending and cross-sell platforms.
- Company 2 - 40% below our estimate - shifts case mix toward complex oncology and transplant work supported by an AI enabled backbone.
- Company 3 - 47% below our estimate - leans into sterile injectables and CDMO contracts while integrating heparin sourcing and R&D spending.
Three companies from the same screener. Open all 194 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com