
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Anheuser Busch InBev (ENXTBR:ABI) Stock Still Looks Reasonable For Long Term Earnings
Anheuser-Busch InBev has delivered a strong run in recent years, which naturally puts today's valuation in the spotlight. With the share price where it is now, the real issue is how firmly that move is supported by the brewing giant's earnings power.
- Over the past 5 years the stock has returned 60.1%, so anyone looking at Anheuser-Busch InBev today is effectively asking whether that gain has already captured what its profits can justify.
- The group relies heavily on turning global beer brands and scale into steady margins and cash generation. This can affect how much value investors ascribe to each dollar of earnings over time.
- Your read on Anheuser-Busch InBev is one view; the desks covering it have another. See what analysts think Anheuser-Busch InBev's shares could be worth.
The stock's next move may depend on whether Anheuser-Busch InBev's current price is adequately supported by the earnings it is generating today.
If you want a wider lens on earnings led stories like Anheuser-Busch InBev before you commit fresh capital, start by scanning 194 high quality undervalued stocks.
Is Anheuser-Busch InBev a Bargain on Earnings?
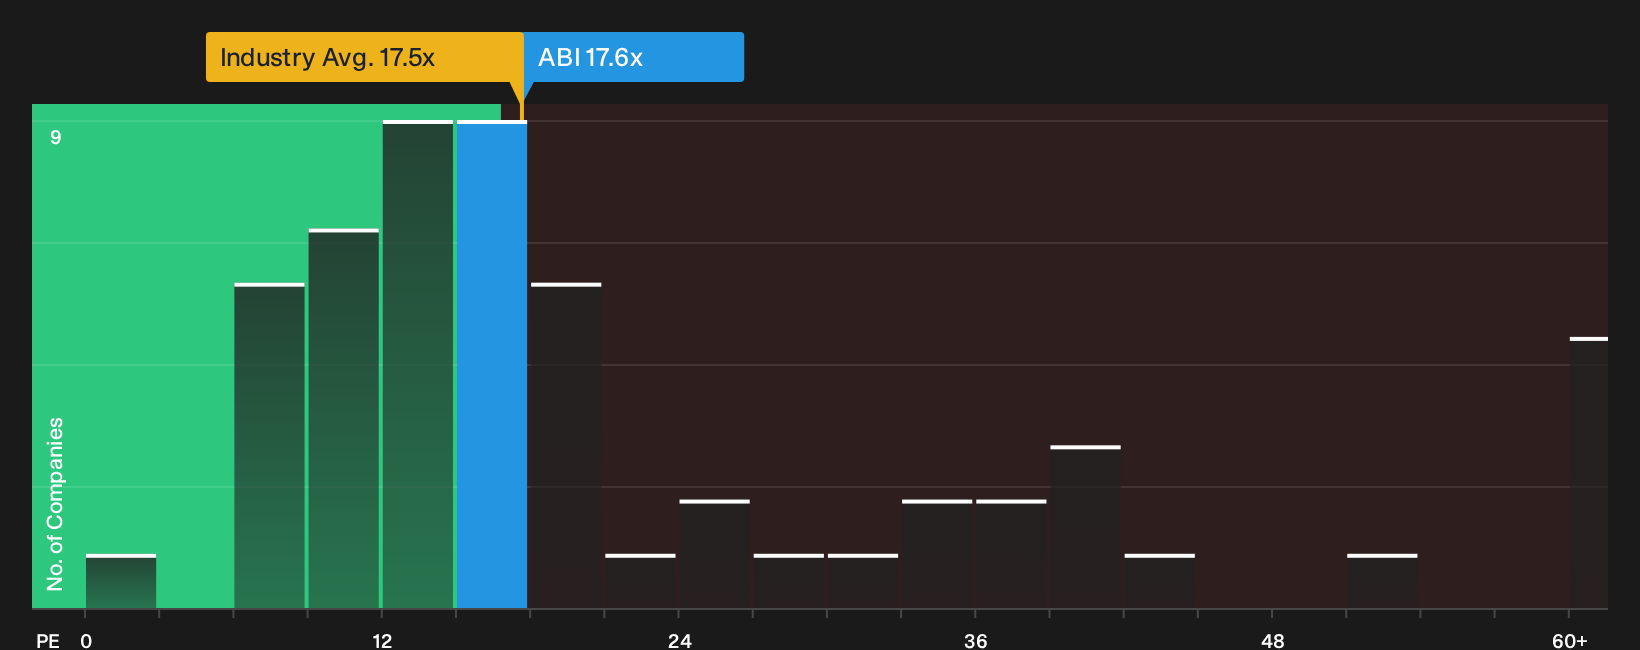
The P/E ratio suits Anheuser-Busch InBev because earnings remain the key lens for a mature consumer brand group. On this metric, the stock trades on about 17.6x earnings, which is slightly above the Beverage industry average of roughly 16.9x. That points to a small premium versus the broader sector, yet still well below the peer group average of about 26.7x, where other listed brewers and drinks groups cluster.
The fair multiple implied by the modelling suggests a higher P/E would be consistent with Anheuser-Busch InBev's profile. As a result, the current 17.6x reading screens as undervalued on this framework. For anyone weighing up the shares, the key question is whether the existing earnings base and its quality justify the gap between this market price and where the tailored benchmark sits, and how much of that difference you are comfortable underwriting. Explore the numbers behind Anheuser-Busch InBev's P/E valuation.
The Anheuser-Busch InBev Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Anheuser-Busch InBev and translate it into clear assumptions about future growth, margins and earnings that would need to hold for the stock to be worth materially more or less than today's price, and sit within the Community page. Where a single multiple or model gives you one number, these narratives spell out the future that number rests on, so you can watch how reality lines up over time.
The Simply Wall St community splits into two camps on Anheuser-Busch InBev, with one group seeing meaningful upside and another viewing the current tag as broadly in line with cautious forecasts.
Bull case: 17% undervalued
"ABI is transitioning into a premiumized portfolio, a more efficient operating system, a deleveraged balance sheet..."
Discover why this Narrative puts Anheuser-Busch InBev at 17% undervalued.
Bear case: 6% overvalued
"This narrative explores a more pessimistic perspective on Anheuser-Busch InBev compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts..."
Explore why this Narrative puts Anheuser-Busch InBev at 6% overvalued.
One last check for Anheuser-Busch InBev before you stop at the share price
Before you focus only on the P/E and community narratives around Anheuser-Busch InBev, it is worth asking who is steering the business and how their incentives line up with your goals. See who runs Anheuser-Busch InBev and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com