
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Mitsubishi Materials (TSE:5711) Undervalued On Its Cutting Tools Sales Reshuffle?
Mitsubishi Materials (TSE:5711) has set up a plan to fold its domestic cutting tools sales operations and those of MOLDINO into a new subsidiary, signaling a meaningful shift in how this business is organized.
Recent trading tells a story of cooling momentum in the short run but strong gains over longer periods. The share price is down 10.9% over the past month and 4.4% over the last week. However, the 1-year total shareholder return of 60.4% and 3-year total shareholder return of 120.6% show that Mitsubishi Materials has still delivered substantial value for patient investors as it moves through this restructuring phase.
Scan how Mitsubishi Materials compares with other Japanese industrials reshaping their operations by running the curated list of solid balance sheet and fundamentals (22 results) as a starting universe.
The share price pullback leaves Mitsubishi Materials trading below both analyst targets and some intrinsic value estimates. Given that gap, and the fresh cutting tools reshuffle, where does a reasonable fair value range actually land?
Preferred P/E of 6.3x for Mitsubishi Materials: Is it justified?
The current picture is striking. Mitsubishi Materials trades on a P/E of 6.3x while the last close sits at ¥4,627 and a separate discounted cash flow estimate suggests a fair value of ¥14,728.24, implying a large gap between price and one modelled cash flow value.
The P/E multiple compares the share price with earnings per share, so a lower ratio can indicate that investors are paying less for each unit of profit. For a diversified materials group that smelts copper, gold, silver and other metals and also sells cemented carbide tools, energy and recycling services, earnings power often drives how the market assigns that earnings tag.
Context matters here. Earnings for Mitsubishi Materials grew very sharply over the past year and are described as high quality, yet the forecast points to slower revenue and earnings progress than the broader Japanese market. That mix suggests the market may be pricing in more muted future profit expansion, even as the current earnings profile and recent acceleration would support a higher level that the fair P/E estimate of 14.7x points toward.
Relative comparisons are clear. The 6.3x P/E is well below the JP Metals and Mining industry average of 11.5x and also beneath the peer average of 10.6x. This signals a materially cheaper earnings tag than sector and peer groups. Against the estimated fair P/E of 14.7x, the current ratio sits at a deep discount that the market could potentially move toward if confidence in consistent profit delivery improves.
Explore the SWS fair ratio for Mitsubishi Materials.
Result: Price-to-earnings of 6.3x (UNDERVALUED)
Still, the recent share price slide and the forecast for slower revenue and earnings progress than the wider Japanese market could challenge any simple undervaluation story for Mitsubishi Materials.
Find out about the key risks to this Mitsubishi Materials narrative.
Another View: What The SWS DCF Model Says
The SWS DCF model paints a very different picture for Mitsubishi Materials. With an estimated value of ¥14,728.24 per share versus a market price of ¥4,627, this approach points to a very large gap. If both models are grounded in the same earnings, which signal carries more weight for you?
Look into how the SWS DCF model arrives at its fair value.
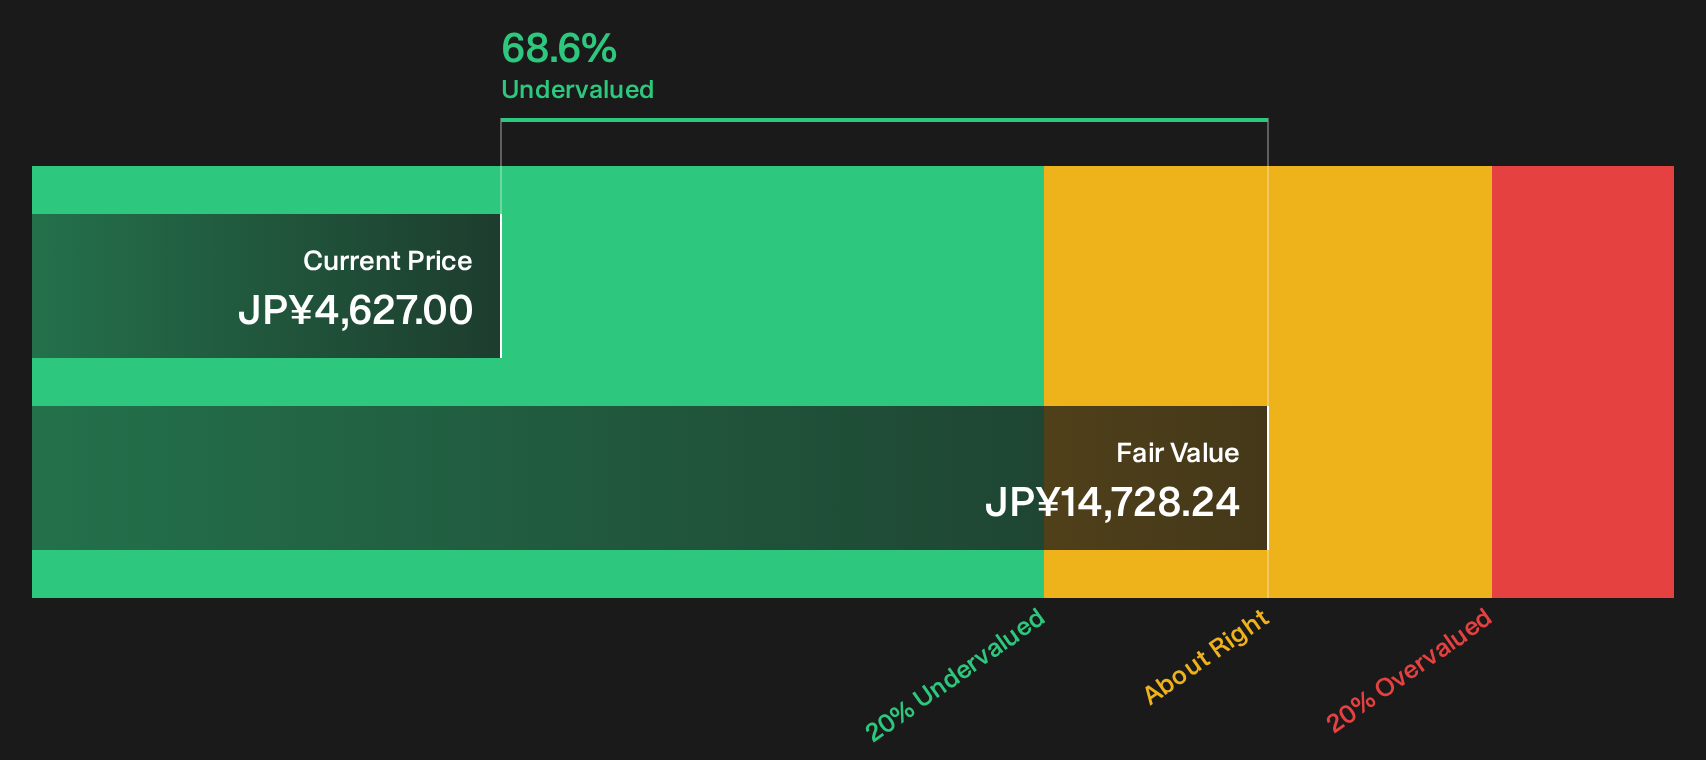
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi Materials for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If you have seen enough mixed signals around Mitsubishi Materials for one sitting and want to apply your own perspective on the story rather than rely on anyone else's view, use the full breakdown of 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Mitsubishi Materials?
Do not stop with Mitsubishi Materials when a wider opportunity set is only a few clicks away and could fit your goals even better.
- Target reliable income streams by scanning companies that meet your yield and stability filters through the 29 dividend fortresses.
- Hunt for quality at a discount by focusing on fundamentally strong businesses that screen as attractively priced in the 13 high quality undervalued stocks.
- Prioritize resilience in your portfolio by filtering for companies with stronger risk profiles using the 22 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com