
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
HP (HPQ) Expands Its AI Hardware Range, Is The Upside Already Priced In?
HP (HPQ) just rolled out a broad refresh of its AI focused hardware, from RTX Spark OmniBook laptops to the NVIDIA GB300 powered ZGX Fury workstation, putting local AI capability directly on PCs and on premises infrastructure.
HP’s latest AI hardware push lands after a choppy stretch for the ticker, with the 1 month share price return down 12.76%, the 90 day share price return up 20.96%, and the year to date share price return at 35.67%, while the 1 year total shareholder return sits at 14.03%. This signals that momentum has cooled recently compared with the stronger gains seen earlier in the year.
Scan HP’s AI push against a wider peer set and see which companies are already leaning into the same trend with the 55 AI infrastructure stocks.
HP has rallied hard this year, then cooled just as the share price moved above the average analyst target and well below some intrinsic value estimates. Where does fair value actually land in that spread?
Most Popular Narrative: 10% Overvalued
On Simply Wall St, the most followed fair value narrative pegs HP at $27.31 using a 9.47% discount rate, compared with the last close at $30.01. This frames the current AI fueled excitement against expectations for more modest long term earnings growth.
The main factor that has to go right is HP converting its AI and cost programs into higher and more stable Personal Systems and Print margins, even as component costs and unit volumes remain under pressure.
The current valuation suggests HP is priced as if AI PCs, services, and cost savings will more than offset print and PC headwinds. This bearish narrative views that as too optimistic for the share price.
See why 61 investors see HP as 10% overvalued.
Result: Fair Value of $27.31 (OVERVALUED)
Still, if HP converts its AI PC mix and cost savings plans into steadier margins, or if recurring services keep widening profit pools, this bearish view could be challenged.
Find out about the key risks to this HP narrative.
Another View: What HP’s P/E Ratio Signals
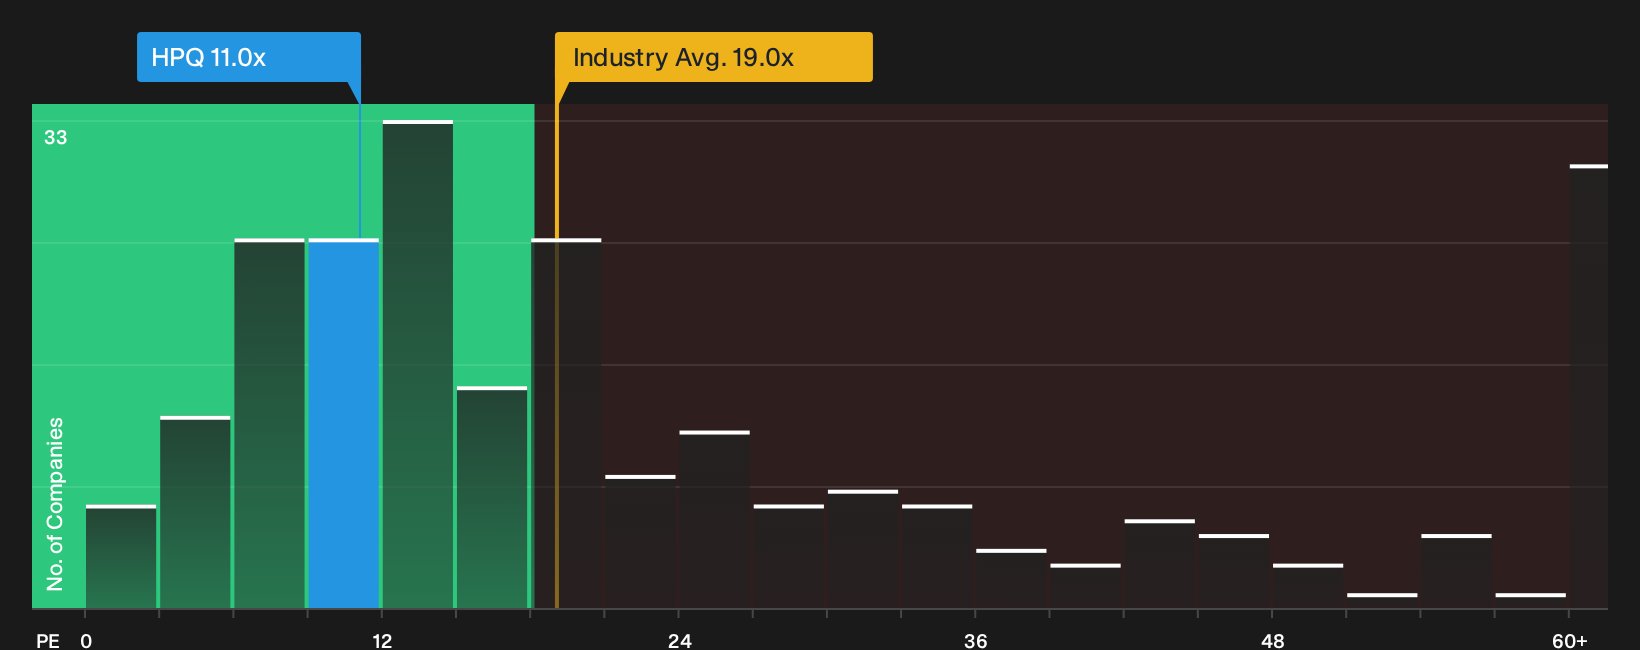
There is a very different message coming from HP’s current pricing. The stock trades on a P/E of 11x, compared with 19x for the global tech industry and 57.1x for close peers, while Simply Wall St’s fair ratio for HP sits at 25.4x.
If the market ever moved HP’s valuation closer to that fair ratio, or even toward the wider sector at 19x, the gap could matter far more than a 10% swing around a single fair value estimate. Which lens do you trust more when those numbers pull in opposite directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on HP’s value story so far. Act while sentiment is still forming and weigh both sides for yourself with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond HP?
If HP has you rethinking where the next opportunity might come from, do not stop here. Cast a wider net and pressure test fresh ideas.
- Target resilient growth by scanning a 20 high quality undiscovered gems list that highlights businesses with strong fundamentals that many investors may still be overlooking.
- Prioritise defense in your portfolio and review a 32 resilient stocks with low risk scores set of companies that score well on resilience and risk controls.
- Dial up quality in your core holdings by working through a list of solid balance sheet and fundamentals (25 results) that focuses on robust finances and durable fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com