
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nittetsu Mining (TSE:1515) Restores Arqueros Access, But Is The Valuation Already Priced In?
Nittetsu Mining (TSE:1515) just updated investors on its Arqueros Copper Mine project after earlier production delays, confirming that road access has been restored and construction is continuing, while electricity arrangements and commissioning plans are still being worked through.
The latest Arqueros update lands after a sharp pullback, with a 30-day share price return of down 14.95% and a 7-day move of down 3.45%. Nittetsu Mining still shows a 32.86% year to date share price return and a 1-year total shareholder return of 74.16%, pointing to strong longer term momentum despite recent volatility.
Scan other copper and materials plays that show similar project momentum and risk profiles using the curated 17 top copper producer stocks alongside Nittetsu Mining today.
After that pullback, Nittetsu Mining trades at a level that sits awkwardly against its own intrinsic value estimate and the broader range of analyst-style models. Where does fair value actually land in that spread?
Price-to-Earnings of 14.7x: Is it justified?
Nittetsu Mining closed at ¥2,964 while trading on a P/E of 14.7x, which screens as expensive compared with both its closest peers and the broader JP Metals and Mining group.
The P/E ratio compares the share price with earnings per share, so a higher figure often signals that investors are willing to pay more for each unit of profit. For a diversified resources group like Nittetsu Mining, that kind of premium usually reflects confidence in earnings quality, project execution, or future cash generation.
Recent numbers show 91.5% earnings growth over the past year and a lift in net profit margins to 7% from 4.1%, which can help explain why the market is paying up. At the same time, the SWS DCF model points to a future cash flow value estimate of ¥959.86 per share, which sits well below the current ¥2,964 price and implies a rich valuation against that cash flow yardstick.
Compared with a peer average P/E of 14.2x and a JP Metals and Mining industry average of 11.5x, Nittetsu Mining trades on clearly higher multiples that price in stronger profitability and earnings resilience than the sector overall.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 14.7x (OVERVALUED).
Still, the Arqueros Copper Mine delays and the large gap between Nittetsu Mining’s share price and the SWS DCF estimate could both pressure sentiment if expectations reset.
Find out about the key risks to this Nittetsu Mining narrative.
Another View: What Nittetsu Mining’s Cash Flows Say
The P/E points to Nittetsu Mining looking expensive, yet the SWS DCF model is even harsher. At ¥2,964, the share price sits well above the estimated future cash flow value of ¥959.86, which signals an overvalued reading on this framework and raises a simple question: Which anchor do you trust more, earnings or cash flows?
For a closer look at how this cash flow view is built, and how sensitive it can be to changing assumptions over time, Look into how the SWS DCF model arrives at its fair value.
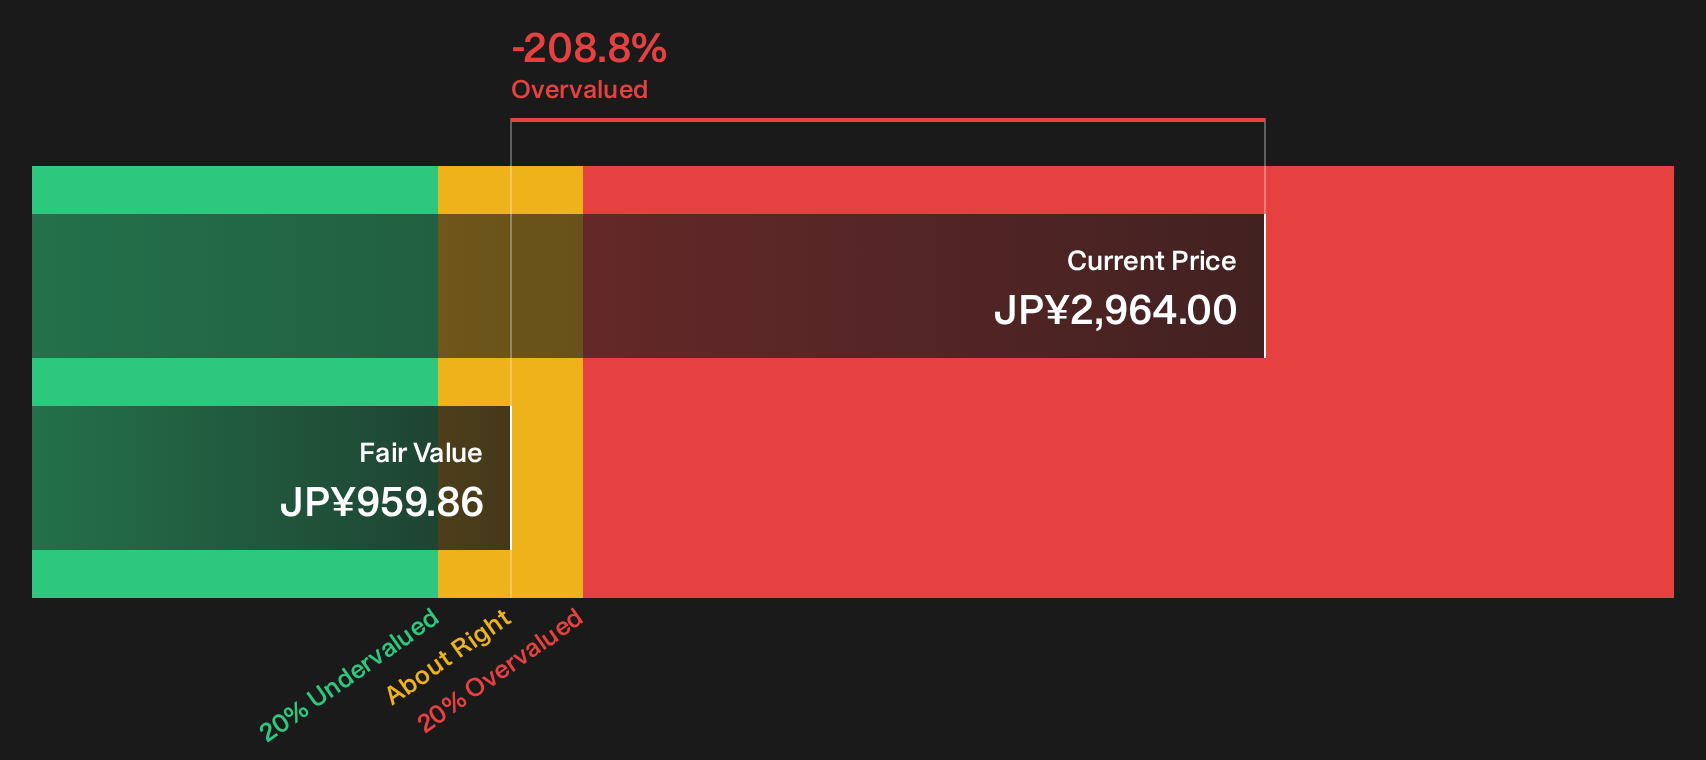
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nittetsu Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Nittetsu Mining is mixed, with sharp recent swings sitting alongside a longer run of strong returns. It makes sense to inspect the full risk and reward picture yourself while this valuation debate is fresh. To see how those trade offs line up in the numbers, start with the 1 key reward and 2 important warning signs.
Looking for more Nittetsu Mining style investment ideas?
If you only stop at Nittetsu Mining, you risk missing other opportunities that fit your approach, so cast the net wider with a few focused screens.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (22 results) that highlights businesses with financial structures built to handle pressure.
- Hunt for potential mispricings using the 73 high quality undiscovered gems that surfaces quality companies many investors are still overlooking.
- Prioritise stability first and use the 22 resilient stocks with low risk scores to quickly filter for businesses with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com