
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Japanese Founder Led Stocks With Earnings Growth Up To 37%
Japanese founder-led stocks sit in an interesting spot right now. The Bank of Japan says inflation is quite close to its 2% goal, and any move on rates lands directly on leaders with real skin in the game. That mix of firmer pricing power and committed insiders can appeal to investors who care about long term alignment. This article highlights three founder-led Japanese stocks from that group.
The three founder-led Japanese stocks below are just a starting sample, and the full screen surfaced 8 more businesses with equally compelling founder stories that are not covered here.
If you want to identify and analyze those additional high conviction ideas built around committed insiders and solid balance sheets, head straight to the Top Founder-Led Companies screener.
SHIFT (TSE:3697)
SHIFT is a founder-led software testing and quality assurance specialist in Japan, built around its CAT test management tool, quality platform and consulting services. The group generated about ¥65.4b from Testing and ¥65.1b from Development, with smaller contributions from Consulting and other segments, and carries a market value of roughly ¥270.4b.
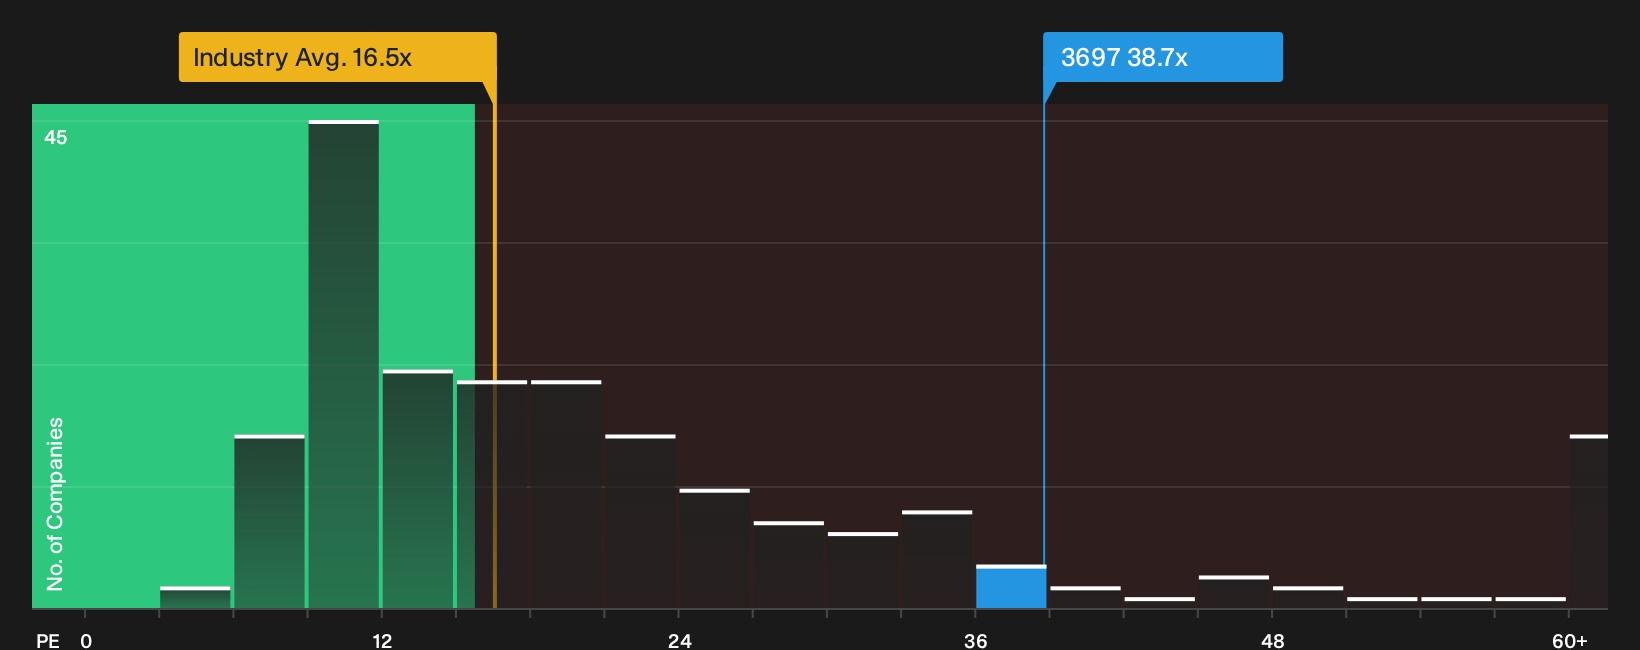
SHIFT aligns with a “back the founder” approach. A substantial insider presence steers the CAT platform, testing work and consulting arm, while smaller nursery and disability-support activities sit alongside the core operations. That combination of high insider commitment, strong governance credentials and a premium P/E will only be attractive if one pressure point on profitability moves in the right direction.
If that profitability pressure point matters to you, review the 2 key rewards and 2 important warning signs (1 is major!) and see where SHIFT’s premium P/E could either compress or finally look justified.
Rorze (TSE:6323)
Rorze builds founder-led automation gear for chip fabs, including wafer transfer tools, robots and EFEM units that move and protect wafers through production. The group is also active in flat panel display and life science equipment, and is valued at about ¥773.5b.
For investors backing legacies rather than hired managers, Rorze links long-serving insiders directly to its semiconductor automation franchise, with founder-aligned ownership intersecting a business that depends on long chip capex cycles. That combination can affect patient holders, depending on how one unseen swing factor in fab spending and order timing evolves.
That hinge on capex cycles is where you want sharper context, so pull up the 3 key rewards and 2 important warning signs (1 is major!) and see how Rorze’s order swings reshape the whole picture.

Sansan (TSE:4443)
Sansan runs founder-led SaaS platforms that centralize business contact and relationship data through its Sansan and Eight services, tightly linked to the screener’s focus on insider-aligned recurring revenue. The Sansan/Bill One segment generated ¥48,865 million, Eight added ¥7,143 million, and the group is valued around ¥251.5 billion.
Sansan aligns management incentives with long-run client relationships, since its contact-management and virtual card tools support sticky, subscription-style income that fits the founder-led theme. Investors assessing this setup may focus on how one pressure on profitability affects those recurring contracts.
That profitability pressure is the real swing factor, so pull up the 3 key rewards and 1 important warning sign to see where Sansan’s recurring revenue model could surprise the market.

Curious About What You Might Be Missing?
Fresh opportunities often move first. The ideas that look quiet today can pick up momentum fast and slip out of an ideal range before the crowd reacts. Consider acting early if they fit your strategy.
- Target resilient cash generators by scanning a curated list of solid balance sheet and fundamentals (22 results) and see which businesses currently combine financial strength with room for a potential rerating.
- Follow structural shifts in mining and electrification by reviewing a hand-picked 17 top copper producer stocks that could benefit if demand momentum keeps building.
- Prepare for possible sentiment swings by checking a focused 18 cryptocurrency and blockchain stocks that filters for listed plays tied to blockchain and digital asset adoption.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com