
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Undervalued Small Caps With Insider Action In Global Markets October 2026
In October 2026, global markets have been marked by a rotation away from large-cap growth stocks, driven by concerns over AI spending and inflationary pressures, with the small-cap Russell 2000 Index experiencing a notable decline of 3.05%. Amidst this backdrop of shifting investor sentiment and economic uncertainties, identifying small-cap stocks that demonstrate strong fundamentals and insider action can be key to navigating these volatile market conditions.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.3x | 0.2x | 47.33% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.9x | 0.9x | 39.62% | ★★★★★☆ |
| Centurion | 15.7x | 3.0x | 20.50% | ★★★★☆☆ |
| Transcontinental | 2.7x | 0.2x | -106.93% | ★★★★☆☆ |
| Diversified Royalty | 25.5x | 10.1x | 46.74% | ★★★★☆☆ |
| Franchise Brands | 26.9x | 2.0x | 47.99% | ★★★★☆☆ |
| Pizza Pizza Royalty | 11.7x | 9.0x | 39.36% | ★★★★☆☆ |
| Sagicor Financial | 6.7x | 0.5x | -81.52% | ★★★★☆☆ |
| Travis Perkins | NA | 0.3x | -229.38% | ★★★☆☆☆ |
| Linc | 12.1x | 12.5x | 34.59% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
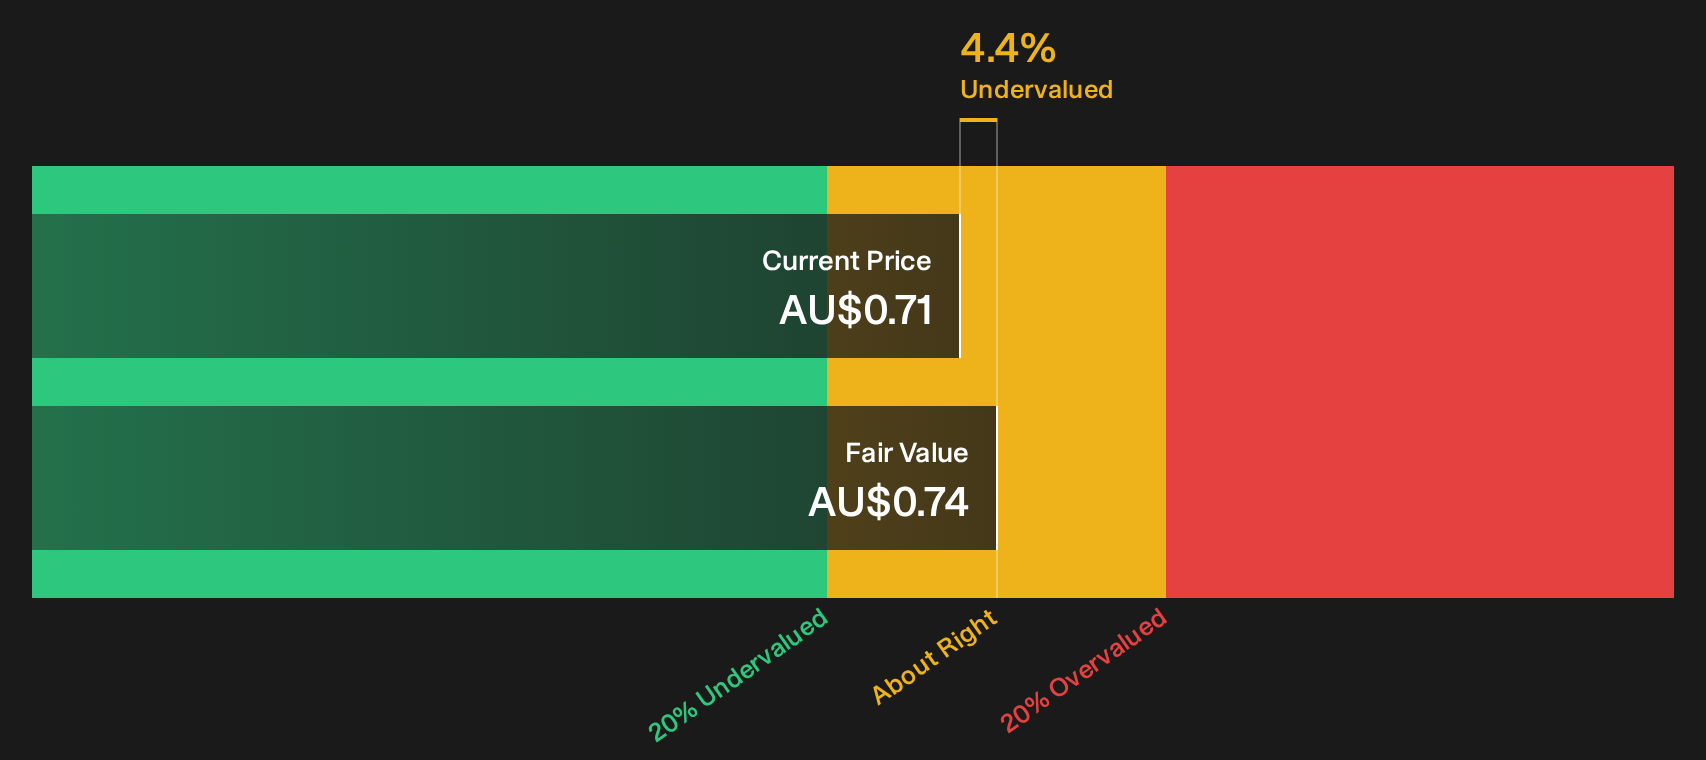
Black Cat Syndicate (ASX:BC8)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Black Cat Syndicate is a mining company focused on gold operations, with key projects including the Kal East and Paulsens Gold Operations, and has a market capitalization of A$0.14 billion.
Operations: The company generates revenue primarily from its Kal East and Paulsens Gold Operations, with recent quarterly revenues reaching A$374.29 million. Despite a gross profit margin of 38.42%, the net income margin has shown improvement, turning positive at 23.10% in the latest period after previous negative margins. Operating expenses and non-operating expenses are significant, impacting net income figures over time.
PE: 6.1x
Black Cat Syndicate's recent performance highlights its potential as an undervalued investment. The company reported a dramatic increase in gold production, reaching 90,833 oz for the year ending June 2026, up from 39,169 oz previously. Sales soared to A$374.29 million alongside a net income of A$86.46 million, marking a significant turnaround from the prior year's loss. Insider confidence is evident with Davide Bosio acquiring 100,000 shares in August 2026 for approximately A$75,000. Additionally, Chris Stone joined as an independent director in September 2026 to enhance strategic planning and operational leadership within the mining sector. Although Black Cat relies on higher-risk external borrowing for funding and faces industry challenges typical of smaller companies, their forecasted earnings growth of nearly 35% annually positions them well for future expansion amidst evolving market dynamics.
Journey Energy (TSX:JOY)
Simply Wall St Value Rating: ★★★★★☆
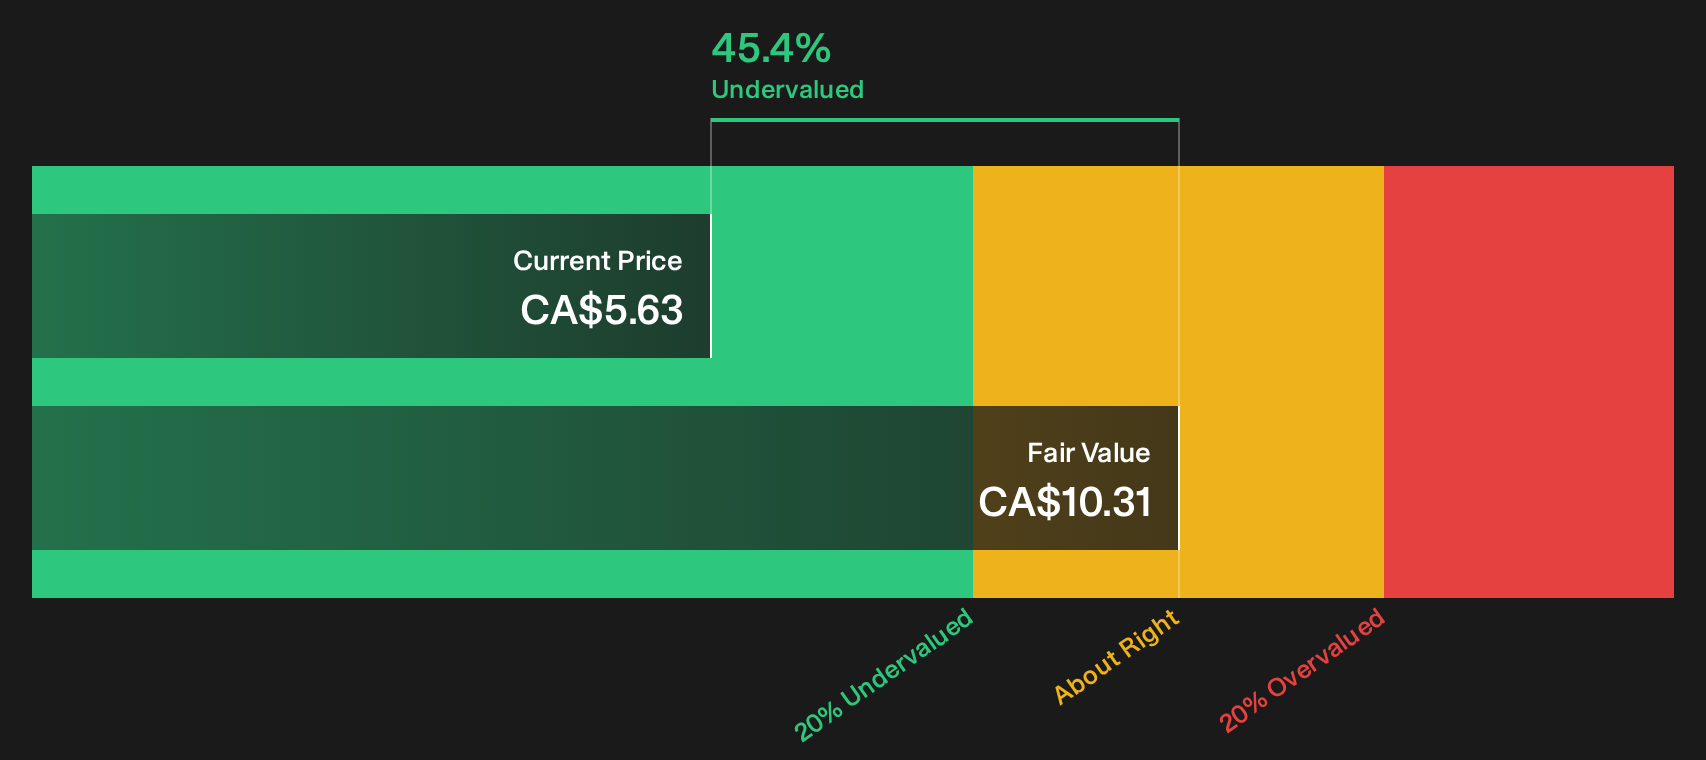
Overview: Journey Energy is a Canadian oil and gas exploration and production company with a market capitalization of approximately CA$0.27 billion, focusing on the development and operation of energy resources in Western Canada.
Operations: Journey Energy's revenue primarily comes from its operations, with recent figures showing CA$180.25 million for the quarter ending June 30, 2026. The cost of goods sold (COGS) was CA$87.39 million, leading to a gross profit margin of 51.52%. Operating expenses include general and administrative costs, which were CA$13.92 million in the same period. Net income for this quarter was CA$26.79 million, resulting in a net income margin of 14.86%.
PE: 14.2x
Journey Energy, a smaller energy player, has shown notable financial growth with Q2 2026 revenue hitting C$55.38 million, up from C$42.63 million the previous year. Net income surged to C$18.51 million from C$4.07 million, indicating strong operational performance despite reliance on riskier external funding sources. Recently added to the S&P Global BMI Index and presenting at major industry conferences, Journey's increased visibility could bolster future prospects in the energy sector. However, no insider buying or share repurchases were noted recently.
- Navigate through the intricacies of Journey Energy with our comprehensive valuation report here.
Gain insights into Journey Energy's historical performance by reviewing our past performance report.
Transcontinental (TSX:TCL.A)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Transcontinental is a Canadian company primarily engaged in retail services and printing operations, with a market capitalization of approximately CA$1.5 billion.
Operations: The company generates revenue primarily from Retail Services and Printing, with a recent gross profit margin of 17.13%. Operating expenses, including depreciation and amortization, significantly impact profitability. Non-operating expenses have varied over time but remain a notable cost factor.
PE: 2.7x
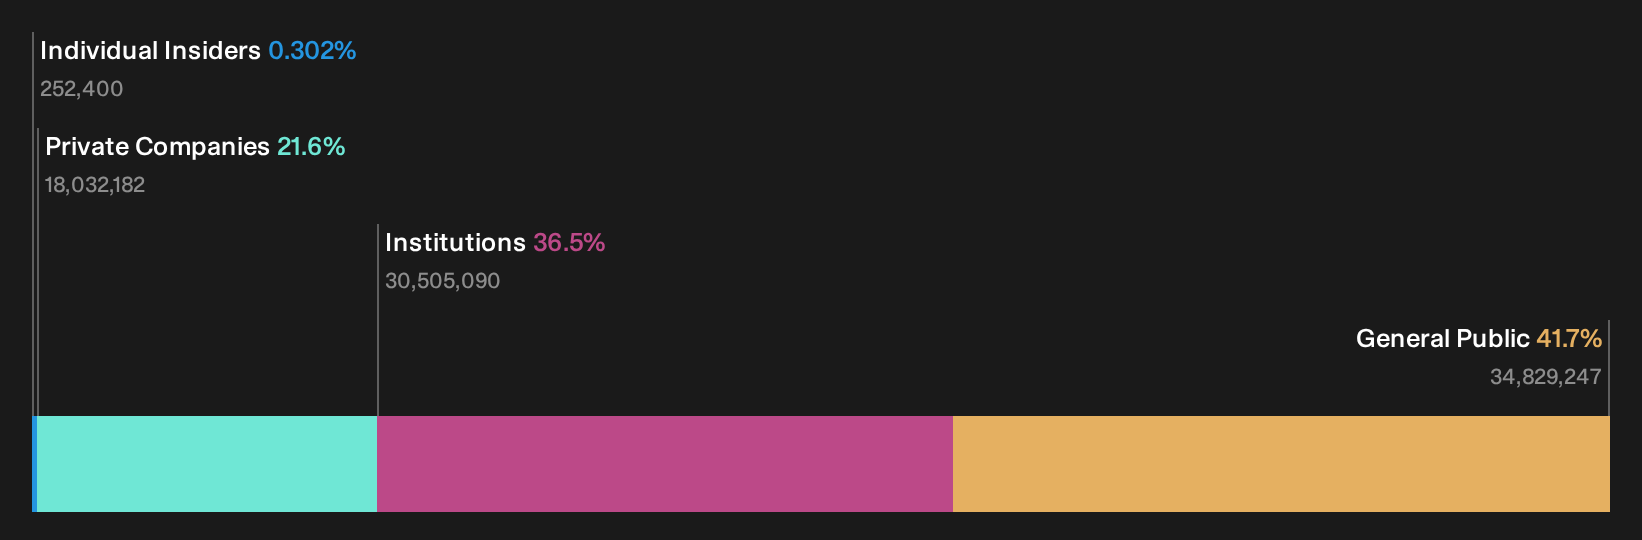
Transcontinental, navigating the small-cap landscape, faces challenges with its high debt levels and reliance on external borrowing. Despite this, their recent earnings report shows a slight sales increase to C$306 million for Q3 2026. However, net income dipped slightly to C$36.5 million from last year. Insiders have shown confidence by purchasing shares recently, signaling potential internal optimism. The closure of their Owen Sound facility is part of strategic downsizing efforts aimed at optimizing operations amidst forecasted earnings declines over the next three years.
Make It Happen
- Delve into our full catalog of 120 Undervalued Global Small Caps With Insider Buying here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com