
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hut 8 (HUT) Could Be 56% Undervalued As River Bend AI Deal Reshapes The Story
Hut 8 (HUT) is drawing fresh attention after announcing its River Bend AI data center project in Louisiana, anchored by a 15 year, US$7b lease agreement with Fluidstack and involving Anthropic as a partner.
Recent trading tells a different side of the Hut 8 story. The share price has retreated sharply in the short term, with the 30 day share price return down 31.39% and the 90 day return down 37.83%. However, the year to date share price return is still up 32.14% and the 1 year total shareholder return of 35.72% points to longer term momentum that many investors are weighing against the new River Bend AI announcement.
Scan beyond Hut 8 and this single AI build out by reviewing 55 AI infrastructure stocks that could also benefit from rising demand for high power, high compute data centers.
Hut 8 now trades sharply below the average analyst price target, yet the market is marking the stock down after the River Bend AI reveal. Is that discount signaling an opportunity, or does it reflect justified caution around execution and profitability?
Most Popular Narrative: 56% Undervalued
Hut 8 last closed at $67.75, while the most followed narrative pegs fair value at $154.04. This frames the current drop as a valuation gap rather than just a bad reaction to one project update.
The Power First development system, supported by an 8.7 gigawatt pipeline and the ability to originate multiple sites under diligence or exclusivity, is now backed by approximately US$7.5b of fully amortizing investment grade project notes and an undrawn US$1.07b revolver. Together, these can support incremental campus build outs that aim to grow contracted revenue and future earnings.
See why 83 investors see Hut 8 as 56% undervalued.
Result: Fair Value of $154.04 (UNDERVALUED)
Still, the Hut 8 narrative can break if large power campuses face prolonged regulatory delays, or if Bitcoin related losses continue to weigh on already negative earnings.
Find out about the key risks to this Hut 8 narrative.
Another View: Hut 8 Looks Expensive On Sales
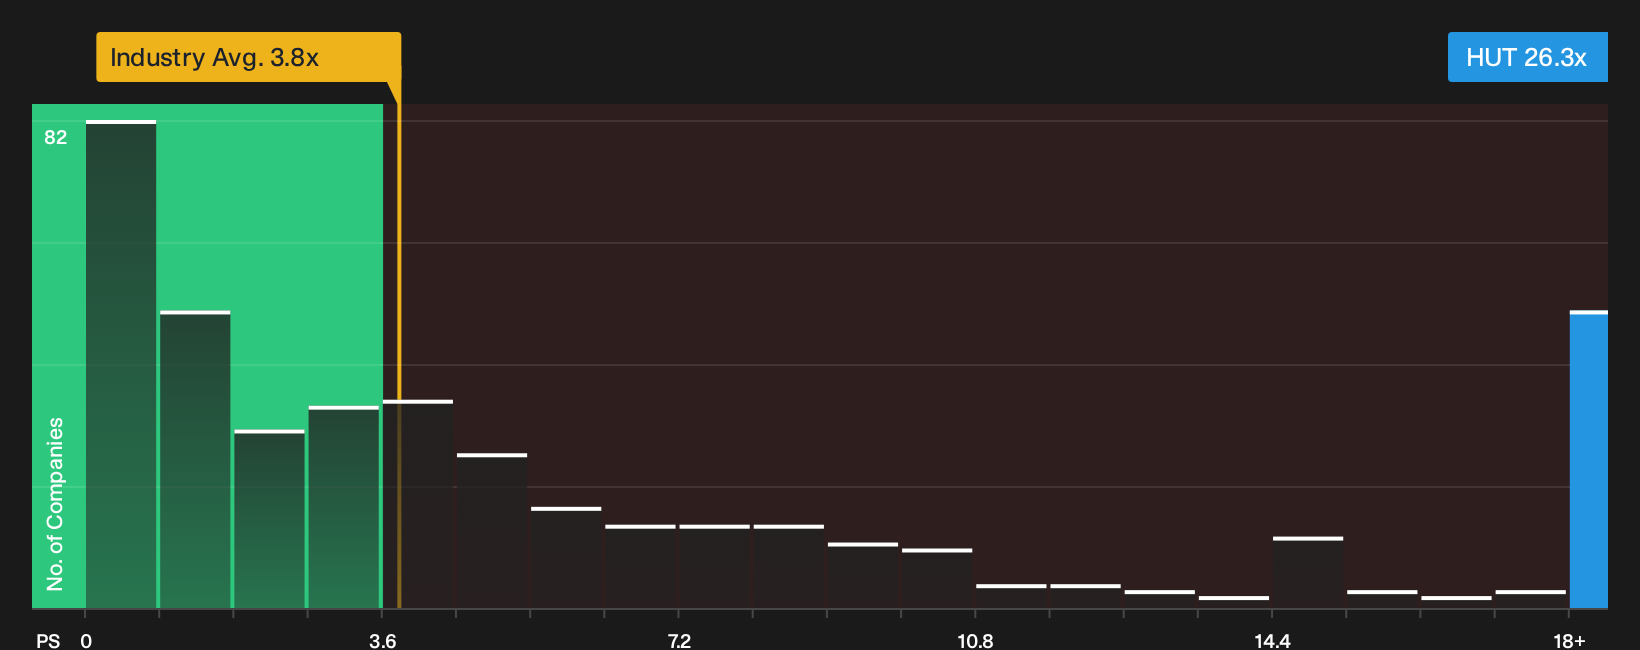
On the flip side of that US$154.04 fair value narrative, Hut 8 trades on a P/S of 26.3x. That is far above the US Software sector at 3.8x and well above the fair ratio of 12.6x. For investors, that gap points to real valuation risk if sentiment cools.
Anyone weighing those numbers against the AI lease story may want to see how Hut 8 stacks up on sales-based metrics beside peers and where that fair ratio suggests the market could drift over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mix of enthusiasm and concern around Hut 8 match your own read of the situation, or does it feel off base given the numbers in front of you? Take a close look at the details, weigh the AI build out against the current multiples, then pressure test your thinking against the 1 key reward and 3 important warning signs.
Looking for more Hut 8 style investment ideas?
If Hut 8 has sharpened your focus on valuation and risk, broaden your watchlist by scanning other opportunities that match your own return and downside comfort zone.
- Target potential bargains by reviewing companies our screener flags as attractively priced on quality fundamentals through the 33 high quality undervalued stocks.
- Strengthen capital preservation by filtering for businesses with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Spot overlooked opportunities by tracking financially sound smaller companies listed in the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com