
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed Dollar General's Run? What Holders Had To Believe
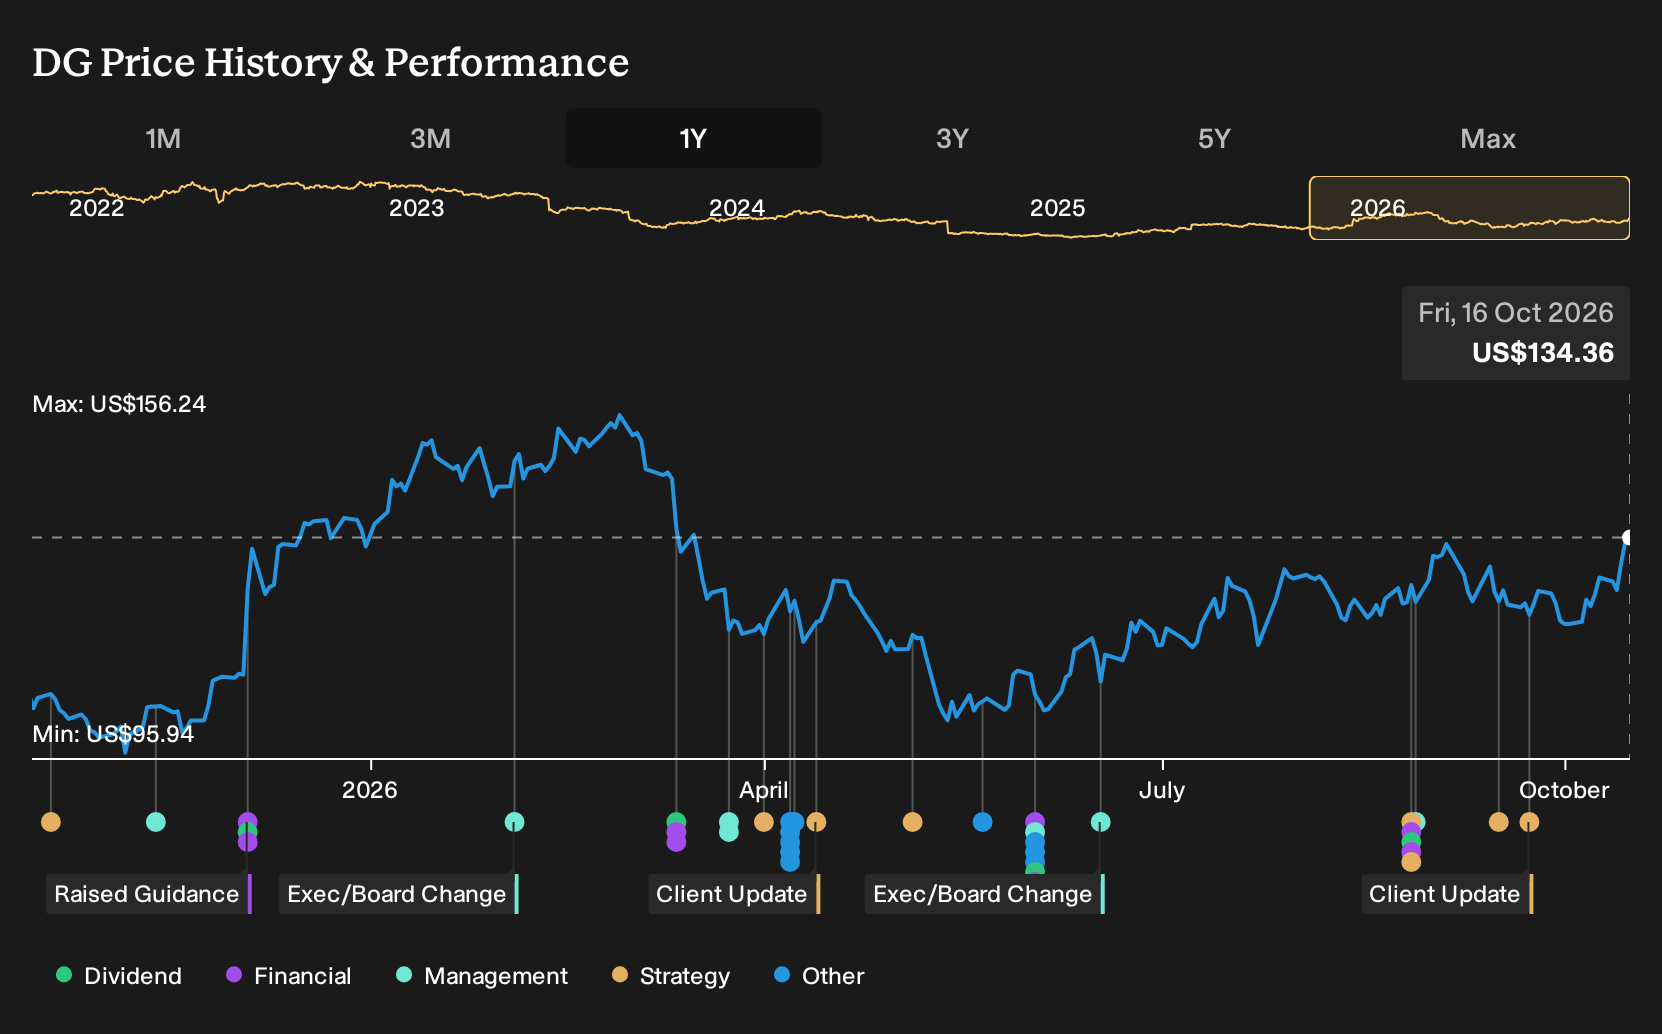
If you only glanced at headlines about store closures, tariff pressures and customer belt tightening, Dollar General may have looked like a grind at best. Investors who held Dollar General over the past year are up 28.7%, including dividends. If you had put money to work on 16 October 2025, that outcome would probably feel surprising. So what, exactly, in the mix of bullish expansion plans and bearish cost worries, was really knowable at the start?
If the move has made Dollar General harder to judge, start where the gap is still open and scan 33 high quality undervalued stocks.
The Two Dollar General Stories Investors Had In Front Of Them
The shares cost US$104 at the start of the period, so any view on Dollar General really hinged on which story about its future seemed more likely.
On the upbeat side, one narrative argued that a Fair Value of US$120 was reasonable. This figure was effectively the price implied if its assumptions played out and leaned on revenue growth assumptions of 4.1% a year and profit margins improving to 3.6% as store expansion, private labels and digital delivery took hold.
The more cautious script pointed to a Fair Value of US$80, which was the price level its own expectations supported. That camp focused on store closures, tariffs and rising labor costs as key risks, with assumptions that margins only reached 3.2% and that urban traffic pressures could linger.
What The Results Changed For The Dollar General Debate
The clearest new fact was Dollar General’s Q2 2027 step up in profitability. Revenue moved from US$10,727.7m in Q2 2026 to US$11,290.4m and net income rose from US$411.4m to US$550.3m, with net margin widening from 3.8% to 4.9%. That improvement lined up more closely with the upbeat case that assumed healthier economics from expansion and efficiency work, even though tariff and cost risks remained in the background.
The takeaway for you is simple. When a thesis hinges on margin repair, watch net income and net margin together rather than only sales. Then check whether each new report walks those ratios toward or away from the story you are being asked to believe.
What Dollar General’s Recent Run Already Prices In
Dollar General trades at US$134 today, after a 28.7% gain over the past year. The selected Narrative’s Fair Value sits below the current price, because it treats today’s level as already baking in steady traffic, remodel benefits and efficiency gains across most of the store base.
The question now is what has to keep going right for that price to hold up, and the Narrative points to one core assumption a buyer must test: that remodel, shrink reduction, digital and media initiatives can all sustain a 6% to 7% operating margin without running out of easy wins.
"The numbers imply that Dollar General’s share price already prices in sustained same store sales growth, continued margin expansion, and successful execution of remodel, digital, and media initiatives that may leave limited room for disappointment."
The price and this Narrative do not agree. → Uncover what this Narrative says Dollar General is actually worth
Looking Beyond Dollar General
Dollar General lives on tight budgets and everyday baskets. Your next question is where that same hunt for value appears elsewhere.
One large grocery player is pushing heavily into online ordering and marketplace sales. It is using in house digital platforms to keep shoppers inside its ecosystem.
Fresh food, health focused ranges and own brands are doing a different job. They pull customers in with convenience, perceived quality and stable pricing.
Those moves demand steady spending on logistics, automation and store upgrades. The traditional grocer’s role could quietly shift as these experiments scale.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com