
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Iluka Resources Stock Is Drawing Fresh Rare Earth Valuation Attention
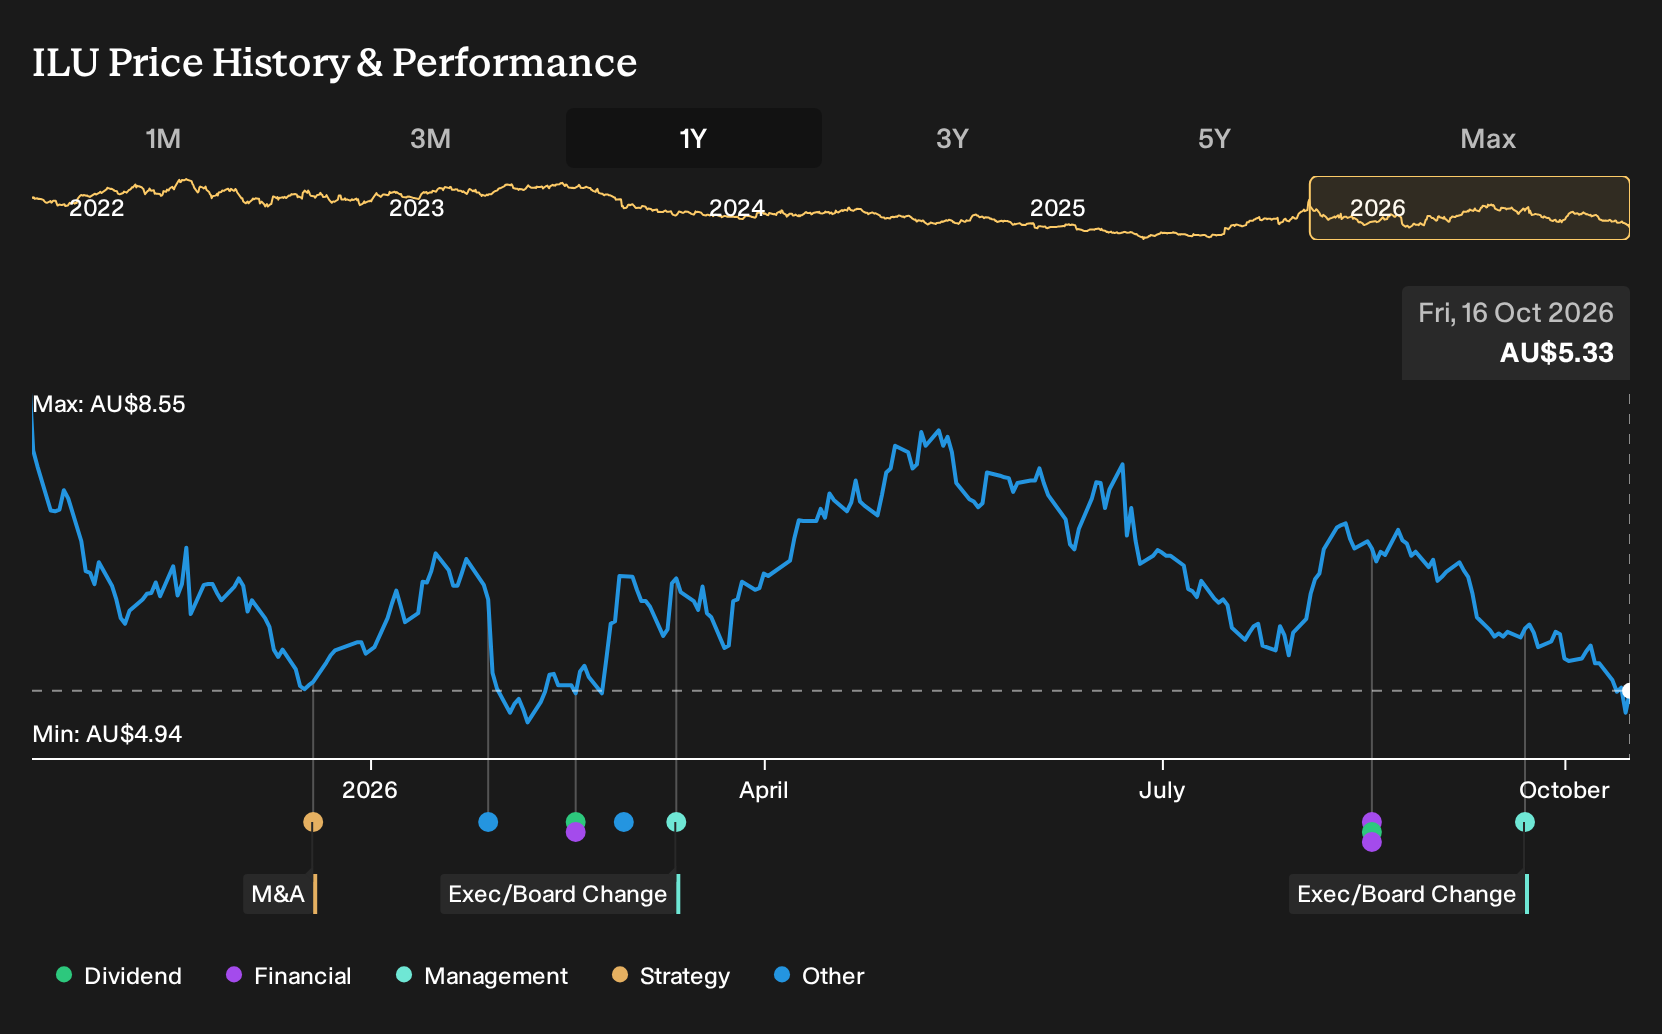
- Iluka Resources is back in focus as renewed interest in non Chinese rare earths and critical minerals puts its existing project pipeline and sales base under the microscope.
- The discussion around Iluka Resources’ price to sales ratio highlights how investors are weighing current revenue against potential rare earth contributions from initiatives such as South Africa’s supply push.
- We will now look at how Iluka Resources’ rare earth positioning and valuation debate could reshape the broader investment narrative.
Scan beyond Iluka Resources and compare its valuation story with other critical mineral producers using the hand picked 32 best rare earth metal stocks often watched by investors tracking non Chinese supply themes.
Iluka Resources Investment Narrative Recap
To own Iluka Resources, you need to believe its mineral sands base and rare earths pipeline can justify funding needs and current valuation despite recent share price weakness. The short term story hinges on execution at projects like Eneabba and Balranald, as well as keeping work in progress and cash costs under control. South Africa’s rare earth push supports the non Chinese supply theme but does not materially change near term operating pressures.
The biggest risk right now is that rising Australian costs and ongoing rare earth refinery spending strain cash flow while Iluka Resources remains loss making. Building inventory without matching demand could weigh on earnings if pricing or volumes soften. Debt already looks stretched against operating cash flow, so any stumble in project timing or commodity demand would likely sharpen questions around balance sheet resilience.
Recent commentary around Iluka Resources has focused on its price to sales ratio and the idea that the stock screens as undervalued on sales despite an elevated P/S versus some peers. That ties directly into the core catalyst. Investors are watching whether rare earth initiatives and mineral sands projects translate forecast revenue growth into actual cash generation that can support the refinery build and reduce reliance on higher risk borrowing.
With analysts expecting strong revenue and earnings growth over coming years, the operational test is straightforward. Iluka Resources needs to bring Eneabba and Balranald online cleanly, adhere to its A$20 million 2025 cost saving plan, and avoid letting work in progress inventory erode margins. If those pieces line up while non Chinese rare earth supply gains traction, the current valuation debate around its sales base becomes central to how the stock is viewed.
Iluka Resources' current analyst narrative points to A$2.1b in revenue and A$171.6 million in earnings by 2029, based on forecast yearly revenue growth of 26.8%. This implies a move from a loss of A$288.4 million in earnings today to A$171.6 million in 2029, a change of roughly A$460 million in aggregate earnings power if those projections play out.
Uncover why Iluka Resources' fair value indicates a 49% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You might see South Africa’s rare earth supply push as a clear positive for Iluka Resources, yet the lowest analyst views lean on regulatory risk instead. Those forecasts were built on revenue reaching about A$2.2b and earnings of roughly A$465.6 million by 2029 before this news, so opinions may shift and it is important to compare several viewpoints yourself.
Explore 7 other Iluka Resources fair value estimates, including one that suggests it could be worth just A$6.50!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Iluka Resources research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Iluka Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iluka Resources' overall financial health at a glance.
Looking for more investment ideas beyond Iluka Resources?
If the Iluka Resources story has sparked new questions for you, it can help to line it up against other opportunities that share similar traits in quality, balance sheet strength, or income potential. The Simply Wall St Screener is built for exactly that kind of comparison, letting you filter the market around the factors that matter most to your process.
- If you want to focus on quality that still looks overlooked, check out 15 high quality undiscovered gems and see which businesses currently fly under the radar despite solid fundamentals.
- If capital preservation sits high on your list, start with 6 resilient stocks with low risk scores and narrow in on companies that score well on resilience and financial risk metrics.
- If income is a priority, scan through 4 dividend fortresses and compare which stocks combine higher yields with balance sheets that can reasonably support ongoing payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com