
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Arabian Drilling Climbed While It Swung To A Loss
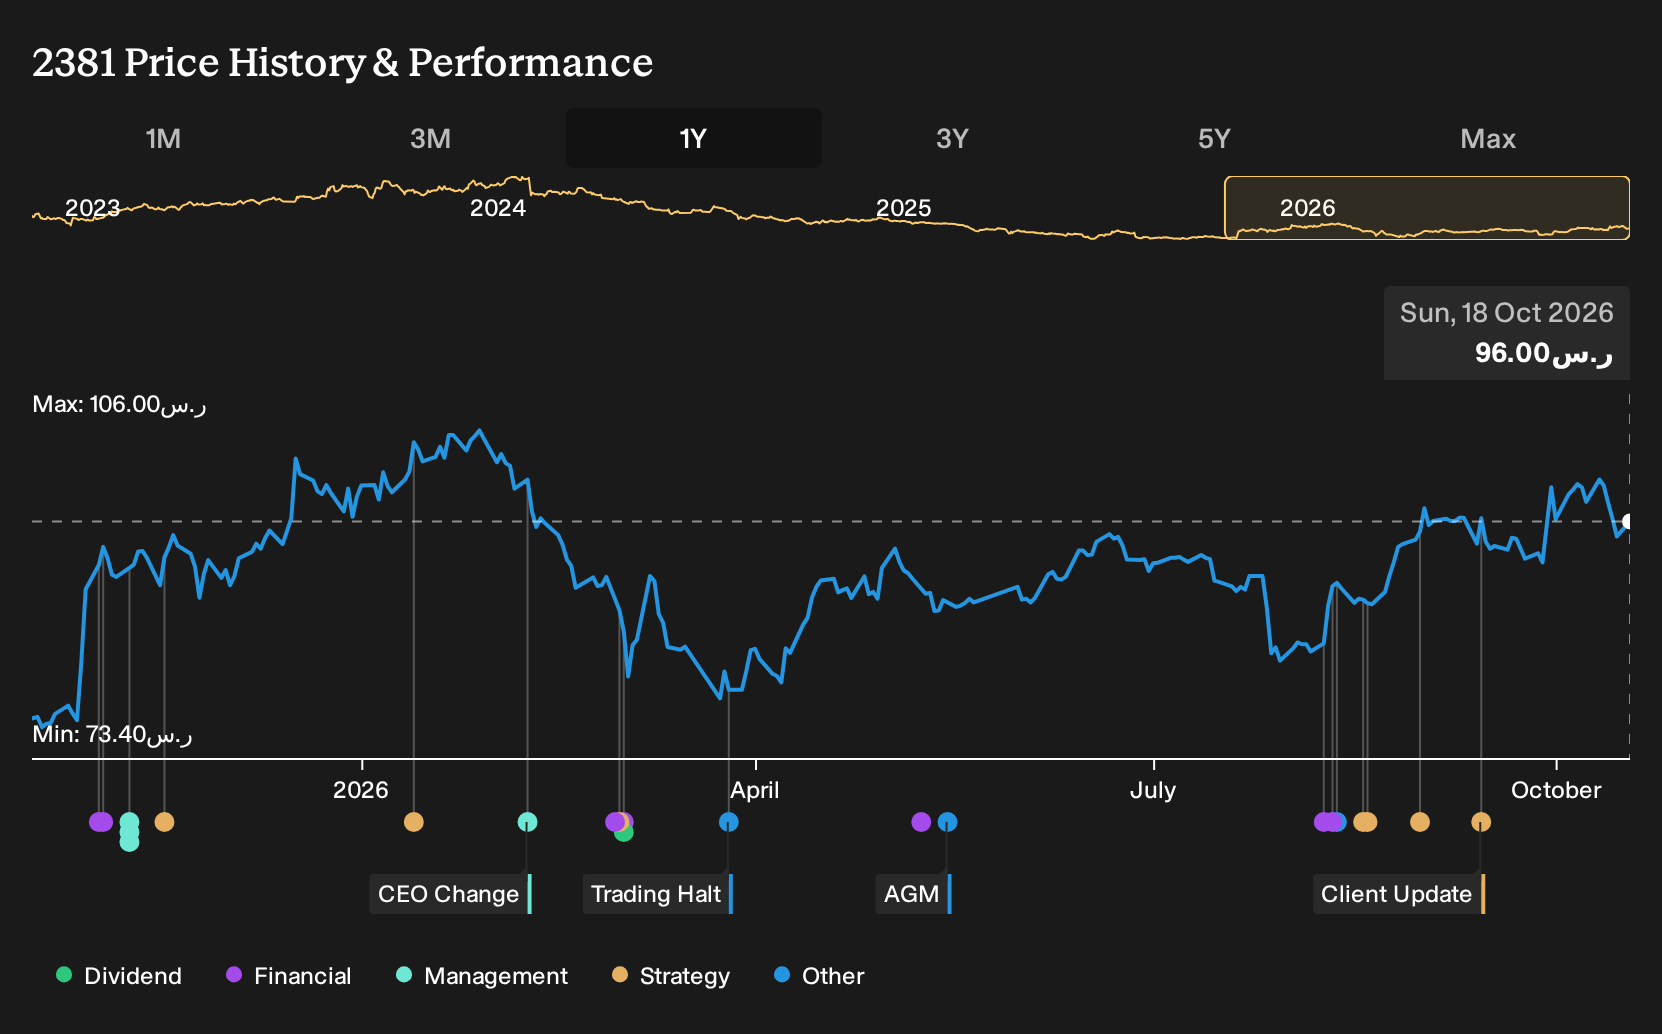
Investors who held Arabian Drilling over the past year are up 28.9%, including dividends. That result came in a year when revenue and profit both fell in the latest reported quarter and net margin slipped into a loss, which is not the backdrop most people instinctively cheer. If you were weighing a purchase back on 18 October 2025, how would you have balanced expanding MENA ambitions against rig suspensions and a dividend halt?
The easy part of this move is behind Arabian Drilling. Zero in on 195 high quality undervalued stocks for companies trading below our estimates.
The Two Futures Investors Had To Price In For Arabian Drilling
The shares cost SAR74.45 at the start of the period, and anyone looking at Arabian Drilling then had to pick between two very different stories about where the rigs and cash flows might go next.
The bullish narrative pointed to a fair value of SAR89.23, a rough guide to what the stock might be worth if its assumptions played out. This view was built on 5.5% revenue growth, an 11.8% profit margin and a future P/E of 29.2x over three years, with international expansion and MENA diversification expected to reduce reliance on Saudi Aramco.
The bearish narrative anchored on a fair value of SAR63, again an implied price based on its own model. It assumed only 1.6% revenue growth, a 10.9% profit margin and a future P/E of 24.7x, and emphasized the risk that a faster shift to renewables, tighter environmental rules and dependence on a few big customers could pressure utilization and long-term rig economics.
What The Results Changed For The Arabian Drilling Thesis
The clearest new datapoint for Arabian Drilling was Q2 2026. Revenue of SAR764.69m compared with SAR862.47m a year earlier, and net income moved from a SAR7.48m profit to a SAR31.51m loss. Net margin fell from 0.9% to a loss of 4.1%. That record challenged both the bullish profitability assumptions and, in the short term, supported the cautious case.
The lesson is simple. When a story rests on margin recovery, you look first at the net margin line and then at the absolute profit to see whether the narrative is turning into cash or remaining only words.
What Arabian Drilling’s Price Assumes Today
Arabian Drilling now trades at SAR96 after a 28.9% gain over the past year. The selected Narrative’s Fair Value sits below that level, framing today’s quote as a test of how much of the backlog story investors are willing to pay for.
The Narrative leans on a strong order book, contract renewals and regional work, while still flagging client concentration, compliance costs and capital intensity. Anyone paying SAR96 is effectively assuming that backlog converts to steadier earnings, so the key question is how those customer and cost risks affect that view.
"Shift to renewables and tightening environmental rules threaten core revenues, while heavy dependence on a few key clients heightens earnings and cash flow volatility. Intensifying competition and escalating compliance costs erode margins, restrict cash generation, and elevate financial risk amid uncertainty over contract renewals and geographic expansion."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 48% below our estimate - benefits from long term public works contracts and modular construction methods gaining adoption.
- Company 2 - 34% below our estimate - grows fee income as investors seek access to renewable projects and digital infrastructure funds.
- Company 3 - 29% below our estimate - broadens from pediatric probiotics into adult health lines sold through major retail chains.
Those are three of them. See the full list of 203 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com