
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can AI Transformation Call Change The Bull Case For BBVA Stock?
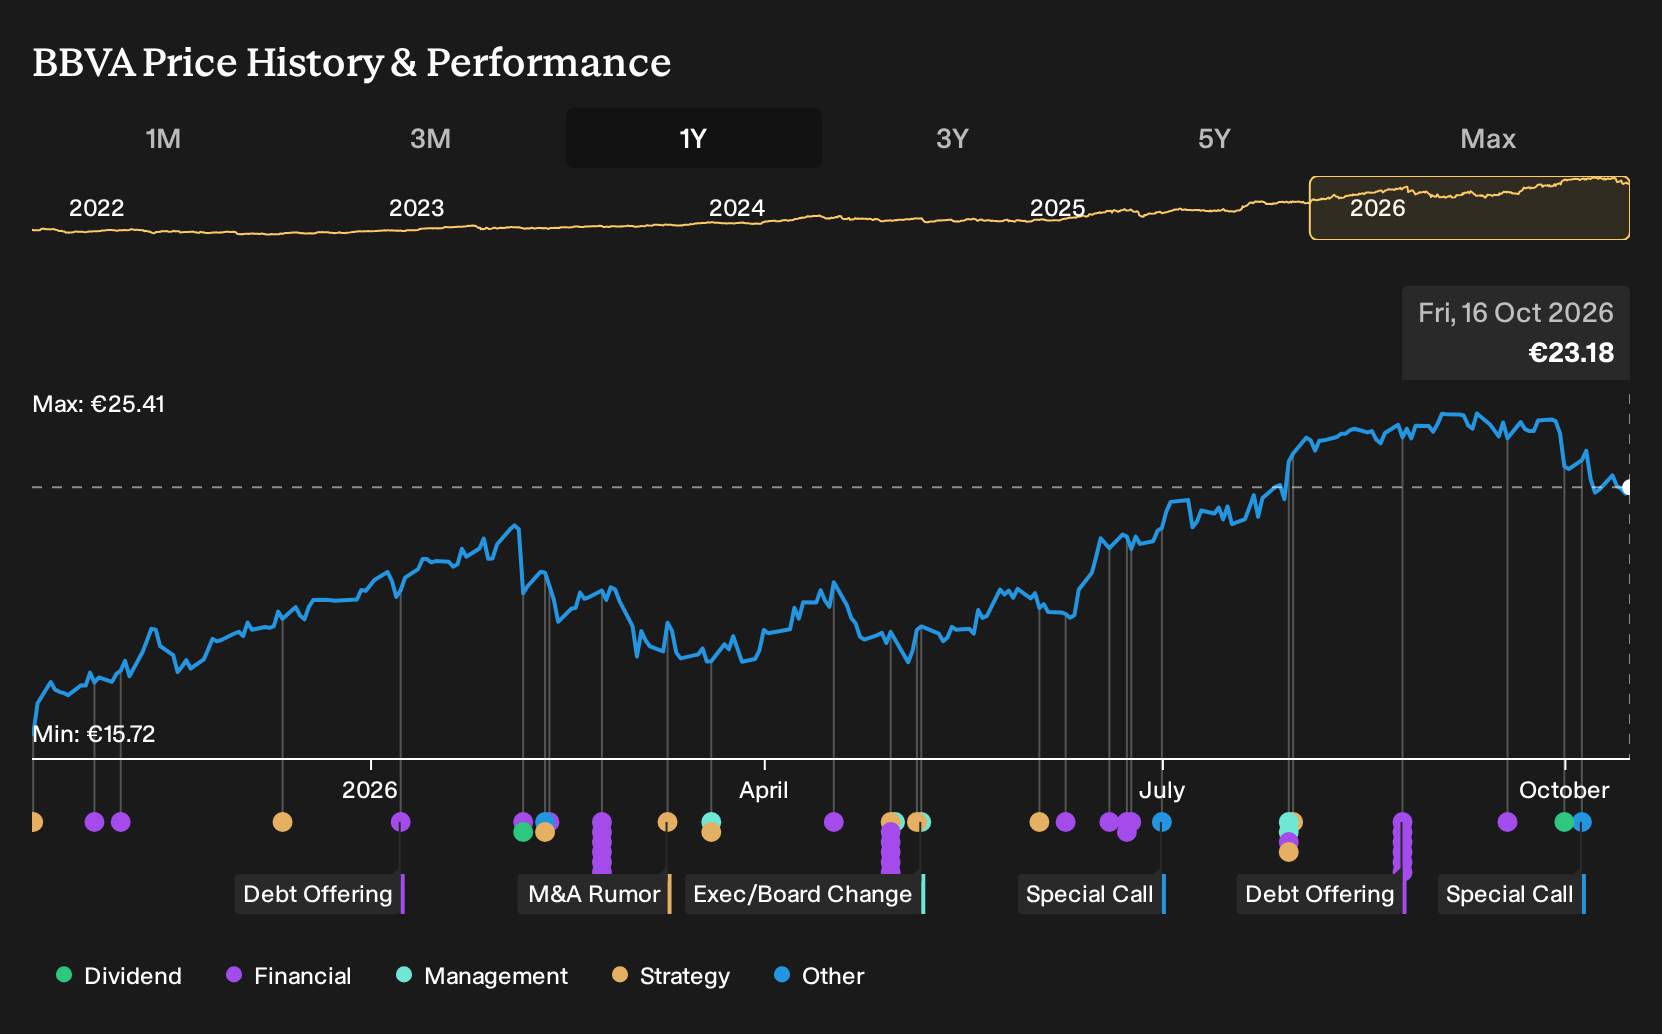
- BBVA held a special call on 5 October 2026 to outline its AI Transformation and IT Strategy, with a particular focus on BBVA Spain.
- The discussion highlighted how BBVA is reshaping core banking operations around AI and technology, which directly affects cost efficiency, product delivery and execution risk.
- We will examine how Banco Bilbao Vizcaya Argentaria's investment narrative is influenced by its AI Transformation call and Spain focused IT strategy.
Use BBVA's AI push as a starting point and size up other financials leaning into automation with our hand-picked 55 AI infrastructure stocks shaping tomorrow's banking rails.
Banco Bilbao Vizcaya Argentaria Investment Narrative Recap
To own Banco Bilbao Vizcaya Argentaria, you need to believe the mix of digital banking, AI and exposure to Mexico and Turkey can keep supporting earnings, even with normal swings in returns. The AI Transformation call mainly sharpens that story rather than changing it. In the near term, the key swing factor remains how efficiently BBVA converts heavy tech and cloud spending into a better cost/income profile.
The biggest immediate risk still sits in the macro and legal bucket. Exposure to Turkey and Mexico leaves group profit sensitive to currency moves and local shocks, while the Villarejo case could add costs or fines. AI investments may improve productivity, but they also increase competitive pressure on pricing if rival offers become easier to compare.
The AI Transformation and IT Strategy discussion effectively updates investors on BBVA’s digital agenda, including its NextGen cloud platform and growing use of AI in contact centers, risk workflows and software development. That matters for the same reasons as before. Management wants more activity running on these systems to lower unit costs and support margins.
For you as a shareholder, the relevance lies in execution. If BBVA can lift the share of online transactions processed on NextGen toward its 2029 target and keep improving Spain’s digital sales mix, the bank gains more flexibility on pricing and capital deployment. If implementation stumbles or competition erodes pricing power faster than efficiency gains arrive, the AI narrative becomes more of a cost line than a clear catalyst.
What The BBVA Earnings Path Implies
Banco Bilbao Vizcaya Argentaria's narrative states a projection of €49.4 billion in revenue and €15.4 billion in earnings by 2029, based on the provided assumptions. This corresponds to 13.1% yearly revenue growth and an earnings increase of €4.7 billion from €10.7 billion today.
Uncover why Banco Bilbao Vizcaya Argentaria's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on BBVA puts fintech competition front and center. The most cautious analysts worry new digital rivals could squeeze fees so hard that even €48.6b of revenue and €14.3b of earnings by 2029 feel ambitious. That is a much harsher lens than consensus and could shift again once this AI call fully filters into forecasts.
Explore 4 other Banco Bilbao Vizcaya Argentaria fair value estimates, including one that suggests as much as 25% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco Bilbao Vizcaya Argentaria research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Banco Bilbao Vizcaya Argentaria. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco Bilbao Vizcaya Argentaria's overall financial health at a glance.
Looking For More Ideas Beyond Banco Bilbao Vizcaya Argentaria?
If BBVA's AI push has you rethinking what efficiency and risk control can look like, it can be useful to scan for other businesses with clear balance sheets, income streams or pricing power. The Simply Wall St screener lets you filter for the traits you care about most, then compare those results side by side with Banco Bilbao Vizcaya Argentaria.
- For investors who care most about stability and downside protection, start with a curated pool of 231 resilient stocks with low risk scores that score well on resilience and risk metrics.
- If your priority is finding companies with strong finances and clean leverage, use the list of solid balance sheet and fundamentals (203 results) to focus on businesses that have balance sheets that can better absorb shocks.
- Those hunting for under-the-radar opportunities can scan a 613 high quality undiscovered gems list that filters for quality fundamentals where attention from the broader market may still be limited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com