
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rivian Automotive (RIVN) As Mind Robotics News And Record Deliveries Test Its Valuation
Rivian Automotive (RIVN) has landed back on investor dashboards after two linked developments. Mind Robotics, where Rivian owns roughly a third, appointed veteran operator Doug Field as president, and Rivian reported record third quarter vehicle deliveries.
The recent headlines arrive against a weaker tape. Rivian Automotive’s share price has fallen 27.96% over the past 90 days and is down 36.01% year to date, while the 1-year total shareholder return has declined a milder 4.68%. Short-term momentum has cooled, even as longer-term holders have seen a smaller pullback.
Scan how Rivian Automotive compares with other high-conviction EV and AI plays by reviewing the hand picked 38 AI small caps that are catching attention right now.
Rivian Automotive now combines record deliveries, a large stake in Mind Robotics and a share price that has pulled back hard. Is this a strong platform that is temporarily marked down, or still too expensive for what investors get today?
Most Popular Narrative: 35% Undervalued
Rivian Automotive last closed at $12.42 while the most followed valuation story anchors fair value closer to $19.23, so the gap investors are debating is sizeable. That spread rests on a view that high growth, higher margin software and services, and new vehicle platforms can eventually justify a richer future earnings profile.
Vertical integration in technology, especially in autonomy, battery, and software, combined with growing software and services revenue, including licensing via partnerships like with Volkswagen, is expected to open new high-margin revenue streams and diversify earnings, potentially strengthening EBITDA and net margins over time. Rivian's strategic focus on the premium adventure and outdoor segment trucks and SUVs and growing commercial segment, notably Amazon van contracts, targets higher-margin submarkets and provides more stable, multi-year revenue flows, which could smooth earnings fluctuations and support higher average revenue per vehicle.
See why 257 investors see Rivian Automotive as 35% undervalued.
Result: Fair Value of $19.23 (UNDERVALUED)
Still, the bullish Rivian Automotive story can crack if high cash burn forces fresh equity raises, or if competition and pricing pressure squeeze margins more than expected.
Find out about the key risks to this Rivian Automotive narrative.
Another View On Rivian Automotive’s Valuation
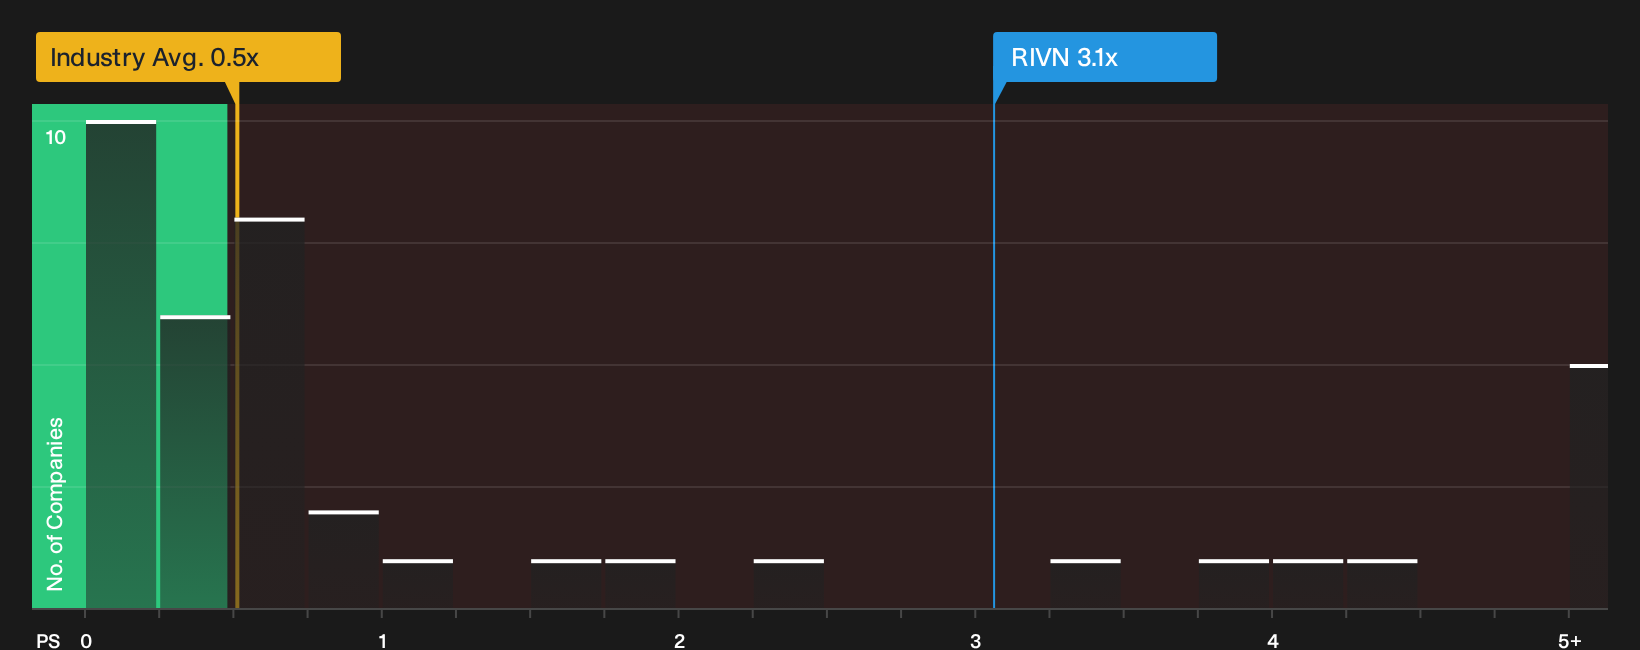
On the flip side of that $19.23 fair value story, Rivian Automotive screens as expensive on a simple sales multiple. The stock trades on a P/S ratio of 3.1x, while the US Auto industry averages 0.5x and the fair ratio sits nearer 1.8x, which points to a rich tag that could compress if sentiment cools.
Those gaps raise a practical question for anyone watching RIVN. Is the premium simply the cost of owning a fast growing EV player, or is it a valuation risk that only makes sense if the bullish narrative fully plays out?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Rivian Automotive’s price and fair value are clear. Move quickly, review the underlying numbers yourself, and weigh both the 3 key rewards and 2 important warning signs.
Looking for more Rivian Automotive sized ideas?
If you only focus on Rivian Automotive, you might miss other opportunities quietly lining up right now, so put a small portion of time into broadening your watchlist.
- Target value first and let price follow by scanning companies flagged as 33 high quality undervalued stocks with stronger fundamentals than their current market tag suggests.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can better handle shocks and funding needs without constantly leaning on fresh capital.
- Hunt for under-the-radar potential by checking a 20 high quality undiscovered gems that larger investors may not be watching closely yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com