
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DICK'S Sporting Goods (DKS) Faces A Class Action Deadline, Is The Stock Fully Valued?
Rosen Law Firm has issued an investor alert for DICK'S Sporting Goods (DKS) shareholders, reminding buyers of common stock between September 8, 2025 and August 24, 2026 about a November 3, 2026 lead plaintiff deadline.
DICK'S Sporting Goods now trades at US$144.35, with the share price up 2.49% over 1 day and 19.15% over 30 days, yet still down 30.74% over 90 days and 27.90% year to date. The 3 year total shareholder return of 46.45% contrasts sharply with a 34.31% decline over the past year, pointing to momentum that has recently faded as investors reassess risk in light of events like the class action notice.
Balance recent volatility in DICK'S Sporting Goods by scanning hand-picked retailers and consumer names with resilient financials. Use the list of solid balance sheet and fundamentals (25 results) as a starting point for ideas.
DICK'S Sporting Goods still runs a broad, profitable retail platform, yet the share price has swung sharply in recent months. Is this now a solid business at a stretched tag, or a reset entry point?
Most Popular Narrative: 28% Overvalued
DICK'S Sporting Goods closed at $144.35, while the most followed narrative fair value sits at $112.77, implying a valuation premium that rests heavily on how investors interpret the recent Foot Locker reset and management's messaging.
Management's structural response to the guidance revision rests on a consistent rhetorical architecture. The DICK'S business is performing; the headwinds are real but temporary; the investments being made today are exactly the right investments. Each claim is internally defensible. Taken together, they produce a framework in which virtually any near-term result can be framed as consistent with long-term strategy. That is not an accusation; it is a description of how the communication is built.
See why 2 investors see DICK'S Sporting Goods as 28% overvalued.
Result: Fair Value of $112.77 (OVERVALUED)
Still, the DICK'S Sporting Goods narrative could be tested if Foot Locker underperformance drags on or if the more aggressive promotional backdrop proves sticky for longer than guided.
Find out about the key risks to this DICK'S Sporting Goods narrative.
Another View: What DICK'S Sporting Goods' P/E Is Saying
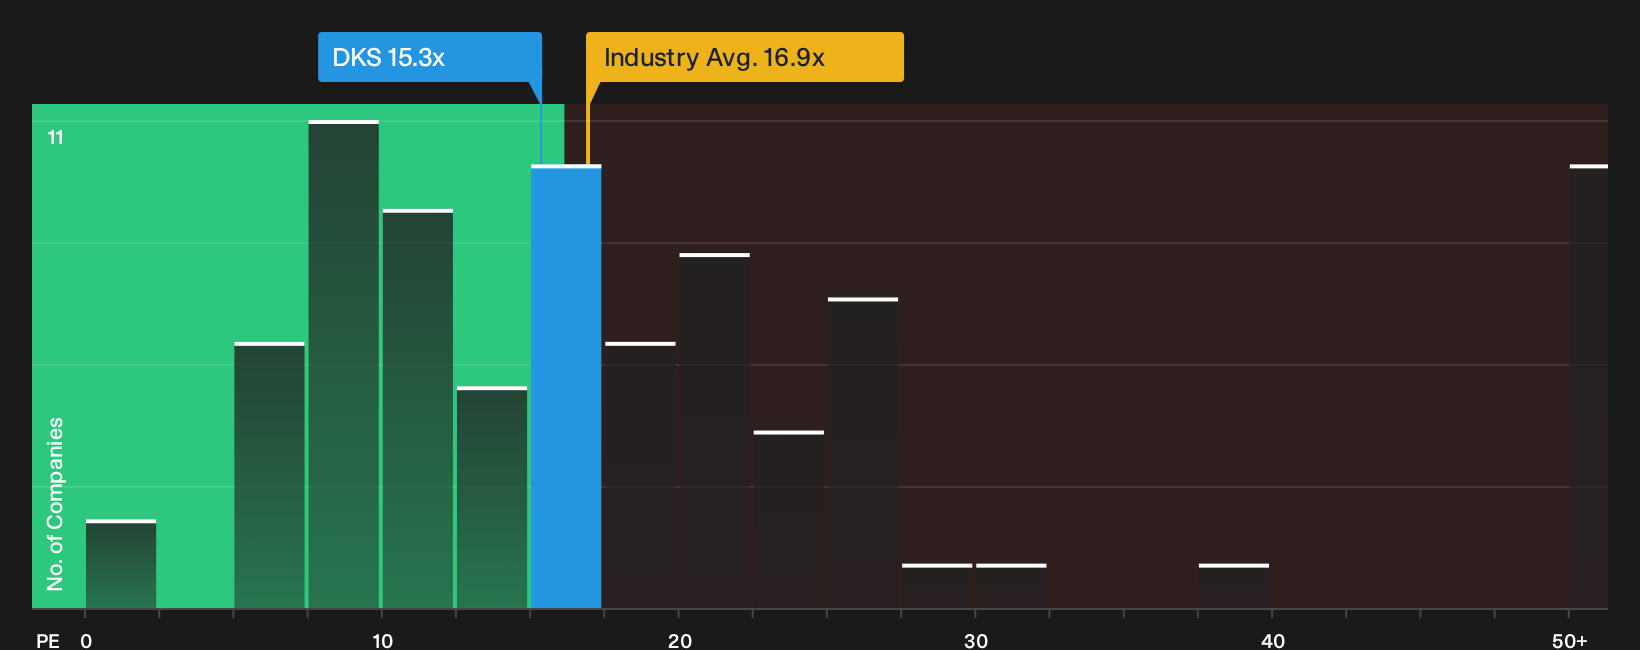
The most followed narrative flags DICK'S Sporting Goods as 28% overvalued against a $112.77 fair value, yet the current P/E of 15.3x tells a softer story. It sits below the US market on 18.1x, under the US Specialty Retail group on 16.9x, and even below a fair ratio of 18.7x.
In practice, that means the headline premium to narrative fair value sits alongside a discount to both peers and the fair ratio. This can point either to earnings risk the market is already weighing or to patience being rewarded if profitability stabilizes. Which explanation feels closer to what you see in the Foot Locker and margin reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of this DICK'S Sporting Goods story so far? Consider acting promptly, reviewing both the caution flags and the upside angles, and grounding your stance in 3 key rewards and 4 important warning signs.
Looking for more DICK'S Sporting Goods investment ideas?
Do not stop your research with one retailer. Use the Simply Wall St Screener to size up fresh opportunities that could better match your risk and return preferences.
- Target potential mispricing by scanning the 33 high quality undervalued stocks that combine solid fundamentals with prices that lag behind intrinsic value estimates.
- Strengthen your income plan by reviewing the 8 dividend fortresses that focus on robust payouts supported by underlying cash flows.
- Dial down portfolio stress by filtering for the 32 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com