
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exploring 3 Undervalued European Small Caps With Insider Action
As European markets navigate heightened geopolitical tensions and fluctuating energy prices, the pan-European STOXX Europe 600 Index has shown resilience with a recent advance of 2.09%. In this environment, small-cap stocks with strong fundamentals and strategic insider activity can present intriguing opportunities for investors seeking to capitalize on market inefficiencies.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Genuit Group | 21.2x | 1.2x | 39.43% | ★★★★★★ |
| LSL Property Services | 14.8x | 1.4x | 43.61% | ★★★★★☆ |
| Vp | NA | 0.6x | 35.14% | ★★★★★☆ |
| Hanza | 31.7x | 1.3x | 38.92% | ★★★★☆☆ |
| Franchise Brands | 26.9x | 2.0x | 47.99% | ★★★★☆☆ |
| Saniona | 7.6x | 3.3x | 30.45% | ★★★★☆☆ |
| Nyab | 19.2x | 0.9x | 31.52% | ★★★☆☆☆ |
| Cibus Real Estate | 11.1x | 4.6x | -2803.47% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -229.38% | ★★★☆☆☆ |
| Linc | 12.1x | 12.5x | 34.59% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
Domino's Pizza Group (LSE:DOM)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Domino's Pizza Group is a leading pizza delivery and carryout company in the UK, operating a network of franchised and corporate-owned stores, with a market capitalization of approximately £1.38 billion.
Operations: Domino's Pizza Group generates revenue primarily through its sales operations, with a significant portion of costs attributed to the cost of goods sold (COGS). Over recent periods, the company's gross profit margin has shown some variation, reaching 47.99% in December 2024 before declining to 45.57% by June 2026. Operating expenses and non-operating expenses also play a role in shaping net income outcomes for the company.
PE: 15.2x
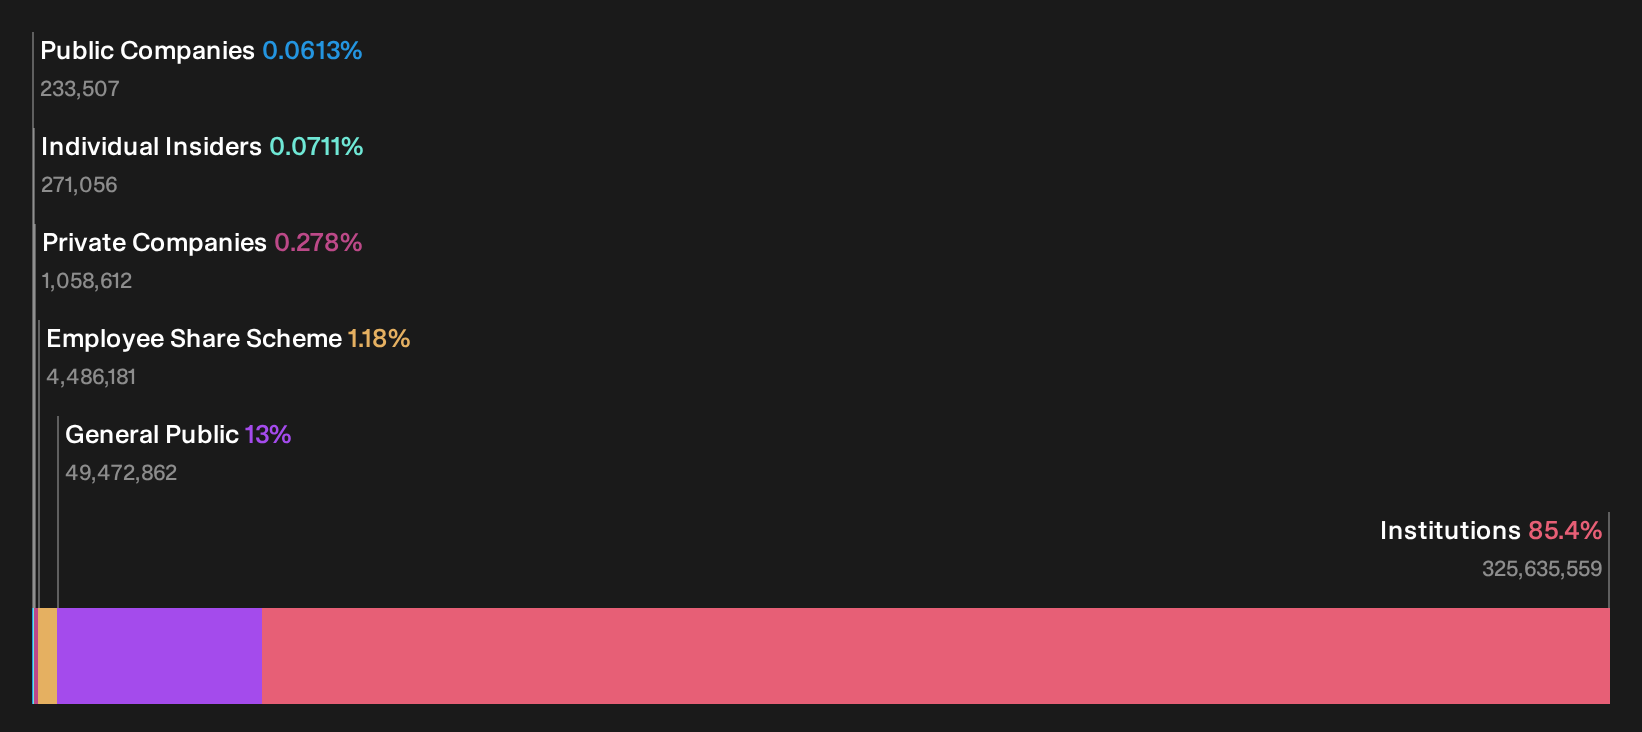
Domino's Pizza Group, a smaller player in the European market, shows potential with its recent financial performance. In the first half of 2026, sales increased to £353.6 million from £331.5 million year-on-year, while net income rose slightly to £30.6 million. Despite high debt levels and reliance on external borrowing, insider confidence is evident through share purchases over the past year. The company’s earnings are projected to grow by 9.73% annually, indicating promising future prospects amidst financial challenges.
Schroder Real Estate Investment Trust (LSE:SREI)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Schroder Real Estate Investment Trust is a UK-based company focused on property investment, with operations primarily generating revenue from its £31.12 million property portfolio.
Operations: The primary revenue stream is derived from property investment, with the latest reported revenue at £31.12 million. The gross profit margin has shown a notable trend, reaching 84.62% as of September 2024 and continuing above 80% in subsequent periods until March 2026. Operating expenses have consistently remained under £2 million in recent periods, contributing to the company's financial performance dynamics.
PE: 14.8x
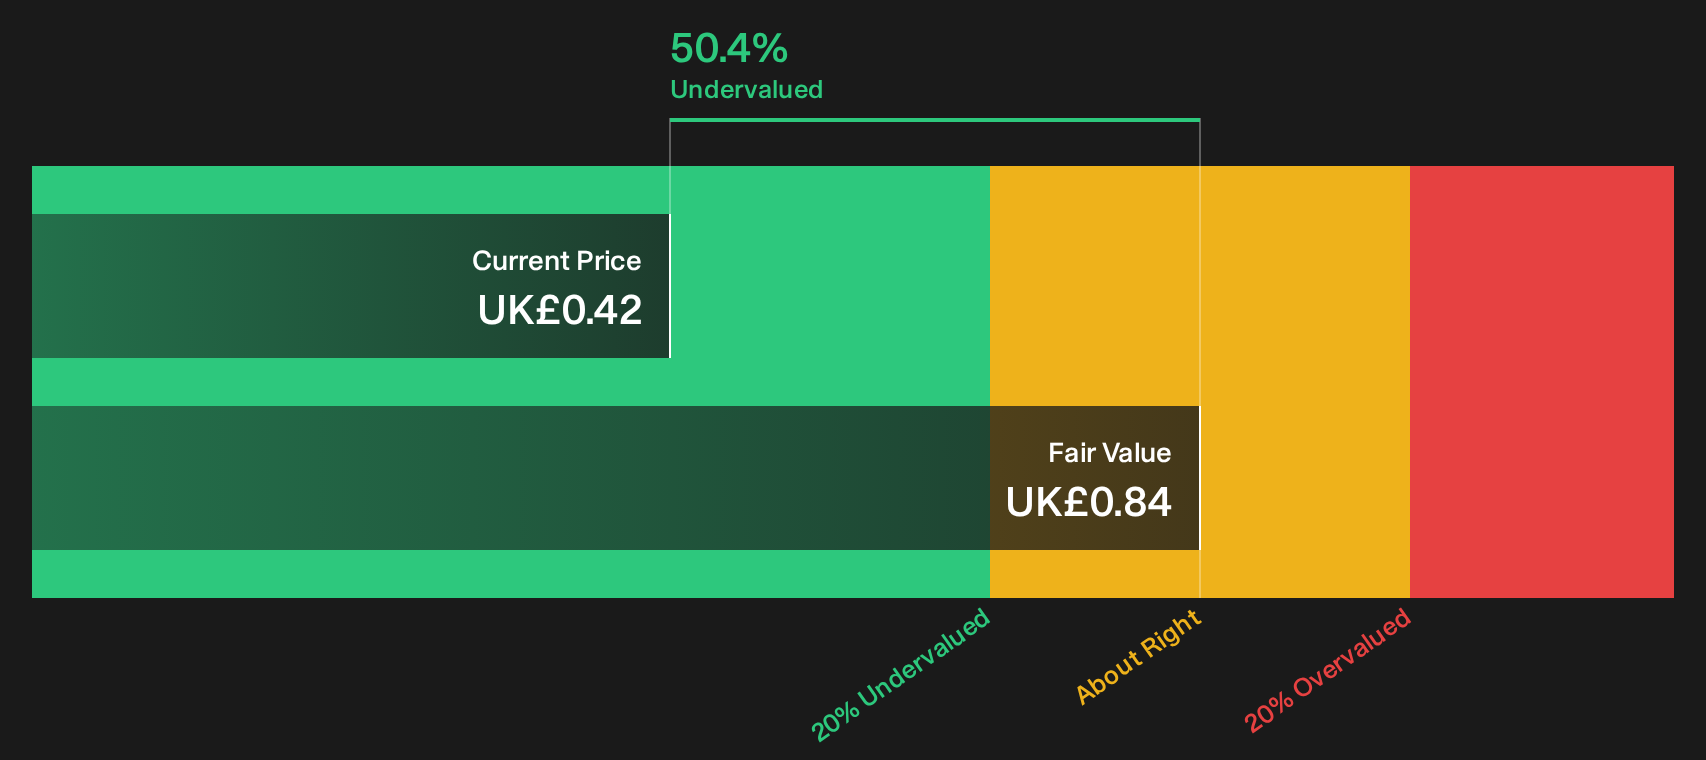
Schroder Real Estate Investment Trust, a smaller player in the European market, has been catching attention due to its insider confidence. Recent share purchases by insiders indicate a belief in its potential despite earnings declining annually by 15% over the past five years. Although debt coverage remains a concern with operating cash flow falling short, the company continues rewarding shareholders with dividends like the recent £0.00897 per share payout for Q2 2026. Future growth hinges on overcoming these financial challenges while leveraging insider optimism.
Cibus Real Estate (OM:CIBUS)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Cibus Real Estate focuses on the ownership and management of properties, with a market cap of €0.28 billion.
Operations: The primary revenue stream for Cibus Real Estate comes from the ownership and management of properties, generating €202.2 million in the latest period. The company's gross profit margin has shown an upward trend, reaching 83.93% recently, indicating a strong ability to manage costs relative to revenue growth. Operating expenses have been consistently increasing over recent periods, with general and administrative expenses being a significant component.
PE: 11.1x
Cibus Real Estate, a smaller European entity, is capturing attention with insider confidence as their CEO and Director acquired 15,435 shares valued at approximately SEK 1.88 million. This move signifies potential belief in the company's prospects despite challenges like reliance on external borrowing for funding and forecasted earnings decline of 2.4% annually over three years. Recent financial maneuvers include issuing SEK 700 million in green notes to refinance existing debt, reflecting strategic management of liabilities amidst modest revenue growth expectations.
- Delve into the full analysis valuation report here for a deeper understanding of Cibus Real Estate.
Explore historical data to track Cibus Real Estate's performance over time in our Past section.

Taking Advantage
- Dive into all 38 of the Undervalued European Small Caps With Insider Buying we have identified here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com