
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Equities Priced Below Estimated Value In October 2026
In October 2026, the European market has seen a notable shift in investor focus towards corporate fundamentals as the earnings reporting season unfolds, amidst ongoing geopolitical tensions and fluctuating energy prices. With the pan-European STOXX Europe 600 Index advancing and major indices like Germany's DAX and France's CAC 40 showing gains, investors are increasingly seeking stocks that appear undervalued based on their intrinsic value relative to current market conditions. Identifying such opportunities often involves looking for companies with strong fundamentals that may have been overlooked due to broader market trends or temporary setbacks.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valmet Oyj (HLSE:VALMT) | €27.32 | €53.76 | 49.2% |
| Sentia (OB:SNTIA) | NOK80.80 | NOK157.18 | 48.6% |
| PORR (WBAG:POS) | €31.00 | €61.44 | 49.5% |
| Orthex Oyj (HLSE:ORTHEX) | €4.40 | €8.71 | 49.5% |
| Lindab International (OM:LIAB) | SEK130.30 | SEK253.54 | 48.6% |
| Huuuge (WSE:HUG) | PLN24.25 | PLN45.44 | 46.6% |
| Erste Group Bank (WBAG:EBS) | €110.10 | €219.92 | 49.9% |
| Eni (BIT:ENI) | €25.955 | €51.43 | 49.5% |
| DWS Group GmbH KGaA (XTRA:DWS) | €66.10 | €127.43 | 48.1% |
| Apator (WSE:APT) | PLN25.75 | PLN50.24 | 48.7% |
Let's take a closer look at a couple of our picks from the screened companies.
Azimut Holding (BIT:AZM)
Overview: Azimut Holding S.p.A. offers asset management and advisory solutions across various regions including Italy, Europe, the Middle East, the Americas, and the Asia-Pacific with a market cap of €4.97 billion.
Operations: The company generates its revenue primarily from the Asset Management segment, which accounts for €1.57 billion.
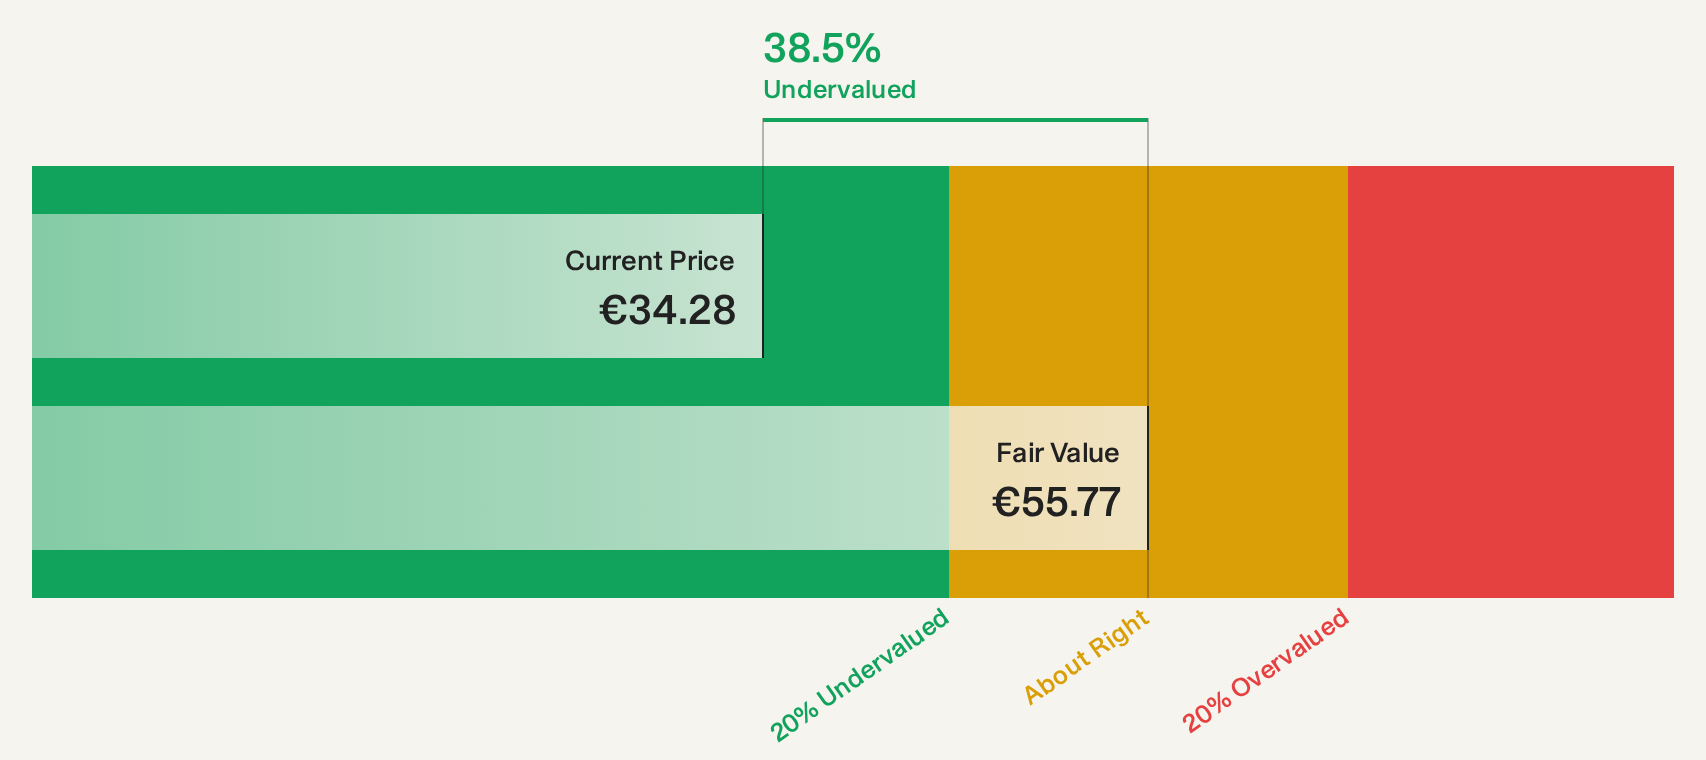
Estimated Discount To Fair Value: 37.5%
Azimut Holding appears undervalued based on discounted cash flow analysis, trading at €34.84 against an estimated cash flow value of €55.78, a significant discount. Despite a modest 0.2% annual earnings growth over five years, revenue is projected to grow by 7.91% annually, outpacing the Italian market's average growth rate of 5.6%. The company has initiated a share buyback program and maintains its earnings guidance for 2026 at €450 million net income excluding extraordinary items.
- Insights from our recent growth report point to a promising forecast for Azimut Holding's business outlook.
- Take a closer look at Azimut Holding's balance sheet health here in our report.
Boliden (OM:BOL)
Overview: Boliden AB (publ) is involved in the extraction, production, and recycling of base metals across Sweden, Finland, other Nordic regions, Germany, the United Kingdom, Europe, North America, and internationally with a market cap of approximately SEK151.52 billion.
Operations: The company's revenue segments include Mines, generating SEK35.56 billion, and Smelters, contributing SEK96.71 billion.
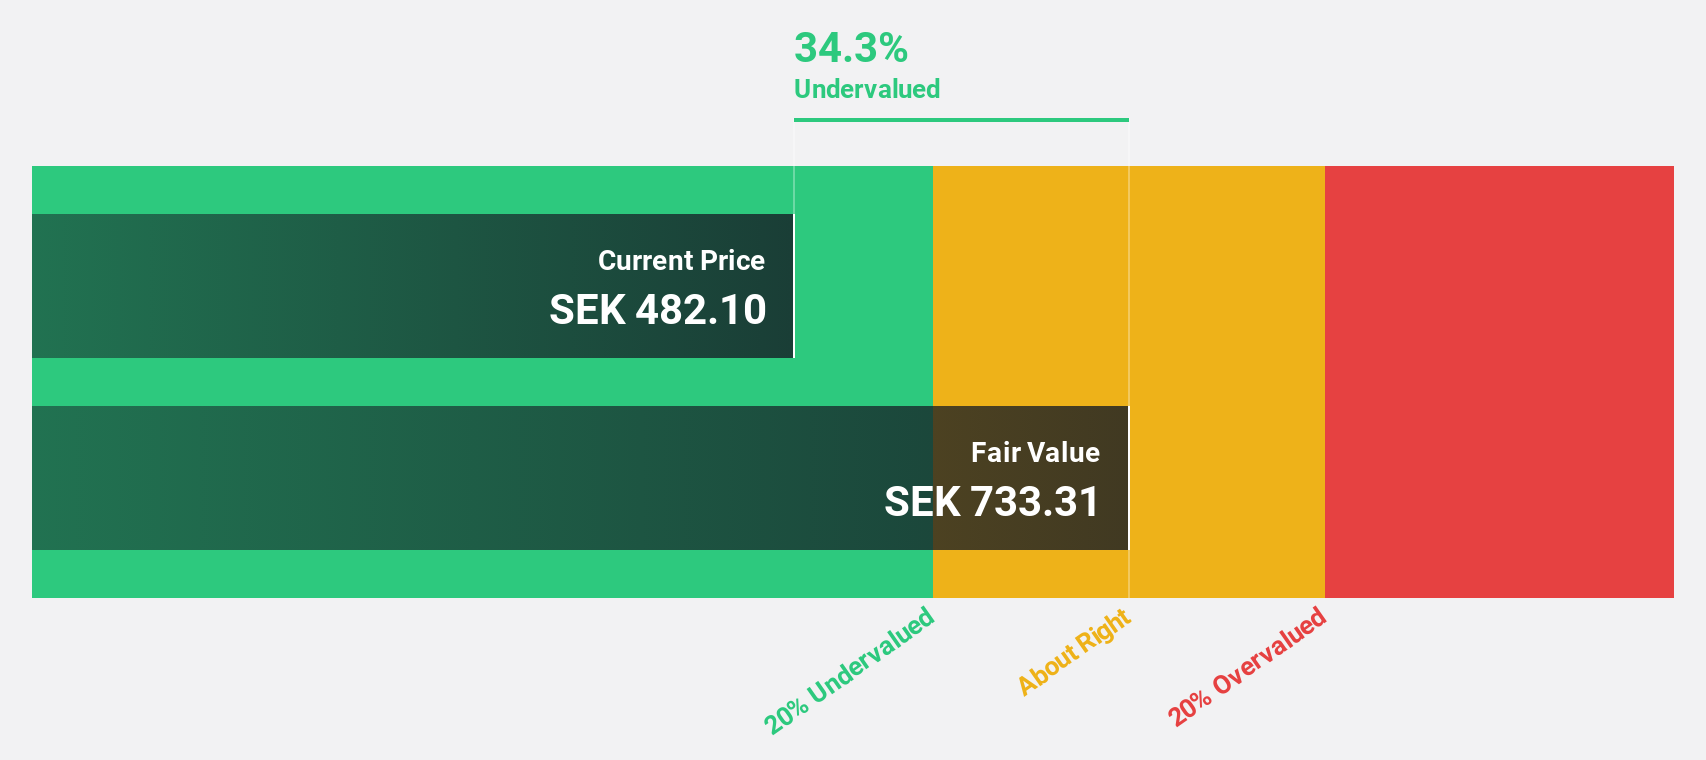
Estimated Discount To Fair Value: 43.8%
Boliden is trading at SEK533.6, significantly below its estimated future cash flow value of SEK948.96, representing a substantial discount. Earnings grew 57.7% last year and are expected to grow 11% annually, outpacing the Swedish market's 7.7%. Despite unstable dividends and slower revenue growth compared to industry benchmarks, Boliden's strategic moves, including acquiring a stake in Nexa Resource and advancing the Laver mining project, bolster its long-term prospects in Europe's mining sector.
- Upon reviewing our latest growth report, Boliden's projected financial performance appears quite optimistic.
- Navigate through the intricacies of Boliden with our comprehensive financial health report here.
Erste Group Bank (WBAG:EBS)
Overview: Erste Group Bank AG offers a range of banking and financial services to retail, corporate, and public sector clients, with a market cap of €42.73 billion.
Operations: The company's revenue segments include Retail (€5.21 billion), Corporates (€2.40 billion), Group Markets (€922 million), and Savings Banks (€2.53 billion).
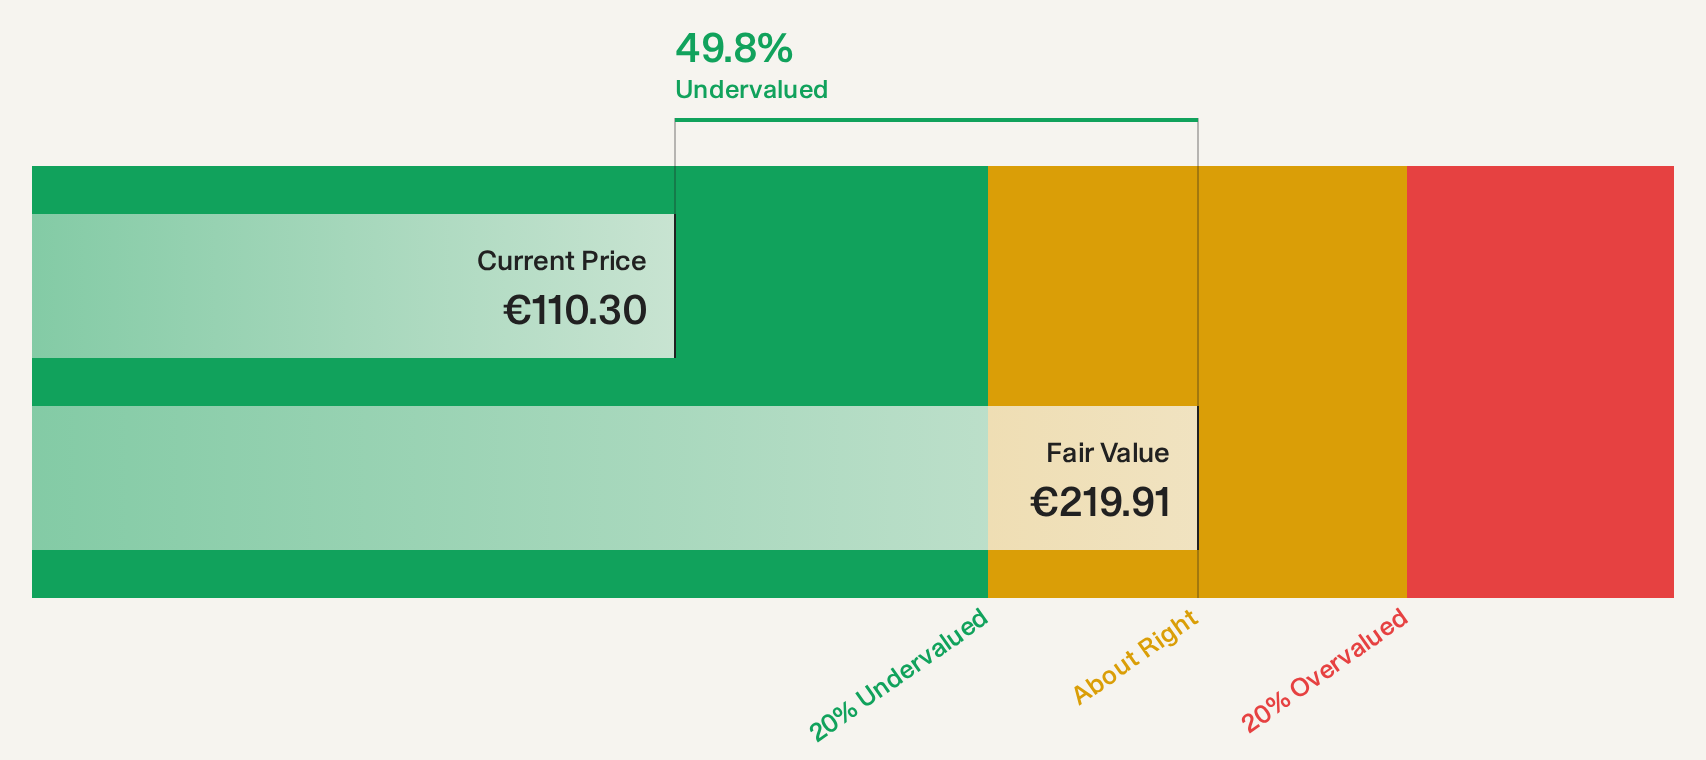
Estimated Discount To Fair Value: 49.9%
Erste Group Bank, trading at €110.1, is significantly undervalued compared to its estimated future cash flow value of €219.92. The bank's earnings are forecast to grow 10.74% annually, surpassing the Austrian market's 9.3%. While it has a high level of bad loans at 2.2%, recent fixed-income offerings totaling over €5 billion reflect robust capital management strategies and provide liquidity for growth initiatives in asset management and digital investing solutions across core markets.
- The growth report we've compiled suggests that Erste Group Bank's future prospects could be on the up.
- Click here to discover the nuances of Erste Group Bank with our detailed financial health report.
Key Takeaways
- Click here to access our complete index of 73 Undervalued European Stocks Based On Cash Flows.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com