
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Growth Stocks Insiders Are Betting On
As European markets experience a shift in focus back to corporate fundamentals amid geopolitical tensions and fluctuating energy prices, investors are keenly observing growth opportunities within the region. In this environment, companies with high insider ownership often attract attention as they suggest confidence from those who know the business best, potentially aligning with broader market trends.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Egetis Therapeutics (OM:EGTX) | 18.4% | 49.5% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.4% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 35.4% |
Here we highlight a subset of our preferred stocks from the screener.
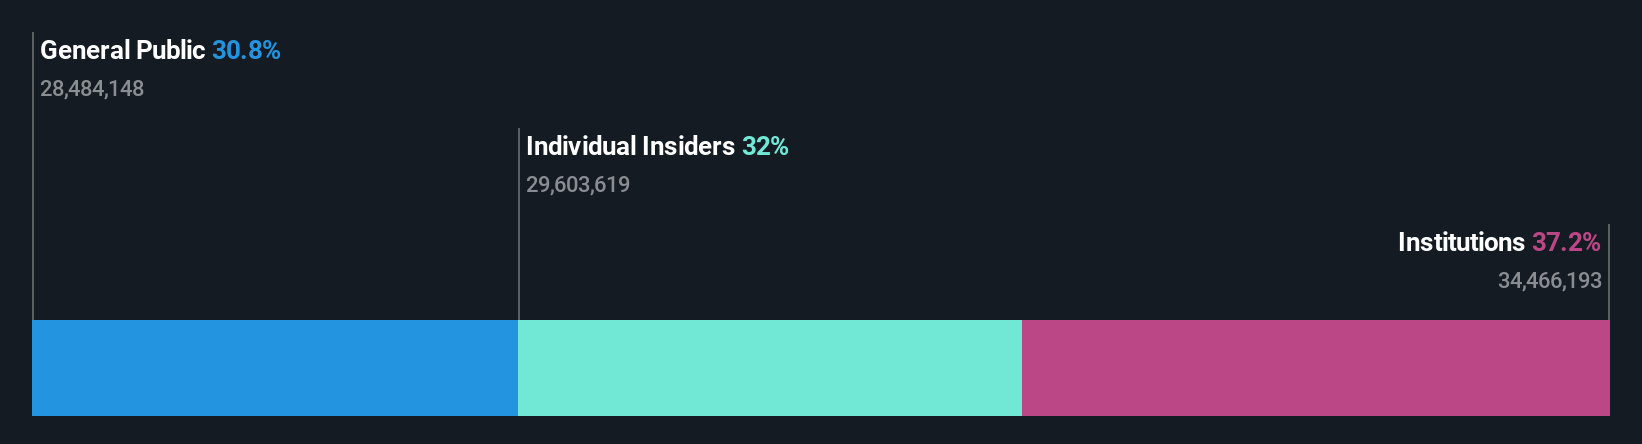
Bilia (OM:BILI A)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Bilia AB (publ) operates as a full-service supplier for car ownership in Sweden, Norway, Luxembourg, and Belgium with a market cap of SEK13.35 billion.
Operations: The company's revenue is derived from several segments: Car sales in Sweden (SEK20.03 billion), Norway (SEK7.99 billion), and Western Europe (SEK3.74 billion); Service operations in Sweden (SEK6.95 billion), Norway (SEK2.69 billion), and Western Europe (SEK837 million); as well as Fuel sales amounting to SEK806 million, alongside contributions from Corporate Functions totaling SEK1.40 billion.
Insider Ownership: 30.9%
Earnings Growth Forecast: 15.8% p.a.
Bilia's earnings are forecast to grow at 15.8% annually, outpacing the Swedish market average of 7.7%, while revenue is expected to increase by 5.2% per year, surpassing the market's decline. Despite trading at a discount of 35.8% below estimated fair value, Bilia faces challenges with high debt levels and an unsustainable dividend yield of 4.12%. The company shows no significant insider trading activity in recent months, indicating stable insider confidence without substantial buying or selling trends.
- Delve into the full analysis future growth report here for a deeper understanding of Bilia.
- Our expertly prepared valuation report Bilia implies its share price may be lower than expected.
Eastnine (OM:EAST)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Eastnine AB (publ) is a real estate investment firm with a market cap of SEK4.19 billion.
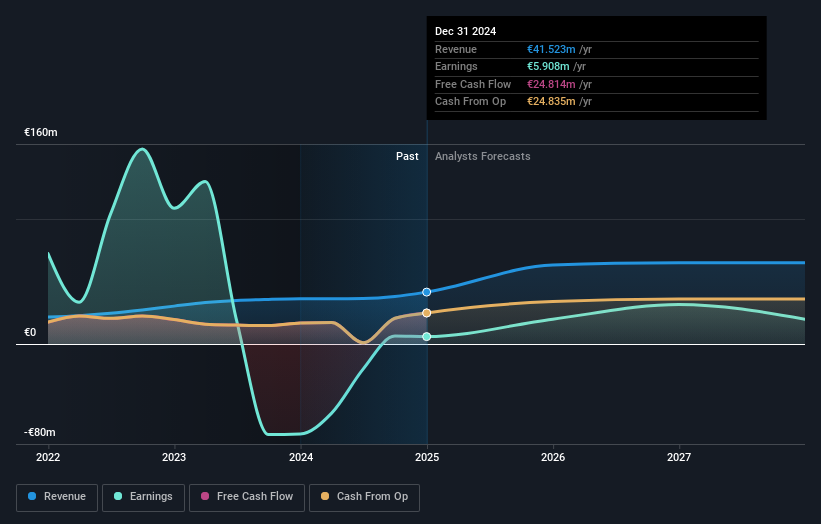
Operations: The firm's revenue segments include properties in Riga, Latvia (€3.54 million), Poznan, Poland (€14.72 million), Warsaw, Poland (€18.14 million), and Vilnius, Lithuania (€25.26 million).
Insider Ownership: 23.5%
Earnings Growth Forecast: 20.1% p.a.
Eastnine's earnings are projected to grow at 20.1% annually, significantly outpacing the Swedish market's 7.7%. Despite a low Return on Equity forecast of 6.7%, Eastnine offers value with a Price-To-Earnings ratio of 14.2x, below the market average. Recent acquisition of The Bridge in Warsaw for €240m enhances its portfolio and is expected to boost property management profits per share by 18% by end-2027, supported by high insider ownership stability and minimal recent selling activity.
- Get an in-depth perspective on Eastnine's performance by reading our analyst estimates report here.
- Our expertly prepared valuation report Eastnine implies its share price may be too high.
Stadler Rail (SWX:SRAIL)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Stadler Rail AG is a Swiss company that manufactures and sells trains across various regions including Europe, the Americas, and CIS countries, with a market cap of CHF3.12 billion.
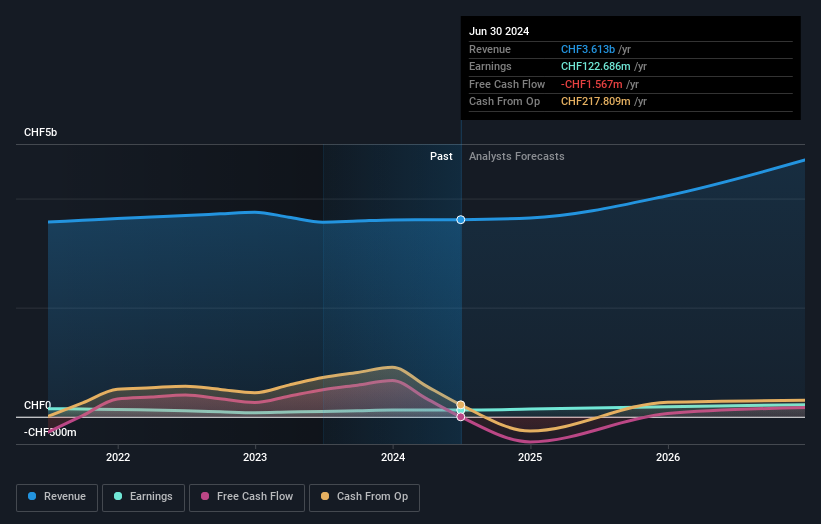
Operations: The company's revenue is primarily derived from its Rolling Stock segment at CHF3.52 billion, followed by Service & Components at CHF1.09 billion, and Signalling at CHF210.99 million.
Insider Ownership: 14.4%
Earnings Growth Forecast: 29.5% p.a.
Stadler Rail's earnings are forecast to grow significantly at 29.47% annually, surpassing the Swiss market's growth rate. Despite this, its share price has been highly volatile recently. The company is trading at 72.1% below estimated fair value, suggesting potential undervaluation. Recent executive changes include Philipp Brunner succeeding Markus Bernsteiner as CEO in January 2027, ensuring continuity with Brunner's extensive industry experience and leadership within Stadler’s divisions in Europe and Germany.
- Navigate through the intricacies of Stadler Rail with our comprehensive analyst estimates report here.
- Insights from our recent valuation report point to the potential undervaluation of Stadler Rail shares in the market.
Key Takeaways
- Click this link to deep-dive into the 205 companies within our Fast Growing European Companies With High Insider Ownership screener.
- Want To Explore Some Alternatives? Trump has pledged to "unleash" American oil and gas and these 22 US stocks have developments that are poised to benefit.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com