
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
InterDigital (IDCC) Stock Looks Reasonably Priced On Royalty Earnings
InterDigital has delivered a powerful long term run, yet recent price softness raises a straightforward question for you as a shareholder or potential buyer: Is the current valuation still supported by what the business earns today and what its earnings may reasonably support over time?
- Over the past 5 years the stock has returned about 406.4%, which puts a lot of accumulated optimism on the line when you ask whether the earnings profile still backs up the price.
- The company’s model is built around licensing and monetising its intellectual property, so the durability of those royalty streams can shape how much investors are willing to pay for each dollar of profit.
- There is a second opinion on InterDigital worth weighing. See what analysts think InterDigital's shares could be worth.
The issue now is whether InterDigital’s current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want more context on what a strong multi year run like InterDigital's might look like elsewhere, compare it with 33 high quality undervalued stocks.
Where Does InterDigital Sit on Earnings?
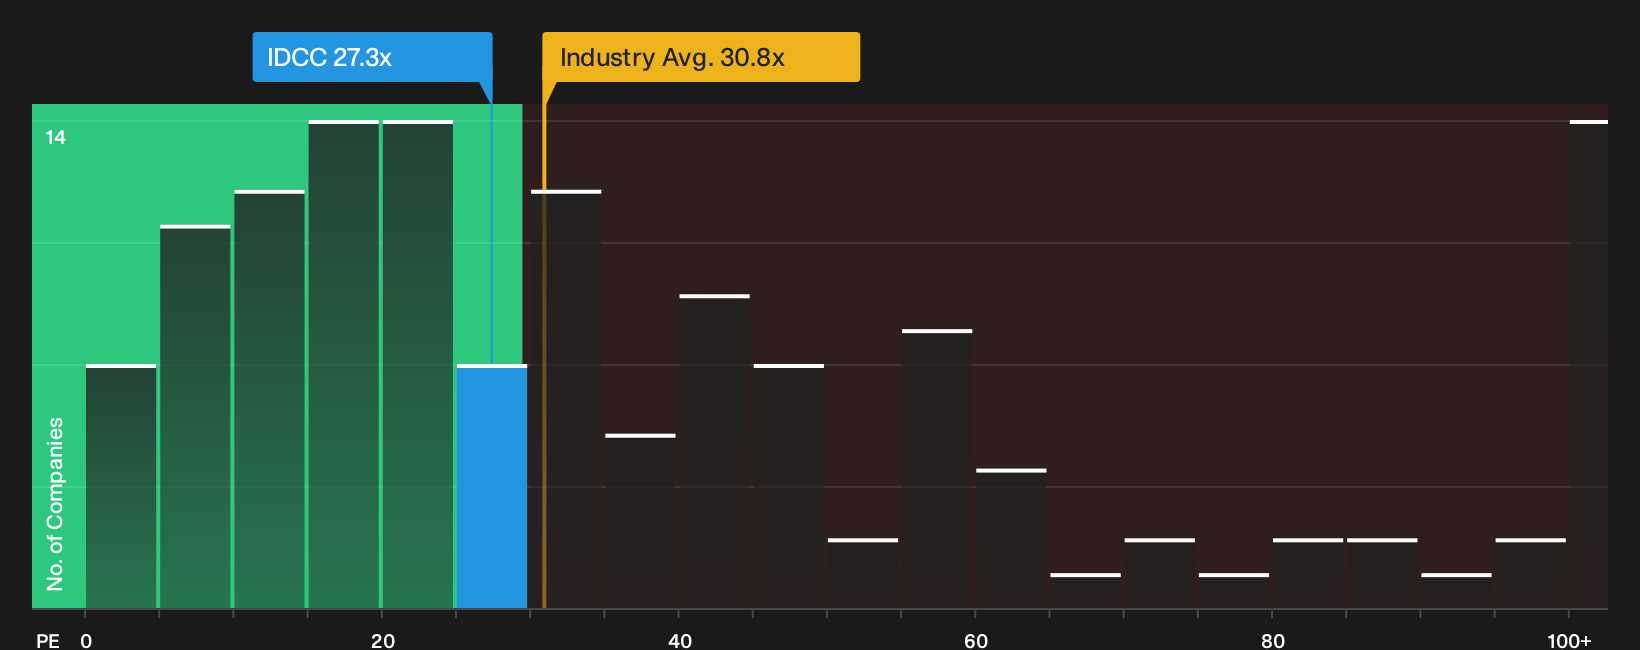
The P/E ratio fits InterDigital because earnings remain the core yardstick for a licensing driven business. The current P/E sits near 27.3x, which is lower than the broader software industry average of about 30.8x and well below the peer group sitting around 45.6x. For a stock built on recurring royalty income, that difference gives you a clear indication of how much the market is willing to pay for each dollar of profit today.
A Fair Ratio model, which blends factors like growth profile, profitability, risk and size into a more customised benchmark, points to a level slightly under the current 27.3x. That places InterDigital just above what this framework would suggest as a balanced price, rather than sharply overvalued or clearly cheap on earnings. The gap between the market multiple and this tailored yardstick is not extreme. The key question for you is whether the patent portfolio and licensing pipeline feel strong enough to justify paying around this earnings tag. Explore the numbers behind InterDigital's P/E valuation.
The InterDigital Narrative: What Would Justify Today's Price?
Narratives act as the missing link between InterDigital's current P/E puzzle and the expectations implied in the share price. They spell out what kind of future growth, profitability and earnings profile would need to unfold for the stock to be worth significantly more or less than it is today on Simply Wall St's Community page. Each Narrative ties its number to a clear view on where InterDigital's growth, margin structure and key risks might head next. You can come back to this as fresh information emerges.
One of the top community narratives on InterDigital: 31% undervalued
"The combination of a large cash position of about US$1.1b and an ARR base of US$625.7m that is heavily weighted to long term fixed fee contracts provides financial capacity for continued dividends and capital returns..."
Discover why this Narrative puts InterDigital at 31% undervalued.
One more piece of the InterDigital puzzle worth checking
The royalty engine and current P/E only tell part of the story, because the people steering InterDigital and the way they are rewarded can heavily influence where the business goes next. See who runs InterDigital and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com