
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
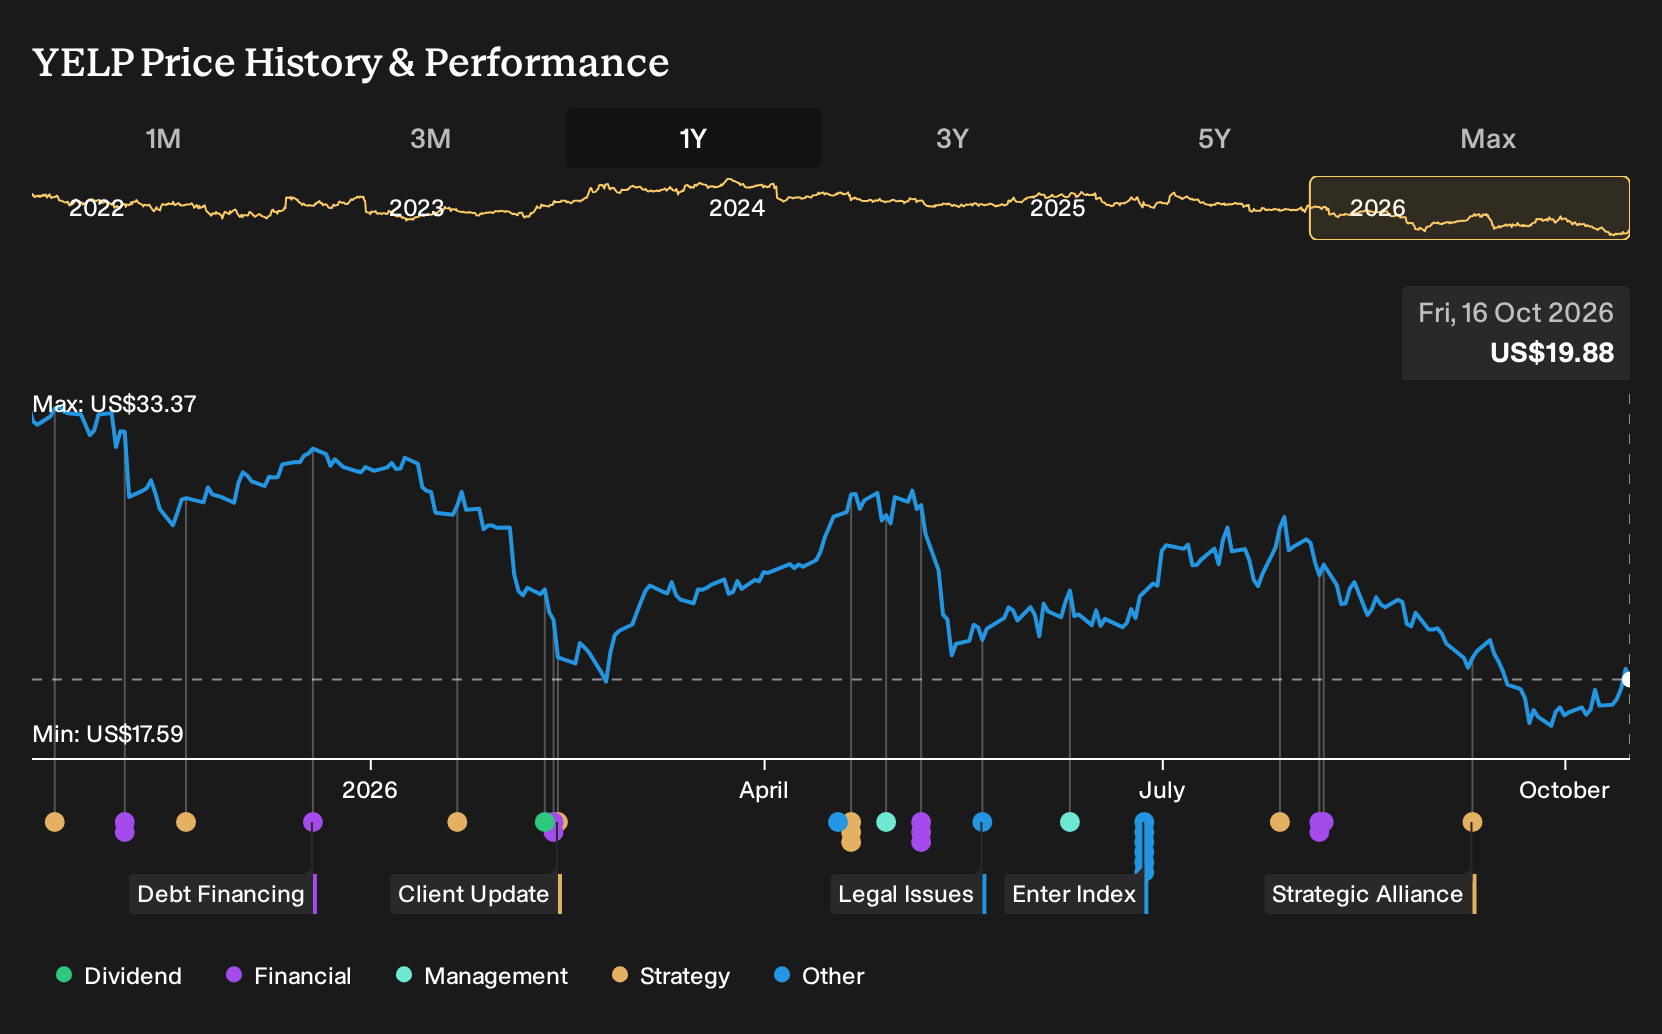
Yelp Fell While Sales Rose
If you had looked at Yelp in late 2025 and decided to wait for clearer proof that its AI push and new integrations were working, the choice probably felt cautious rather than bold. Investors who held Yelp over the past year are down 38.8%, including dividends. With fresh headlines about OpenAI deals, Amazon partnerships, and softer profitability now in view, which assumption from a year ago most deserved a harder look before committing capital?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Yelp. See which of 38 AI small caps may still merit a closer look.
The Two Yelp Narratives Investors Had To Weigh
The shares cost US$32.66 at the start of the period, and anyone looking at Yelp then had two competing stories to weigh up.
On the bullish side, the Fair Value was US$34.44, based on the idea that AI integration and Zapier workflows would lift engagement. That view leaned on assumptions of 3.5% annual revenue growth and profit margins reaching 12.0% in three years.
The more cautious narrative put Fair Value at US$30. It rested on 2.5% revenue growth, an 11.4% profit margin assumption, and the risk that tech giants using generative AI and tighter privacy rules would chip away at Yelp’s ad model.
What The Results Put To The Test For Yelp
Yelp’s Q2 2026 report showed revenue at US$375.5m and net income at US$31.7m, which meant a lower net margin of 8.4% compared with 11.9% a year earlier. That record challenged the bullish view that AI tools and partnerships would quickly lift profitability, so the period ultimately supported a more cautious interpretation.
The key assumption here was that AI integrations would expand margin as well as revenue. For any other stock, it may be useful to track whether new products appear in both the top line and the net margin before treating them as established earnings drivers.
What Today’s Yelp Price Already Assumes
Yelp trades at US$19.88, and the selected Narrative’s Fair Value sits above that level based on its own assumptions. That view leans on AI products, subscription tools, and licensing helping to counter ongoing pressure in core local ads.
For the recent fall to look like opportunity rather than warning, a buyer would need to believe Yelp can scale AI driven services and licensing quickly enough to outweigh weak restaurant, retail, and services advertising.
"The rapid adoption and expansion of AI-powered features like Yelp Assistant and the rollout of new entry points, including to logged out users, are expected to boost overall user engagement and the stickiness of the platform, which should contribute to increased lead generation and higher advertising revenues over time."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 35% below our estimate - uses a large super app client base to push deeper into secured, higher yielding credit.
- Company 2 - 43% below our estimate - expands beyond trackers by scaling storage, inverter and other higher margin solar hardware offerings.
- Company 3 - 41% below our estimate - ramps spending on AI, digital infrastructure and payments to drive fee income and operating leverage.
Three companies from the same screener. Open all 33 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com