
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Matador Resources (MTDR) Below Fair Value After Its Woodford Deal?
Matador Resources has delivered a 39.7% share price gain over the past 5 years, and that kind of long haul run naturally raises a question about whether its current valuation is supported by its earnings power. With the stock last closing at US$57.52 and investors digesting fresh deal news, the issue now is how much of the company’s profit profile is already reflected in that price.
- The 39.7% return over 5 years puts real weight on the question of whether Matador Resources’ earnings justify the rerating that has already happened.
- The planned acquisition that would take its Woodford position to about 50,000 net undeveloped acres can influence expectations for future production, capital spending and ultimately the earnings stream investors are using to value Matador Resources today.
- The analysts covering Matador Resources have run their own numbers. See what analysts think Matador Resources's shares could be worth.
For investors, the debate is whether Matador Resources’ current share price is in line with what its earnings profile supports when judged against the Fair Ratio benchmark.
If you are weighing whether Matador Resources’ earnings justify today’s price, it can help to compare it with a broader set of 33 high quality undervalued stocks.
Is Matador Resources a Bargain on Earnings?
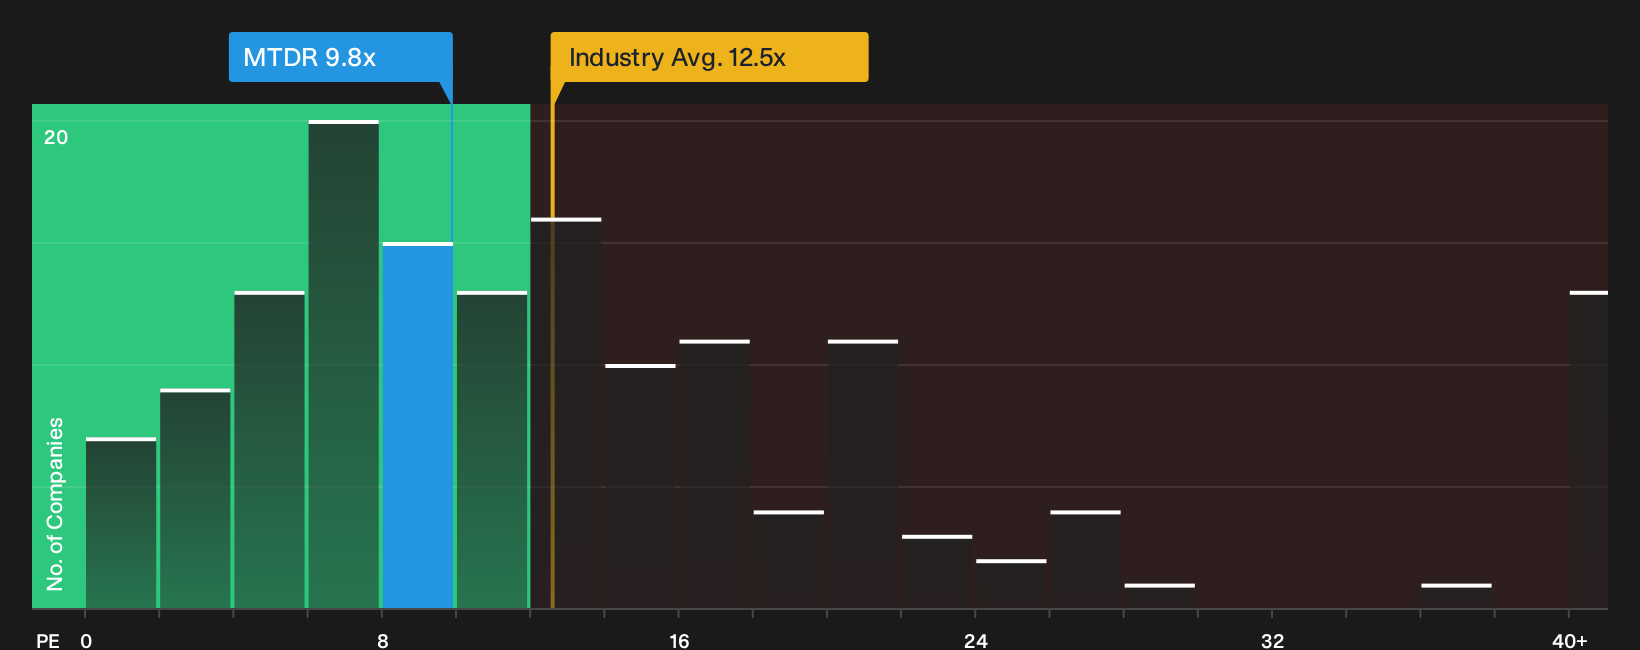
For Matador Resources, the P/E ratio works well because earnings are a key anchor for how investors assess oil and gas producers. The stock trades on about 9.8x earnings, which sits below both the oil and gas sector average of roughly 12.5x and the broader peer group near 34.2x. On the Fair Ratio framework, which estimates the multiple you might expect given Matador Resources’ mix of growth prospects, profitability, size and risk, that earnings multiple screens on the cheap side rather than expensive.
Because the firm has just completed a Delaware Basin Woodford acquisition that lifts its position to roughly 50,000 net undeveloped acres, the current discount on P/E suggests the market is not assigning a high premium to that larger footprint. The gap versus peers and the Fair Ratio does not settle whether the stock is a bargain on its own, but it signals that investors are paying less per dollar of earnings than is typical for similar oil and gas businesses. Explore the numbers behind Matador Resources's P/E valuation.
The Matador Resources Narrative: What Would Justify Today's Price?
Narratives pick up where the valuation puzzle leaves off by spelling out which earnings, margin and growth assumptions would need to hold for Matador Resources' share price to end up meaningfully higher or lower than it is today. They sit on Simply Wall St's Community page, and each one treats Matador Resources' estimated worth as a specific thesis about the business that can be revisited over time rather than a one off snapshot.
One of the top community narratives on Matador Resources: 7% undervalued
"The main factor that has to go right is that Matador Resources converts its larger Delaware Basin position, integrated midstream growth and lower drilling and completion costs into sustained free cash flow that supports both lower leverage and a consistently rising base dividend..."
Discover why this Narrative puts Matador Resources at 7% undervalued.
One more angle on Matador Resources that could change the picture
Before you treat Matador Resources as a simple P/E story, it is worth knowing that our broader checks have flagged specific issues that deserve a closer look beside the valuation work. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com