
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exploring 3 Undiscovered Gems in Asia with Strong Potential
Amid the recent volatility in global markets, with small-cap indices like the Russell 2000 experiencing notable declines, investors are increasingly looking toward Asia for opportunities that might be less impacted by current economic uncertainties. In this environment, identifying stocks with strong fundamentals and growth potential becomes crucial, as these characteristics can help navigate through market fluctuations and capitalize on emerging trends.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
Japan Eyewear Holdings (TSE:5889)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Japan Eyewear Holdings Co., Ltd., with a market cap of ¥52.73 billion, operates through its subsidiaries to plan, design, manufacture, and sell eyeglasses in Japan.
Operations: Japan Eyewear Holdings generates revenue primarily from its subsidiaries, Four Nines and Kaneko Optical, with ¥6.31 billion and ¥13.65 billion respectively.
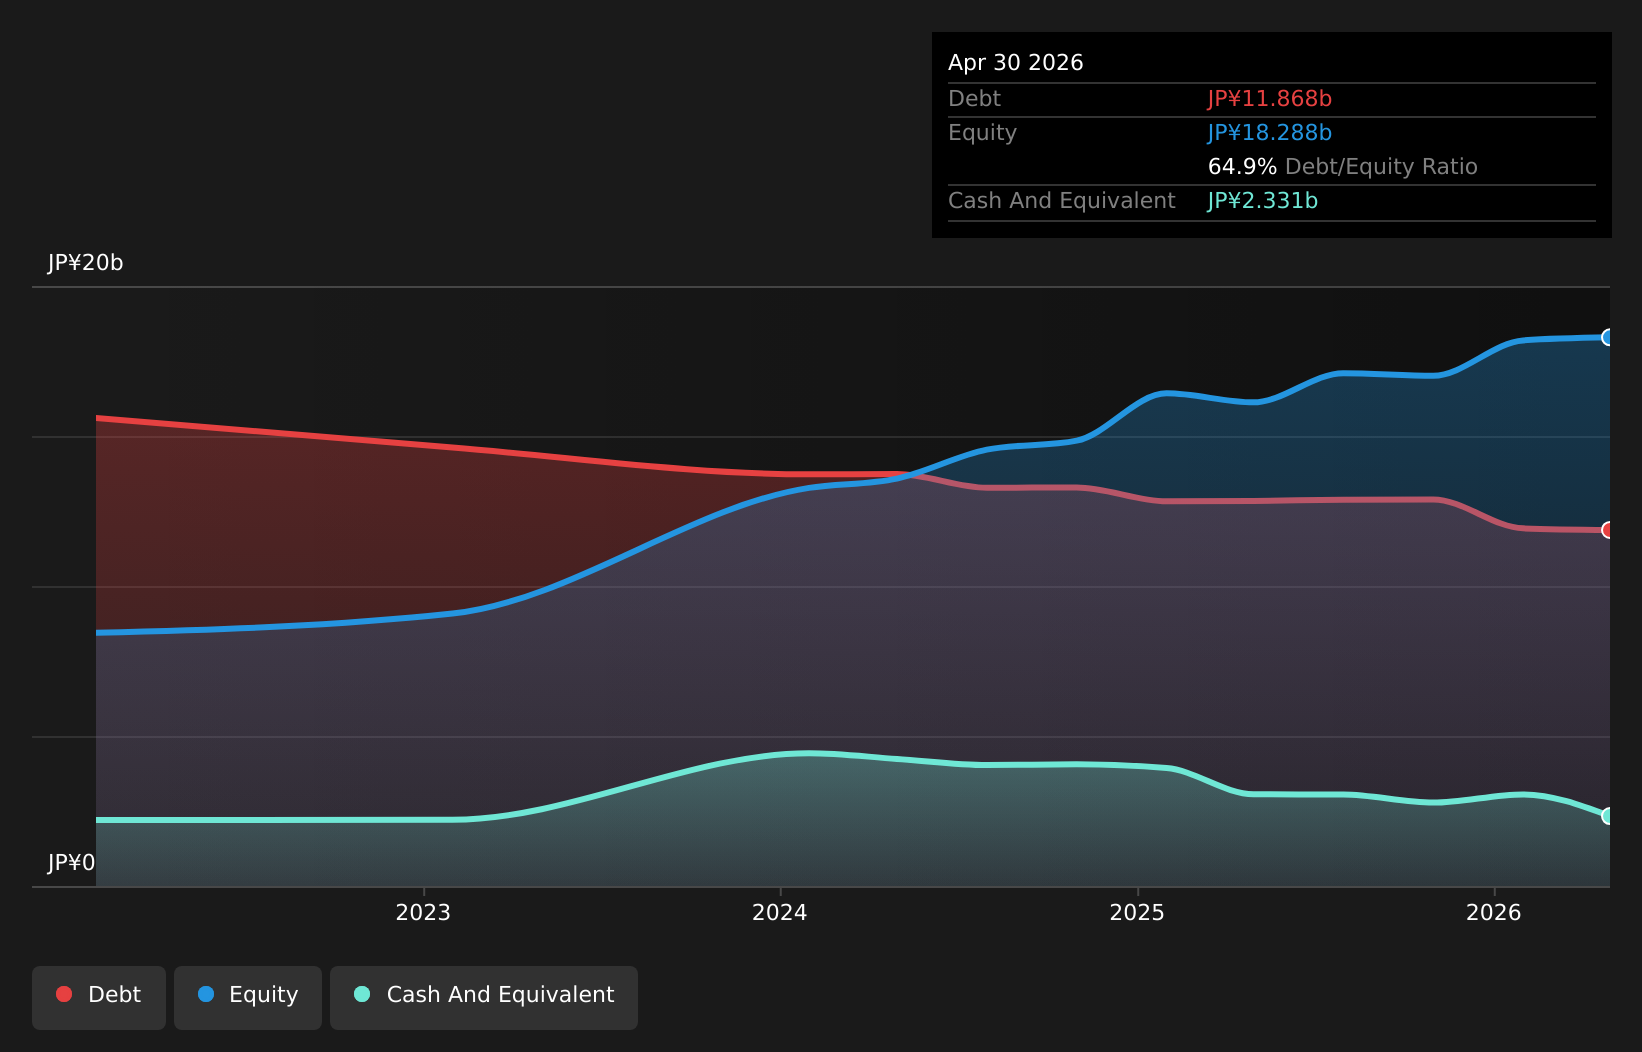
Japan Eyewear Holdings, a smaller player in the eyewear market, reported half-year sales of ¥10.26 billion, up from ¥8.94 billion last year, with net income rising to ¥2.24 billion from ¥1.74 billion. The company offers good value at 58.9% below estimated fair value and boasts high-quality earnings despite a high net debt to equity ratio of 41%. Earnings have grown impressively by 34% annually over five years but lagged behind industry growth last year at 5.4%. With EBIT covering interest payments by 18 times, financial stability seems solid despite debt concerns.
Nagase Brothers (TSE:9733)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Nagase Brothers Inc., with a market cap of approximately ¥56.07 billion, operates as an educational services provider in Japan.
Operations: Nagase Brothers generates revenue primarily from its High School Student Division and Swimming School, contributing ¥30.52 billion and ¥17.82 billion respectively. The company also earns from its Elementary and Junior High School Students Division with revenues of ¥13.42 billion, while the Business School Division adds another ¥2.01 billion to the total revenue stream.
Nagase Brothers, a relatively small player in the market, has been making waves lately. Its net debt to equity ratio of 79.7% is considered high, yet interest payments on its debt are well covered by EBIT at 64.3 times coverage. Over the past year, earnings grew impressively by 50.6%, outpacing the Consumer Services industry growth of 18.4%. The company is trading at a good value compared to peers and industry standards and was recently added to the S&P Global BMI Index as of September 2026, signaling increased visibility and potential investor interest in this promising entity.
- Dive into the specifics of Nagase Brothers here with our thorough health report.
Explore historical data to track Nagase Brothers' performance over time in our Past section.

Ta Tun Electric Wire & Cable (TWSE:1623)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Ta Tun Electric Wire & Cable Co., Ltd. is a Taiwanese company that focuses on the manufacture, processing, sale, and installation of wires and cables, with a market capitalization of NT$12.41 billion.
Operations: The primary revenue stream for Ta Tun Electric Wire & Cable comes from its wire and cable products, generating NT$6.66 billion.
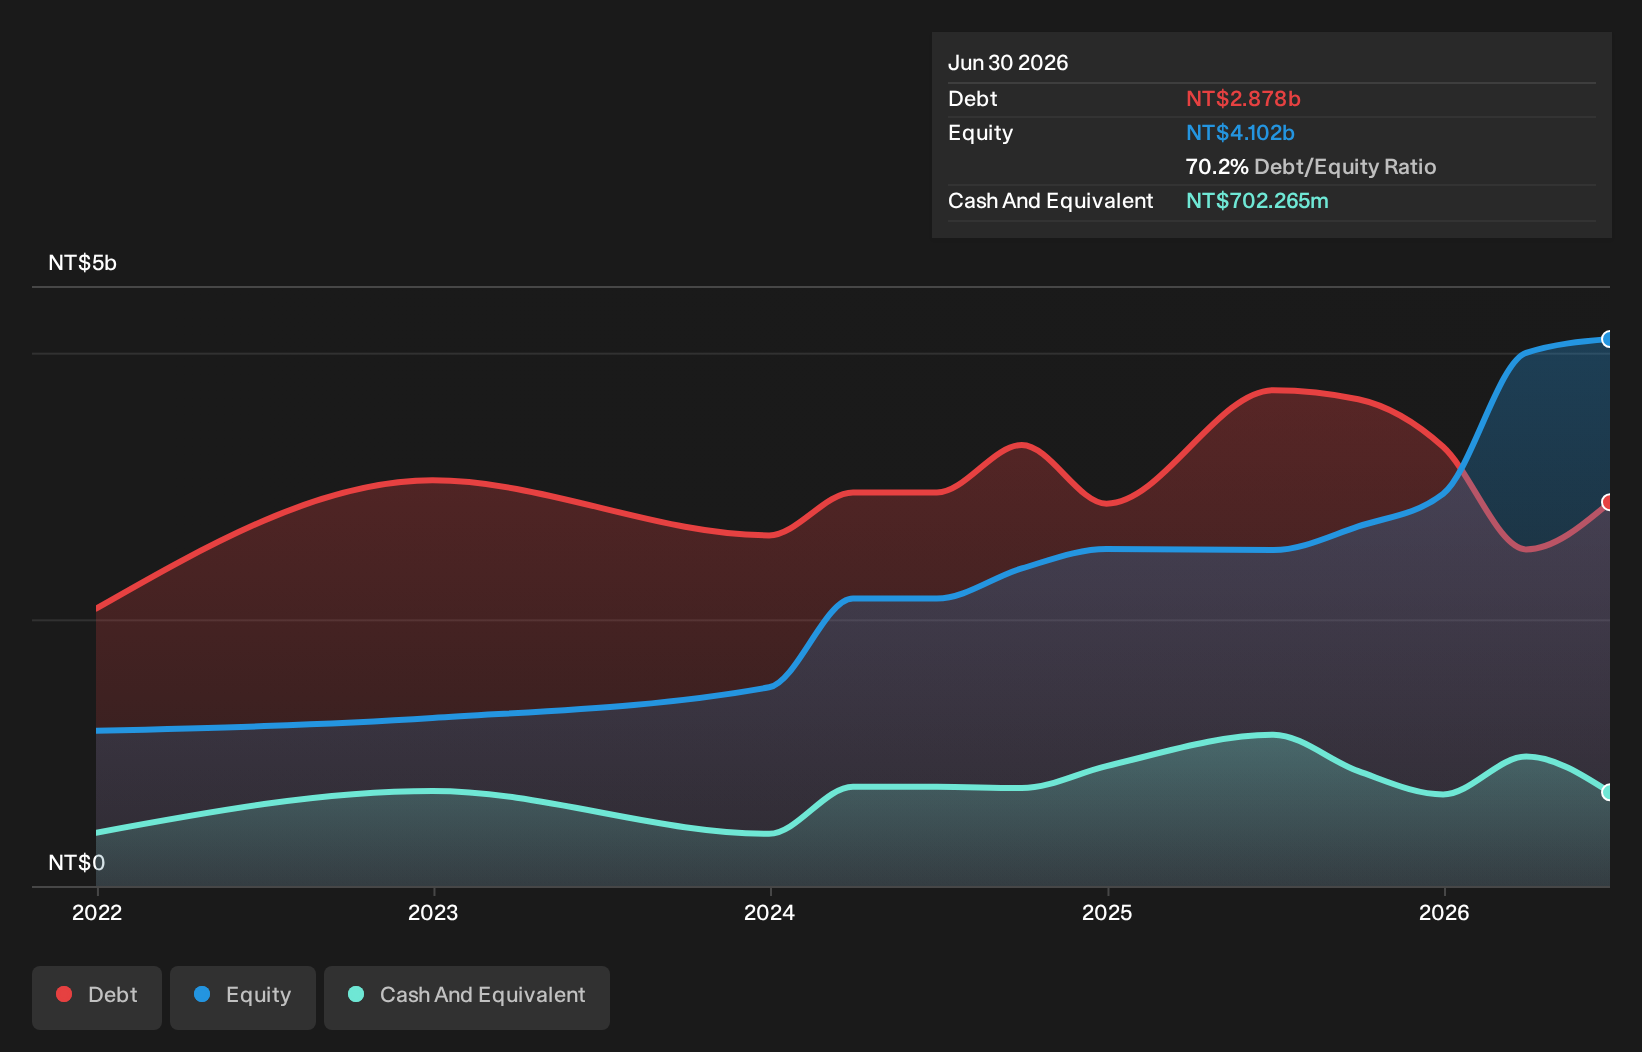
Ta Tun Electric Wire & Cable, a small player in the electrical industry, shows potential despite some challenges. Over the past five years, earnings have grown 33.4% annually, although last year's growth of 7.6% lagged behind the industry's 23.8%. The company's debt to equity ratio stands at a high 53%, yet its interest payments are well-covered by EBIT at a multiple of 21x. Recent results show mixed performance with second-quarter sales dropping to TWD 1,432 million from TWD 1,582 million last year and net income falling to TWD 113 million from TWD 207 million previously.
- Delve into the full analysis health report here for a deeper understanding of Ta Tun Electric Wire & Cable.
Understand Ta Tun Electric Wire & Cable's track record by examining our Past report.
Key Takeaways
- Investigate our full lineup of 122 Asian Undiscovered Gems With Strong Fundamentals right here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com