
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI IPO Boom Puts Equity Underwriter Stocks In Focus
Anthropic’s race toward a potential US$1t IPO, rapid quarterly revenue of US$16.8b and a bold pledge to hand up to 7% of its shares to a Public Benefit Fund are shaking up expectations for who really profits from the next wave of AI. This is where underwriters and equity dealers come in. This article highlights three large quoted investment banks that screens suggest could be most exposed to that story.
The stocks highlighted below are a first look at this theme, and the full screen surfaced 13 more global equity underwriters with equally compelling stories that are not covered in the article. To identify your own highest-conviction ideas in this space, head straight into the Global Equity Underwriters for Mega-Cap Tech IPOs screener.
Investcorp Capital (ADX:ICAP)
Overview: Investcorp Capital is an Abu Dhabi based alternative investment firm that underwrites acquisitions and co invests across corporate, real asset, credit, and strategic capital deals worldwide.
Operations: Investcorp Capital generates US$51 million from its Underwriting segment and US$43 million from Co Investments, indicating a balanced revenue mix.
Market Cap: AED3.1 billion
Investcorp Capital links into this underwriters theme through its Underwriting segment, which supports acquisitions and large syndicated deals that can sit around mega cap tech and AI listings. Forecast double digit earnings and revenue growth add extra interest to that pipeline for IPO focused investors. However, one unresolved pressure on its dividend policy could reshape how much cash ultimately stays in the business.
That dividend pressure is exactly why IPO focused investors scrutinising Investcorp Capital often start with the 2 key rewards and 1 important major warning sign to understand what might reshape future cash returns.

Corporación Actinver S. A. B. de C. V (BMV:ACTINVR B)
Overview: Corporación Actinver S. A. B. de C. V is a Mexican financial group offering banking, advisory, investment and capital markets services.
Operations: Corporación Actinver S. A. B. de C. V generates approximately MX$10.1b of revenue entirely in Mexico, reflecting a domestically focused franchise.
Market Cap: MX$11.3b
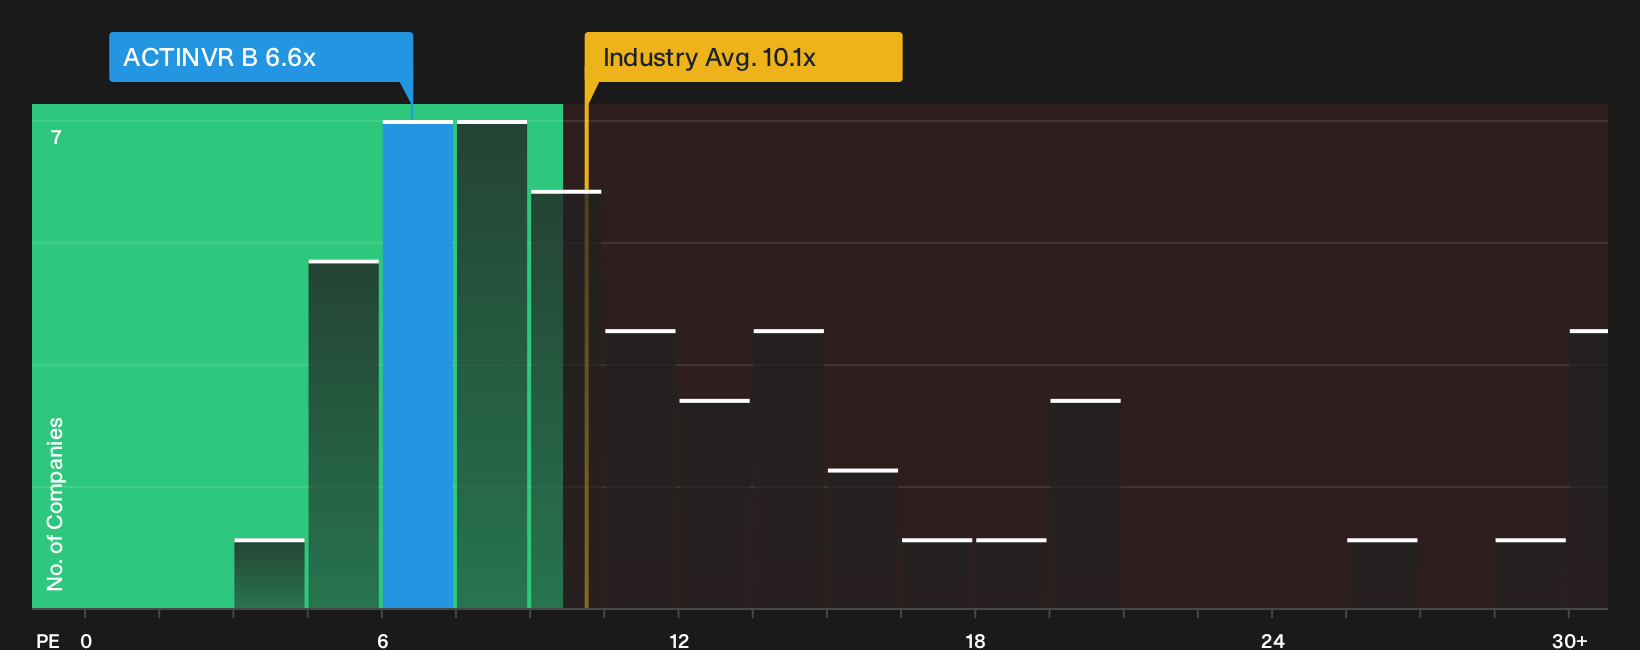
Corporación Actinver S. A. B. de C. V gives you exposure to Mexican equity capital markets, including underwriting and advisory around potential tech listings. The company trades on a P/E of 6.6x with double digit earnings and revenue growth forecasts, set against a funding mix in which 80% comes from external borrowing, so a shift in how that funding base behaves could reshape profitability.
That funding mix is exactly where things could be accelerating or decoupling, so review the Corporación Actinver S. A. B. de C. V financial health report for how Corporación Actinver’s balance sheet could reshape returns.
EFG Holding CompanyE (CASE:HRHO)
Overview: EFG Holding CompanyE is an Egypt based investment bank with ECM, underwriting and brokerage services tied directly to global IPO flows.
Operations: EFG Holding CompanyE earns most income from Egyptian commercial banking at EGP8.4b and brokerage at EGP7.9b, with microfinance and consumer finance above EGP1.8b each.
Market Cap: EGP34.5b
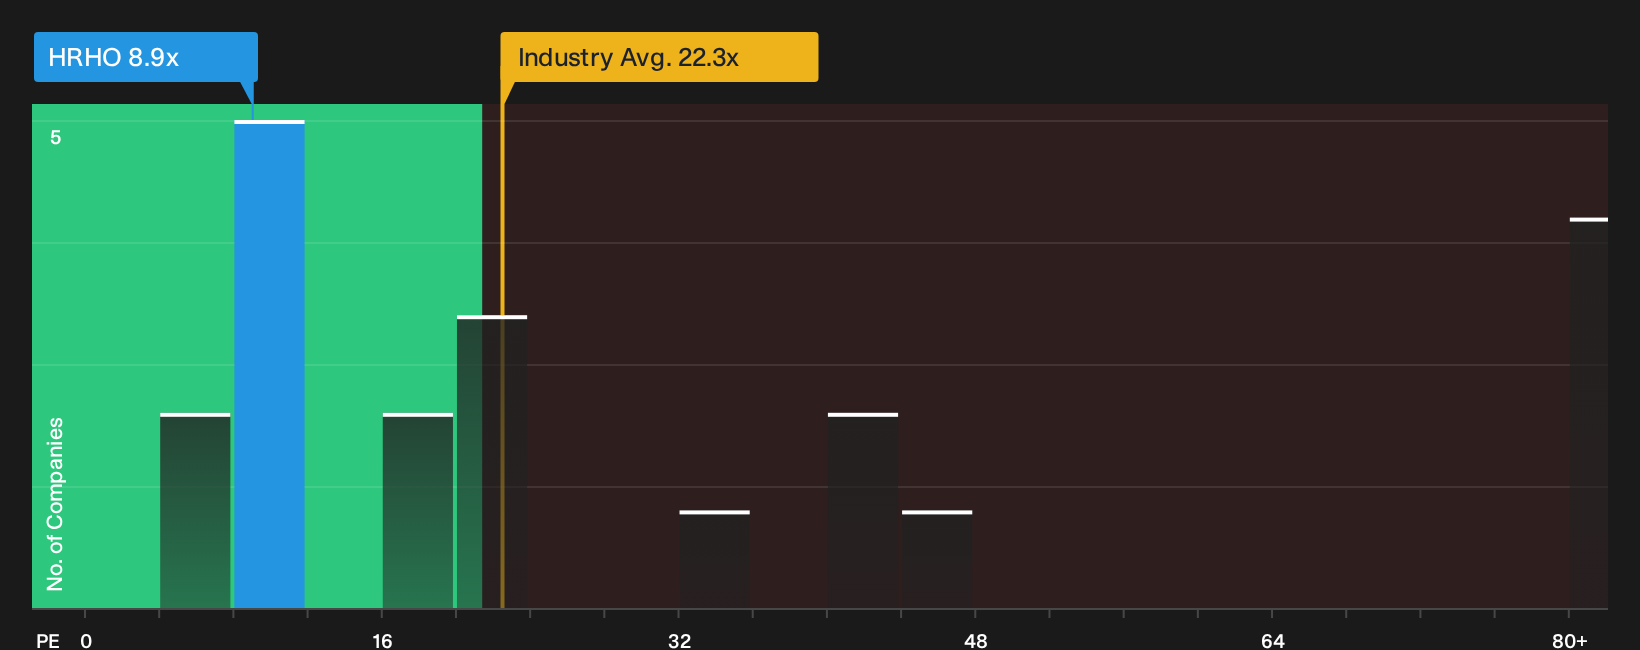
EFG Holding CompanyE offers investors a full service investment bank with equity capital markets, underwriting and brokerage all geared toward IPO fee pools. The stock trades on a P/E of 8.9x against higher market and sector averages. Earnings forecasts and governance updates together illustrate how changes in one previously unseen pressure on funding costs can affect the business.
Those shifting funding costs are exactly why IPO focused investors often head straight for the 5 key rewards and 2 important warning signs (1 is major!) to see what could accelerate or stall EFG Holding CompanyE next.
Seeking Alternatives Before The Crowd
Fresh themes move quickly. Breakout stories gain momentum while they are still under the radar for now. Do not get caught dropping the ball; consider opportunities early.
- Spot early income workhorses and stress test their payout strength using the curated 215 dividend fortresses while yields still reflect mispriced caution.
- Track fast moving enablers of AI demand by scanning the hand picked 55 AI infrastructure stocks before data center momentum fully prices into expectations.
- Hunt disciplined growth stories by filtering for the 232 resilient stocks with low risk scores and focus on businesses where resilience, not hype, drives the next leg of performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com