
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nova (NVMI) Pulls Back As The AI Chip Story Tests Whether The Stock Is A Bargain
Novo (NVMI) has come under pressure recently, with the share price down about 10% over the past month and roughly 26% over the past 3 months, drawing fresh attention to its valuation.
The latest pullback comes after a strong multi year run, with Nova’s share price sliding in recent weeks even as the 3 year total shareholder return is above 200%. This pattern suggests that recent momentum may be fading while longer term holders still sit on substantial gains.
Spot fresh ideas by comparing Nova’s recent pullback with a hand picked group of 20 high quality undiscovered gems that also pair strong fundamentals with long term potential.Nova has pulled back significantly while longer term holders still sit on large gains. Do you lean into the reset now, or wait for a cleaner entry once the valuation picture is clear?
Most Popular Narrative: 38% Undervalued
At a last close of $321.20 versus a widely followed fair value estimate of $515.13, Nova is framed as materially mispriced, with that gap hinging on how its metrology tools track rising chip complexity and capacity builds.
The accelerating complexity of semiconductor devices driven by AI workloads, larger die sizes, advanced nodes and heterogeneous packaging continues to fuel demand for Nova’s advanced metrology solutions across logic, foundry and memory. This demand can support higher revenue and earnings as customers expand metrology intensity. Ongoing global investments in semiconductor manufacturing capacity, including new fabs and regional diversification, are broadening Nova’s customer base and spreading exposure across more geographies. This can support a more resilient revenue mix and smoother operating margins over time.
See why 23 investors see Nova as 38% undervalued.
Result: Fair Value of $515.13 (UNDERVALUED)
Still, the narrative around Nova can shift quickly if competition from China erodes its roughly 30% revenue exposure there, or if sector wide multiple compression deepens valuation pressure.
Find out about the key risks to this Nova narrative.
Another View: Cash Flows Paint A Tougher Picture For Nova
Price targets and earnings based fair values present Nova as materially undervalued, yet the Simply Wall St DCF model points the other way. On that approach, the current share price of $321.20 sits well above an estimated future cash flow value of $145.57, suggesting a stock that screens as expensive rather than cheap.
That gap raises a practical question for you: Do you give more weight to analyst earnings projections and multiples, or to a cash flow model that signals less room for error at today’s price?
Look into how the SWS DCF model arrives at its fair value.
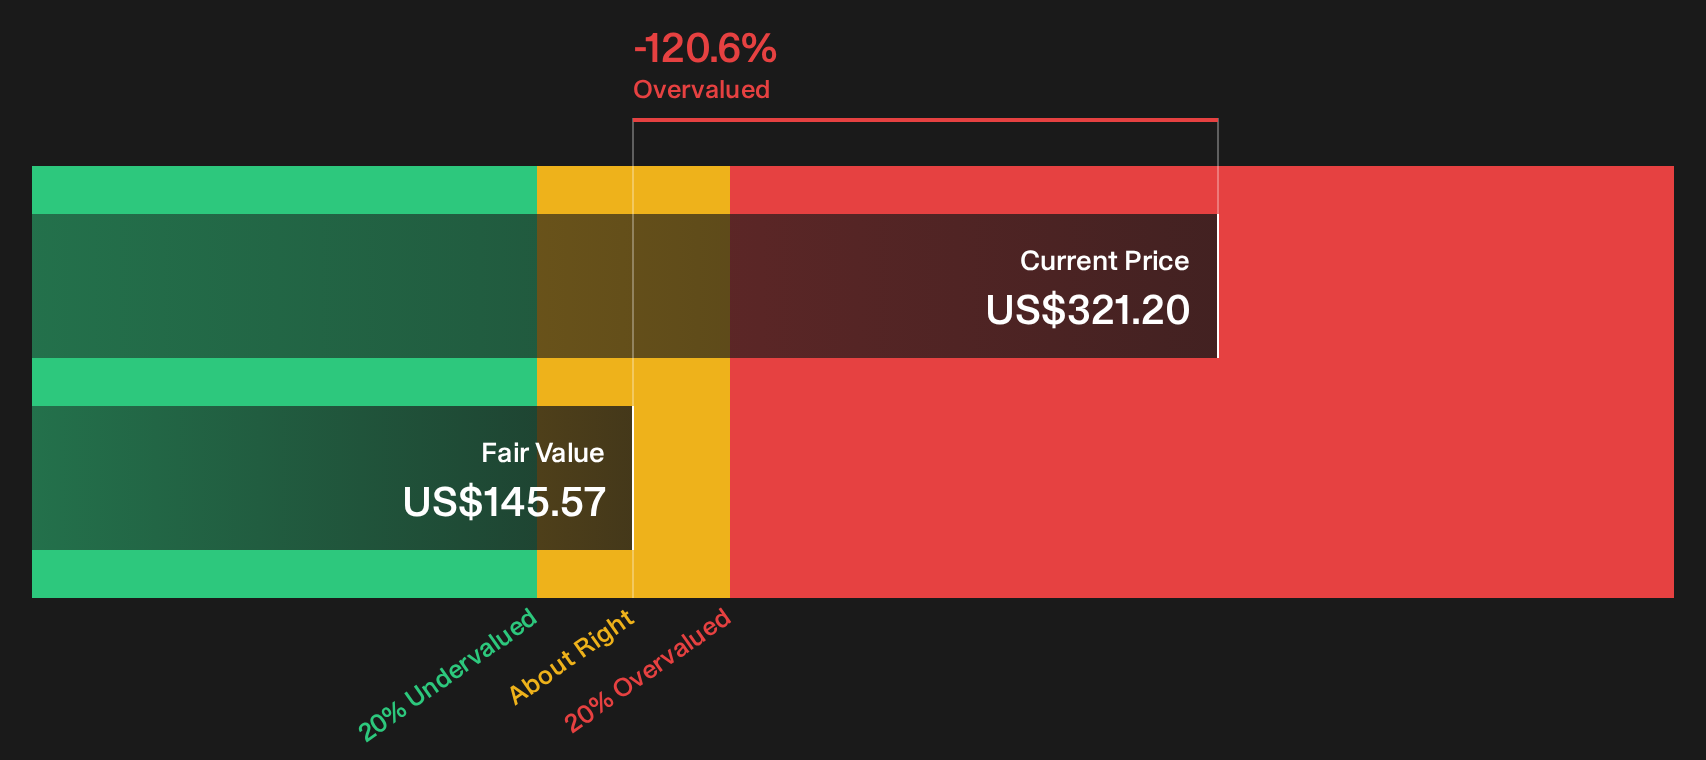
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nova for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of optimism sits alongside clear concerns in the Nova story, which means your view matters right now more than ever. To weigh those trade offs for yourself, start with the 4 key rewards and 1 important warning sign.
Looking for more Nova investment ideas?
If Nova has your attention, do not stop here. Broaden your watchlist now so you are not relying on a single story to drive your next move.
- Target potential bargains that pair quality with attractive pricing by scanning the 33 high quality undervalued stocks for ideas that may complement your Nova thesis.
- Balance out single stock risk and seek steadier compounding by using the 32 resilient stocks with low risk scores to surface businesses with more resilient profiles.
- Hunt for tomorrow's leaders before the crowd notices by running the 20 high quality undiscovered gems and lining them up alongside Nova on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com