
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Push Might Change The Case For Investing In Dropbox Stock (DBX)
- Dropbox is in focus after highlighting its push into AI driven workflows, pointing to strong non GAAP operating margins ahead of its Q3 2026 earnings release, while also flagging higher infrastructure and compute costs tied to these products.
- The business is leaning on AI features and Protect security tools to deepen subscription value and support margins, even as recent research frames Dropbox as trading at a discount to the broader software sector and Argus publishes fresh premium research with an updated outlook.
- We will look at how Dropbox's investment narrative is affected by its AI heavy product focus and the upcoming Q3 2026 update.
Scan beyond Dropbox and see how other AI centric software players are priced by checking our curated list of 33 high quality undervalued stocks in the sector.
Dropbox Investment Narrative Recap
To be comfortable owning Dropbox, you need to buy into a fairly simple idea. The core file sync and share product stays steady, while AI tools and Protect security features lift the value of each subscription enough to justify higher engagement or pricing. The near-term swing factor is whether Q3 2026 shows that AI usage is tracking toward that goal.
The biggest risk is also clear. AI-heavy features require higher infrastructure and compute spending, which has already pressured gross margins. If the upcoming update shows that these costs are scaling faster than AI-related revenue or ARPU, then the current profitability profile and earnings power could look less secure.
Within that context, the renewed focus on AI-driven workflows ahead of Q3 2026 is the announcement that matters most right now. Management has already highlighted strong non-GAAP operating margins and uptake of products like Dash and Protect. The next earnings release is where you see whether usage patterns actually support that story.
For you as a shareholder or prospective investor, the call will likely clarify three things: how much AI usage is contributing to subscription value, how infrastructure and compute costs are tracking, and whether recent cybersecurity issues are contained. Analyst work from Argus and elsewhere can frame expectations, but the operational data from Q3 2026 will be the clearer catalyst.
Dropbox Earnings Setup Through 2029
Dropbox's current analyst narrative leans on relatively steady top line expectations and modestly higher profitability rather than big revenue expansion. Forecasts describe revenue as remaining fairly flat over the next three years, while profit margins are expected to edge up from 17.5% today to 18.2% by 2029. That mix indicates the focus is on squeezing more earnings out of a similar revenue base through cost discipline and product mix, including AI and Protect driven subscriptions.
On the earnings side, the consensus points to profit of US$458.3 million by 2029, compared with US$442.8 million today. That is an increase of about US$15.5 million over the period. The change is incremental rather than dramatic, which matters for how much AI upside might already be reflected in expectations. For investors, the question is whether the upcoming Q3 2026 update supports this glide path or starts to put that earnings step up in question.
Valuation work in the current research ties those numbers together. To line up with the analyst price targets, Dropbox would need to be generating around US$2.5b of revenue and US$458.3 million of earnings in 2029 while trading on a P/E of 16.2x. That multiple would sit below the 29.8x cited for the wider US software group, which implies analysts are using a relatively conservative earnings multiple against a business they expect to keep generating strong cash flow and repurchasing shares.
All of this rests on a simple capital allocation story. Analysts are baking in roughly 7% yearly reduction in the share count for the next three years and using a discount rate of just over 10% to pull those future cash flows back to today. If buybacks keep shrinking the share base, then earnings per share and free cash flow per share can rise even if revenue is flat, which is a key piece of the Dropbox thesis many research notes highlight.
Dropbox's narrative projects US$2.5b revenue and US$458.3 million earnings by 2029. This requires flat yearly revenue performance and an earnings increase of about US$15.5 million from US$442.8 million today.
Uncover why Dropbox's fair value indicates an 11% potential downside to its current price, a premium that may not hold.
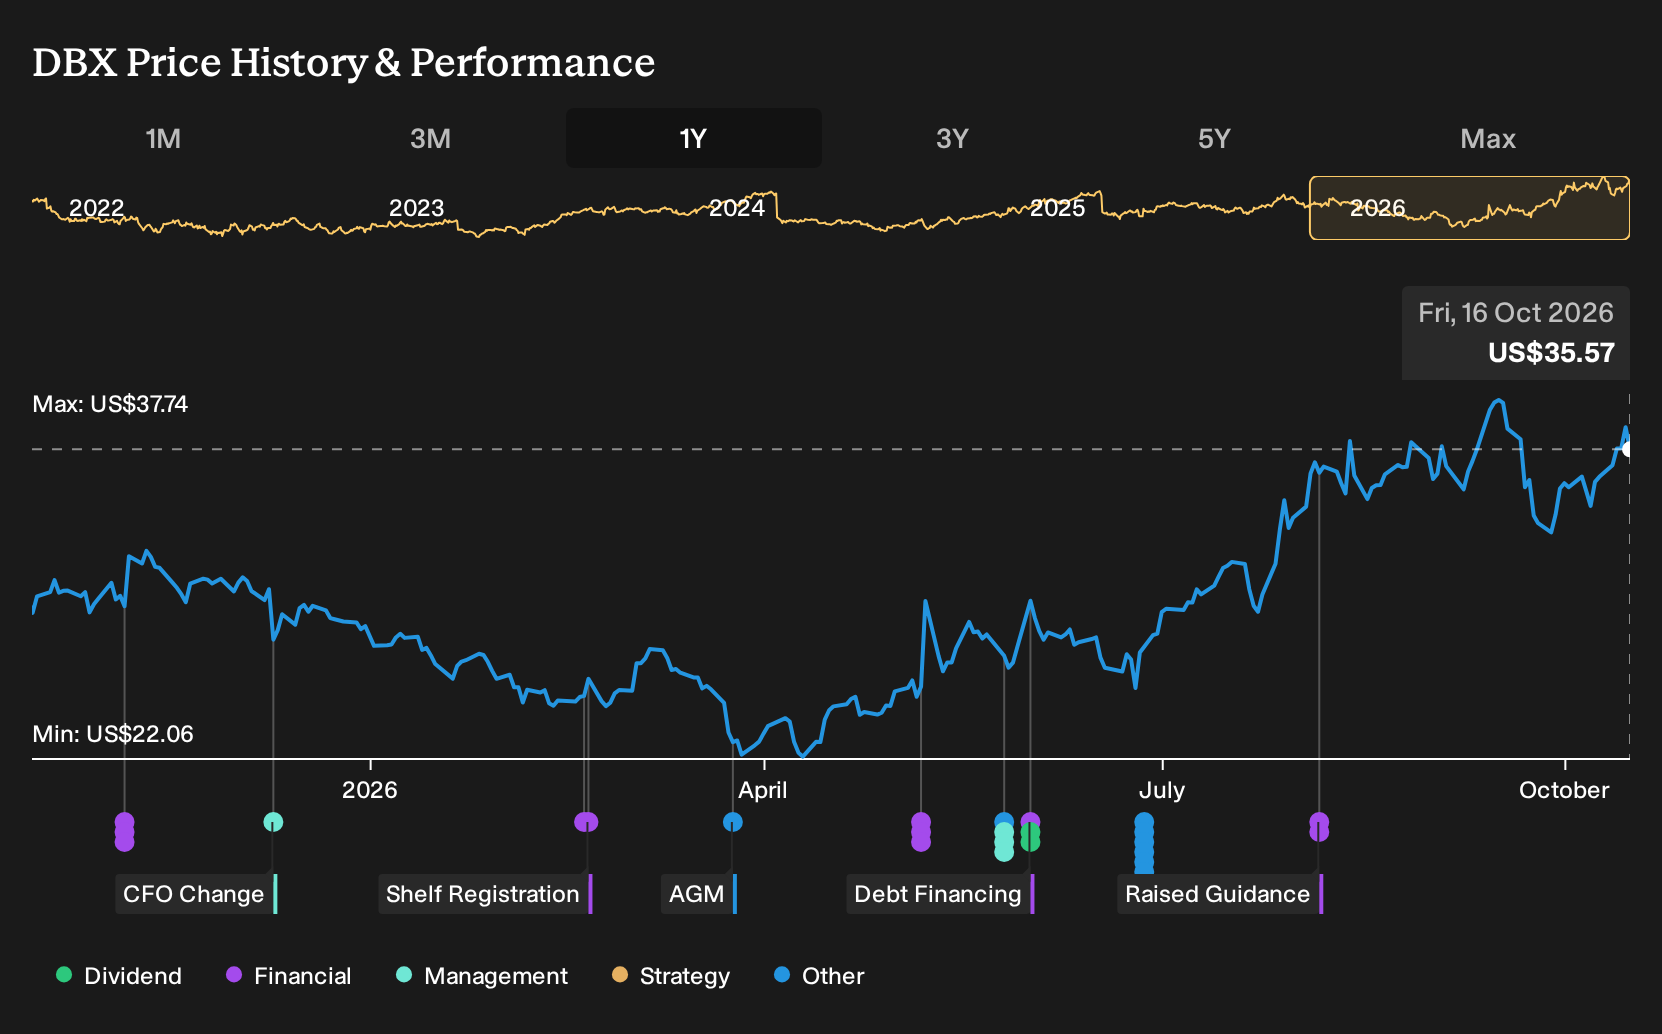
Exploring Other Perspectives
One bearish twist to watch is margin pressure. The lowest Dropbox analysts already pencilled in only US$2.5b of revenue and US$453.1 million of earnings by 2029, on an 11.8x P/E, before this AI rollout news. That group sees AI as a cost risk first, not a growth engine, which shows how far opinions can differ. Use that spread as a prompt to review several viewpoints and then decide which story you think Q3 2026 might move closer to.
Explore 2 other Dropbox fair value estimates, including one that indicates as much as 11% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dropbox research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dropbox. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dropbox's overall financial health at a glance.
Looking for more Dropbox sized investment ideas?
If this Dropbox story has you thinking about where else to put fresh capital to work, a broader scan of the market can help you stress test your thesis and spot other opportunities that fit your risk and income preferences.
- For investors chasing value with quality filters, it can be useful to review a curated group of companies that appear attractively priced on both earnings and balance sheet metrics through the 33 high quality undervalued stocks.
- If capital preservation and balance sheet strength sit high on your checklist, you may want to screen for businesses with low leverage and robust financial cushions using the list of solid balance sheet and fundamentals (25 results).
- For readers who prioritise steady cash returns, one approach is to focus on resilient payers offering yields above 5% by scanning the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com