
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Ibotta Holders Bought Into
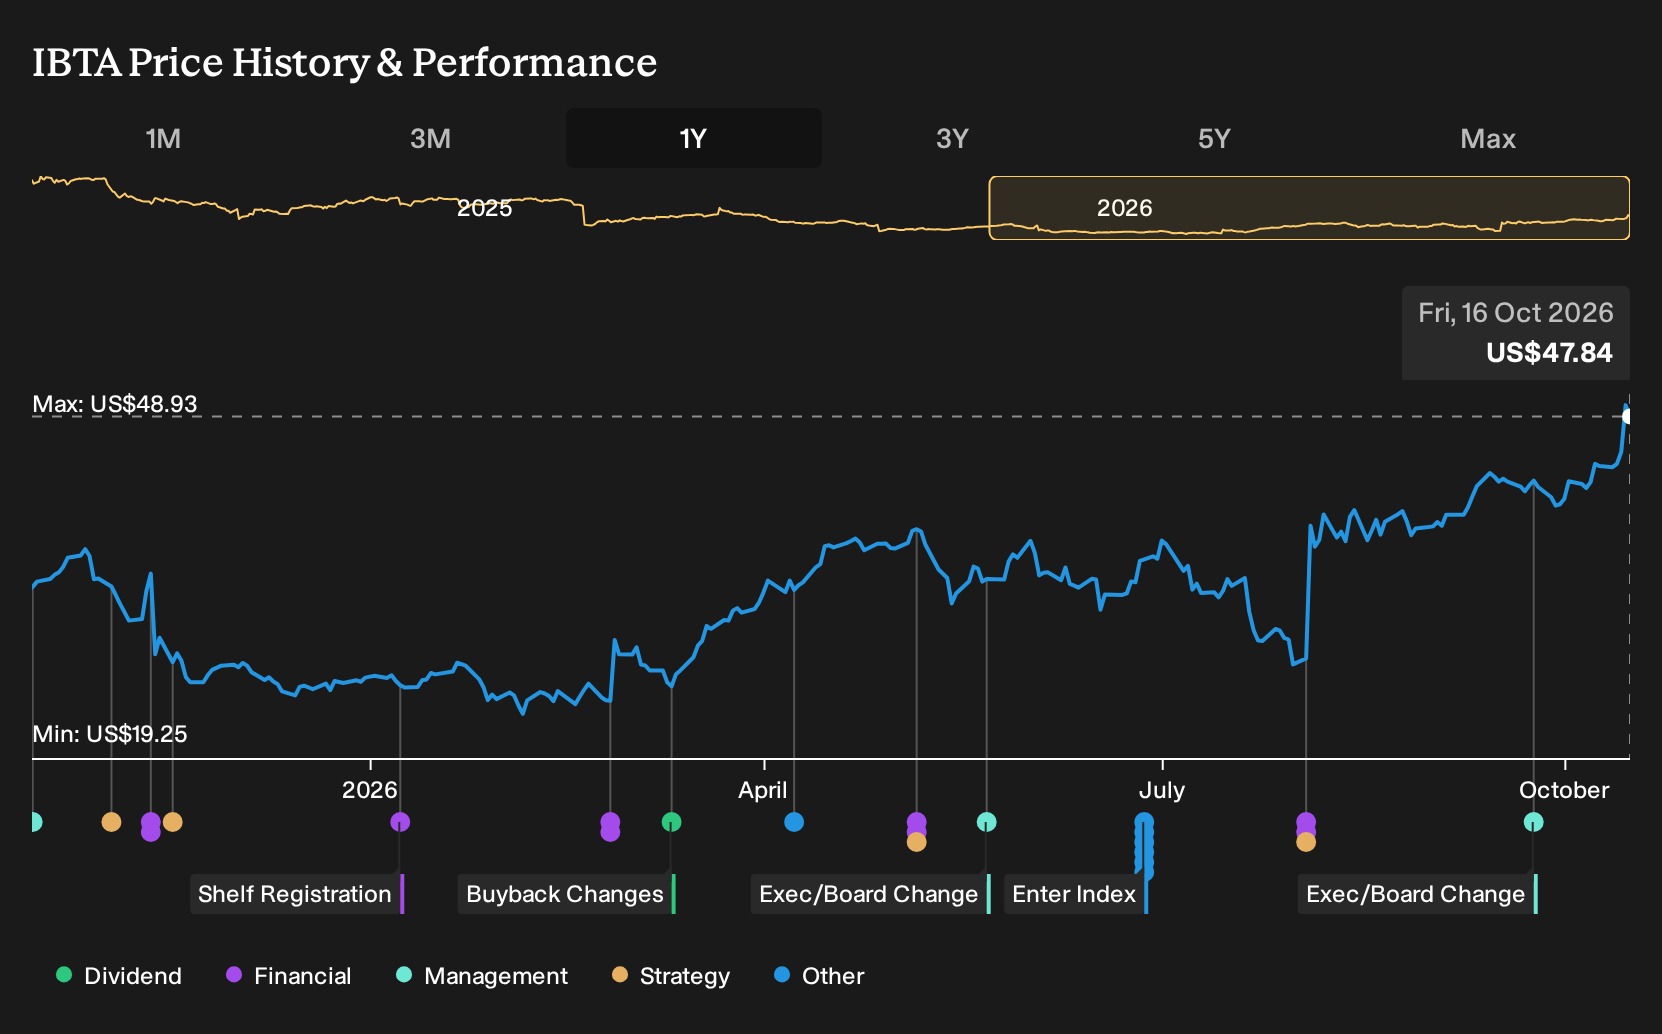
If Ibotta was on your watchlist instead of in your portfolio, the gain may feel like a missed shot. For Ibotta shareholders, the return over the past year was 49.7%, including dividends. That result sits awkwardly beside the latest report, where revenue reached US$88.905m in Q2 2026 while profit flipped into a small loss and net margin declined to 1.4%. If digital coupon growth was supposed to slow as Walmart and Instacart crowded the field, what tipped investors the other way?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Ibotta harder to judge, start where the gap is still open and scan 33 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Ibotta
The shares cost US$31.45 at the start of the period, and Ibotta sat between two sharply different stories about what might happen next.
On the bullish side, one narrative put Fair Value at US$59.63, or 90% above the start price. That view relied on digital couponing staying strong and on Ibotta automating its CPID platform so that revenue kept expanding and margins improved.
The bearish script pointed to Fair Value of US$24, or 24% below the start price. It assumed revenue would decline 2.3%, profit margin would settle at 10.1%, and a future P/E of 18.5x would apply if privacy rules and retailer loyalty programs squeezed the business.
What The Results Changed For The Ibotta Thesis
The clearest fact is the Q2 2026 result. Ibotta reported revenue of US$88.905m, above the Q2 2025 level of US$86.029m. However, profit moved from US$2.49m to a loss of US$1.229m and net margin fell from 2.9% to -1.4%. That combination supports the cautious case, because the profitability gains in the optimistic script remain unproven.
The episode turns on one simple assumption. If the bullish story leans on operating leverage from the CPID platform, it may be more informative to track net margin alongside revenue at each result, rather than watching the share price for confirmation.
What Ibotta’s Price Seems To Assume Now
Today Ibotta trades at US$47.84, and the selected Narrative’s Fair Value sits below that level. The recent 49.7% gain over the past year leaves you paying up for a business still working through a shift away from its direct-to-consumer app.
The Narrative now hinges on whether the Ibotta Performance Network can turn heavier spending and publisher dependence into durable, profitable budget allocation. A buyer at today’s price effectively assumes that transition lands well, so the question is how the cited cost pressure and reliance on large partners square with that bet.
"The numbers imply that Ibotta's share price already discounts a successful transition to third-party publisher driven growth, continued high free cash flow conversion, and margin expansion from current investment levels, leaving limited room for disappointment."
The price and this Narrative do not agree. → Uncover what this Narrative says Ibotta is actually worth
Looking Past Ibotta’s First Step
Ibotta operates where brands demand attention and clear results from every campaign.
Instead of coupons at checkout, advertisers pursue search intent, video watch time and app engagement.
They want one place to plan campaigns, compare formats and understand performance across channels.
One large ecosystem quietly offers that toolkit, from ad placement to measurement, alongside a fast growing cloud arm focused on AI.
If you are mapping Ibotta’s world, that broader ads and cloud hub might be the next stop on your research list.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 27% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com