
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
La-Z-Boy (LZB) Expands Its Store Footprint On A Narrative The Stock May Be Undervalued
La-Z-Boy (LZB) just hit a record 237 company-owned stores across the U.S., including new locations in Georgia, Florida, Tennessee, Mississippi, Massachusetts, Wisconsin, Colorado, and Arizona, expanding its direct-to-consumer footprint.
Despite the fresh store openings, La-Z-Boy’s share price return has fallen 24.7% over the past 90 days and 19.4% year to date, while its 3 year total shareholder return of 10.3% points to longer run gains, even as recent momentum has faded.
Scan for other furniture and home-focused retailers where the market may also be overlooking cash generation potential by reviewing our curated list of 33 high quality undervalued stocks.
La-Z-Boy is adding stores while the share price has moved in the opposite direction. Is the real upside still ahead for investors, or has most of it already played out earlier in the cycle based on where valuation sits today?
Most Popular Narrative: 27% Undervalued
La-Z-Boy finished the last session at $30.07, while the most followed narrative pegs fair value closer to $41. That gap frames the debate around whether recent share price weakness or the underlying cash generation story is doing more of the talking right now.
Expansion of La-Z-Boy company-owned retail stores, with management now targeting about 450 locations and continuing to add roughly 10 new mostly company-owned stores each year, continues to shift sales toward a higher-margin direct channel that can support revenue growth and retail operating margins.
See why 2 investors see La-Z-Boy as 27% undervalued.
Result: Fair Value of $41 (UNDERVALUED)
Still, the La-Z-Boy story depends on friction costs easing and the Joybird turnaround gaining traction. Both of these factors could take longer than bullish narratives assume.
Find out about the key risks to this La-Z-Boy narrative.
Another View: La-Z-Boy Through The P/E Lens
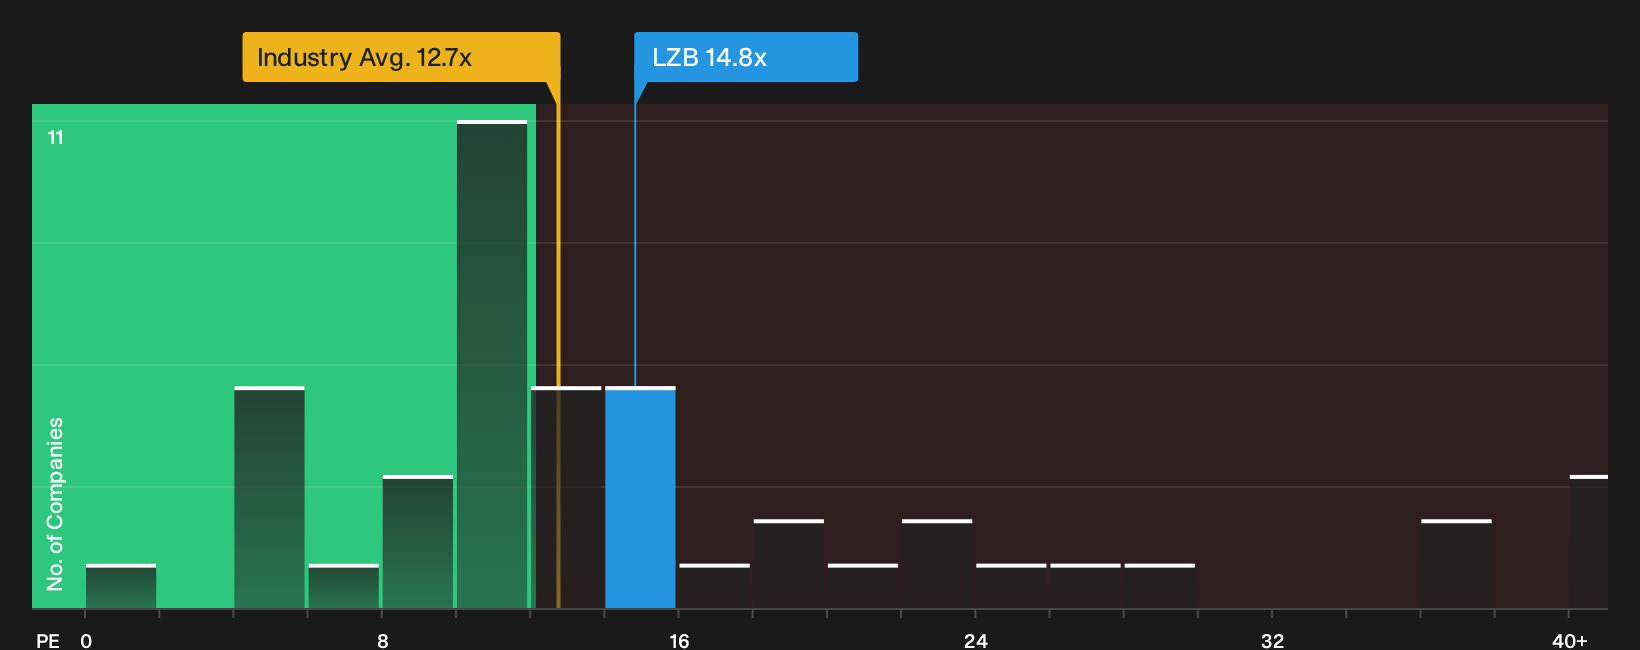
The cash flow story points to La-Z-Boy trading below one estimate of fair value, yet the earnings multiple tells a different story. At about 14.8x P/E, the shares are described as more expensive than both peers at 13.1x and the US Consumer Durables group at 12.7x, even though the fair ratio is 16.4x. Is this a margin-of-safety opportunity, or are you paying up for forecast growth that may not fully arrive?
To pressure test that earnings-based view against the current price action and analyst targets, review the detailed valuation breakdown in our numbers focused comparison, starting with the See what the numbers say about this price — find out in our valuation breakdown..
For a quick visual check on how La-Z-Boy lines up against the wider sector on earnings, take a look at the latest relative valuation snapshot here:
Next Steps
Sentiment in the La-Z-Boy story is clearly split, with both concerns and bright spots on the table. Move quickly, look through the numbers and pressure test the 2 key rewards and 3 important warning signs.
Looking for more La-Z-Boy style investment ideas?
If you only stop at La-Z-Boy, you risk missing other opportunities that fit your style, your risk comfort, and your return expectations across the market.
- Target potential mispricings by running through a curated 33 high quality undervalued stocks that highlights companies with strong fundamentals trading below one estimate of fair value.
- Focus on income potential by scanning a hand picked set of 8 dividend fortresses that combine higher yields with disciplined payout histories.
- Dial down volatility by zeroing in on a 32 resilient stocks with low risk scores that surfaces businesses with sturdier balance sheets and calmer trading profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com