
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Comes Next For EcoRodovias After A 77% Gain
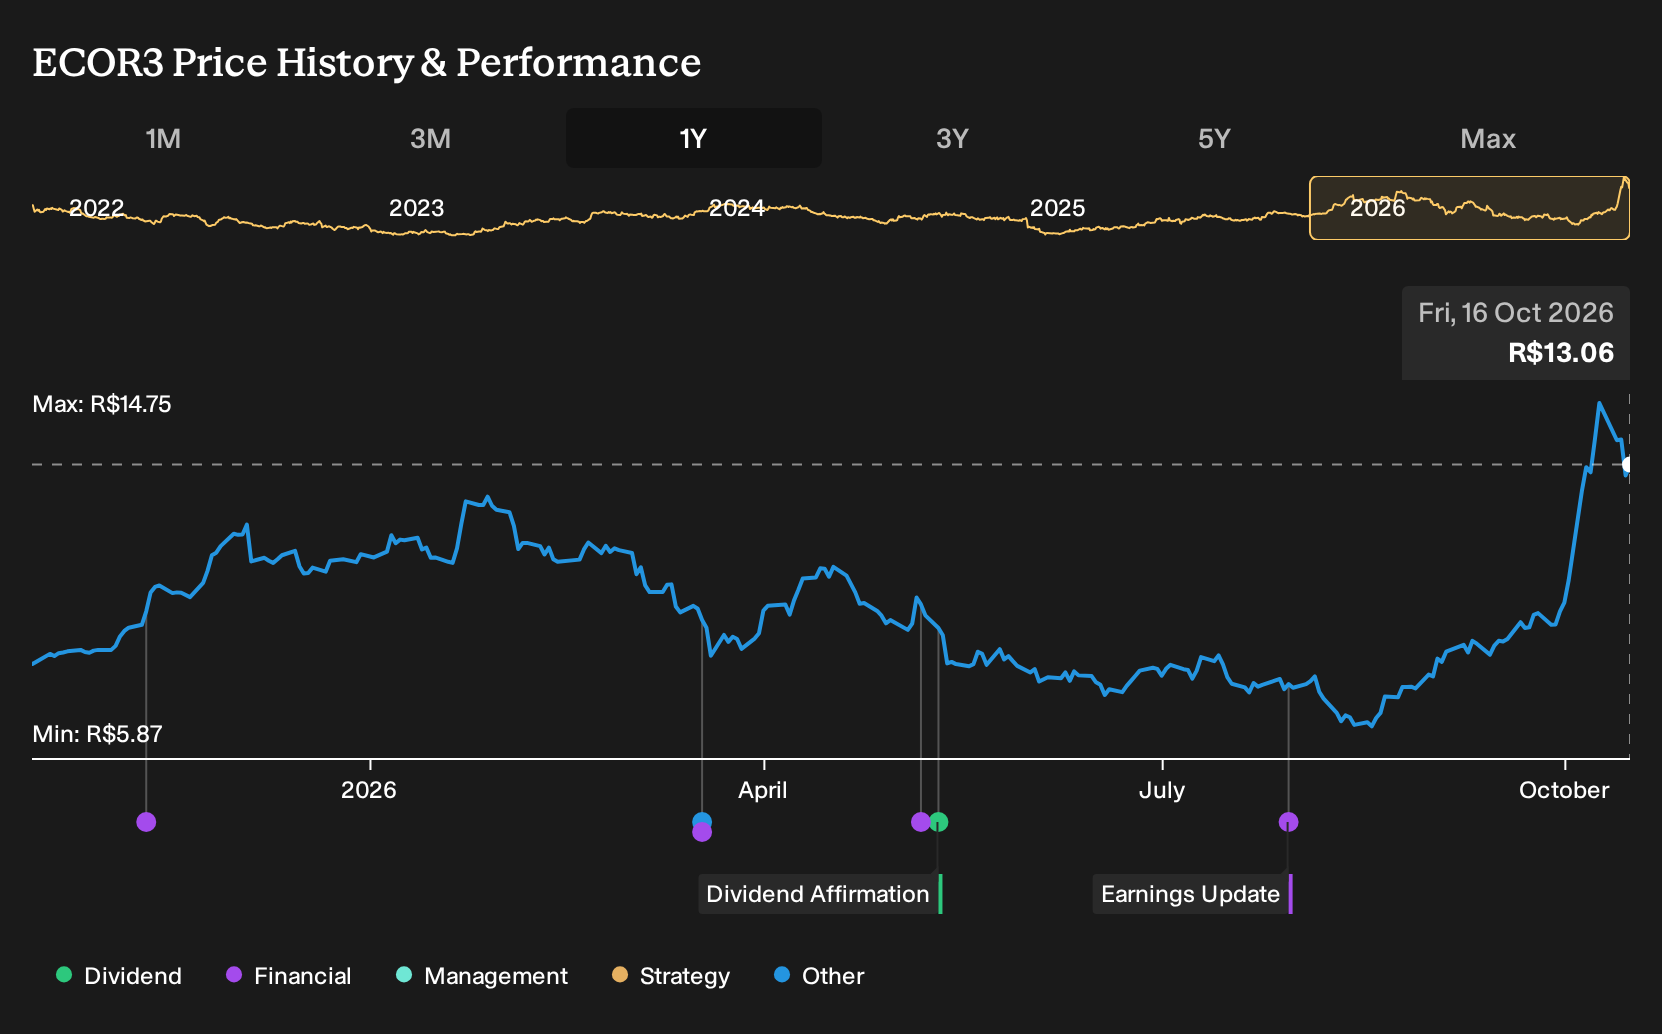
If EcoRodovias Infraestrutura e Logística was on your watchlist instead of in your portfolio, the move over the past year may feel expensive in hindsight. Investors who held EcoRodovias Infraestrutura e Logística over the past year are up 77.1%, including dividends. That surge came while analysts were split between urbanization driven traffic growth and pressure from digital shifts and leverage. Which of those competing views about traffic volumes on Brazil’s toll roads looked more convincing before the payoff arrived?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind EcoRodovias Infraestrutura e Logística. Zero in on 189 high quality undervalued stocks for companies trading below our estimates.
What EcoRodovias Investors Were Really Arguing About
The shares cost R$7.58 at the start of the period, and anyone looking at EcoRodovias Infraestrutura e Logística then had to decide which of two very different stories to trust.
On the bullish side, the Brazil Urbanization And Tech Adoption Will Modernize Toll Roads view put Fair Value at R$9.49, 25% above the start price. That case leaned on rising traffic from urbanization, more concession wins such as Ecovias 101, and heavy use of digital tolling to support higher margins.
The opposing Regulatory Pressure And Digital Shifts Will Undermine Highway Revenues narrative set Fair Value at R$7, 8% below the start price. Bears focused on traffic risk from digitalization and remote work, together with leverage expected to peak at 4.5 times EBITDA as a key financial pressure point for EcoRodovias.
What The Results Changed For The EcoRodovias Argument
The clearest update came from Q2 2026 numbers. EcoRodovias Infraestrutura e Logística reported revenue of R$2,955.338 million versus R$2,718.137 million a year earlier, which leans toward the urbanization driven bullish story. Net income excluding extra items dropped to R$21.207 million from R$204.459 million and net margin slipped from 7.5% to 0.7%, which challenged the profitability part of that optimistic case. Overall the evidence cut both ways.
The takeaway is simple. When a thesis leans on future margin strength, as EcoRodovias did, you need to track net margin as closely as traffic or top line and test whether earnings quality is really moving in the same direction as revenue.
What EcoRodovias’ Current Price Already Assumes
EcoRodovias Infraestrutura e Logística now trades at R$13.06 after a 77.1% gain over the past year. The selected Narrative’s Fair Value sits below that price, framing today’s level as one where expectations already bake in solid execution rather than a clear bargain.
This Narrative focuses on pressure from financing costs, concession renewals and the timing of regulatory rebalancing. A buyer at today’s price would need to believe that large, debt funded CapEx and portfolio renewal convert into stable, cash generative concessions that comfortably cover interest and still support recurring earnings.
"The main factor that needs to work in the company’s favor is EcoRodovias Infraestrutura e Logística successfully converting its large, debt-funded CapEx program and portfolio renewal into sustained, cash-generative concessions that support current leverage and funding commitments without placing additional strain on recurring earnings."
The price and this Narrative do not agree. → Uncover what this Narrative says EcoRodovias Infraestrutura e Logística is actually worth
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 43% below our estimate - targets being the independent planning and information layer across rival treatment machines.
- Company 2 - 33% below our estimate - shifts from a legacy state-owned origin toward a broader packaged nutrition and beverage platform.
- Company 3 - 45% below our estimate - rides hyperscaler spending as server power and liquid cooling move into denser data halls.
That is three of the list. See the full list of 203 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com