
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 ASX Penny Stocks Under A$900M Market Cap To Consider
Australian shares are poised to edge lower after Wall Street's recent downturn, with tech sell-offs and rising energy costs influencing global markets. Despite these challenges, investors may find opportunities in sectors moving towards defensive positions. Penny stocks, while an older term, continue to offer potential value for those interested in smaller or newer companies with strong financials. These stocks can provide a mix of growth and stability that larger firms might not always deliver.
Let's explore several standout options from the results in the screener.
Austco Healthcare (ASX:AHC)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Austco Healthcare Limited develops, manufactures, services, supplies, and distributes healthcare communications equipment and software across Australia, New Zealand, Asia, Europe, and North America with a market capitalization of A$93.69 million.
Operations: The company's revenue is derived from healthcare communications equipment and software, with A$55.76 million from Australia/New Zealand, A$43.39 million from North America, A$6.71 million from Asia, and A$4.37 million from Europe.
Market Cap: A$93.69M
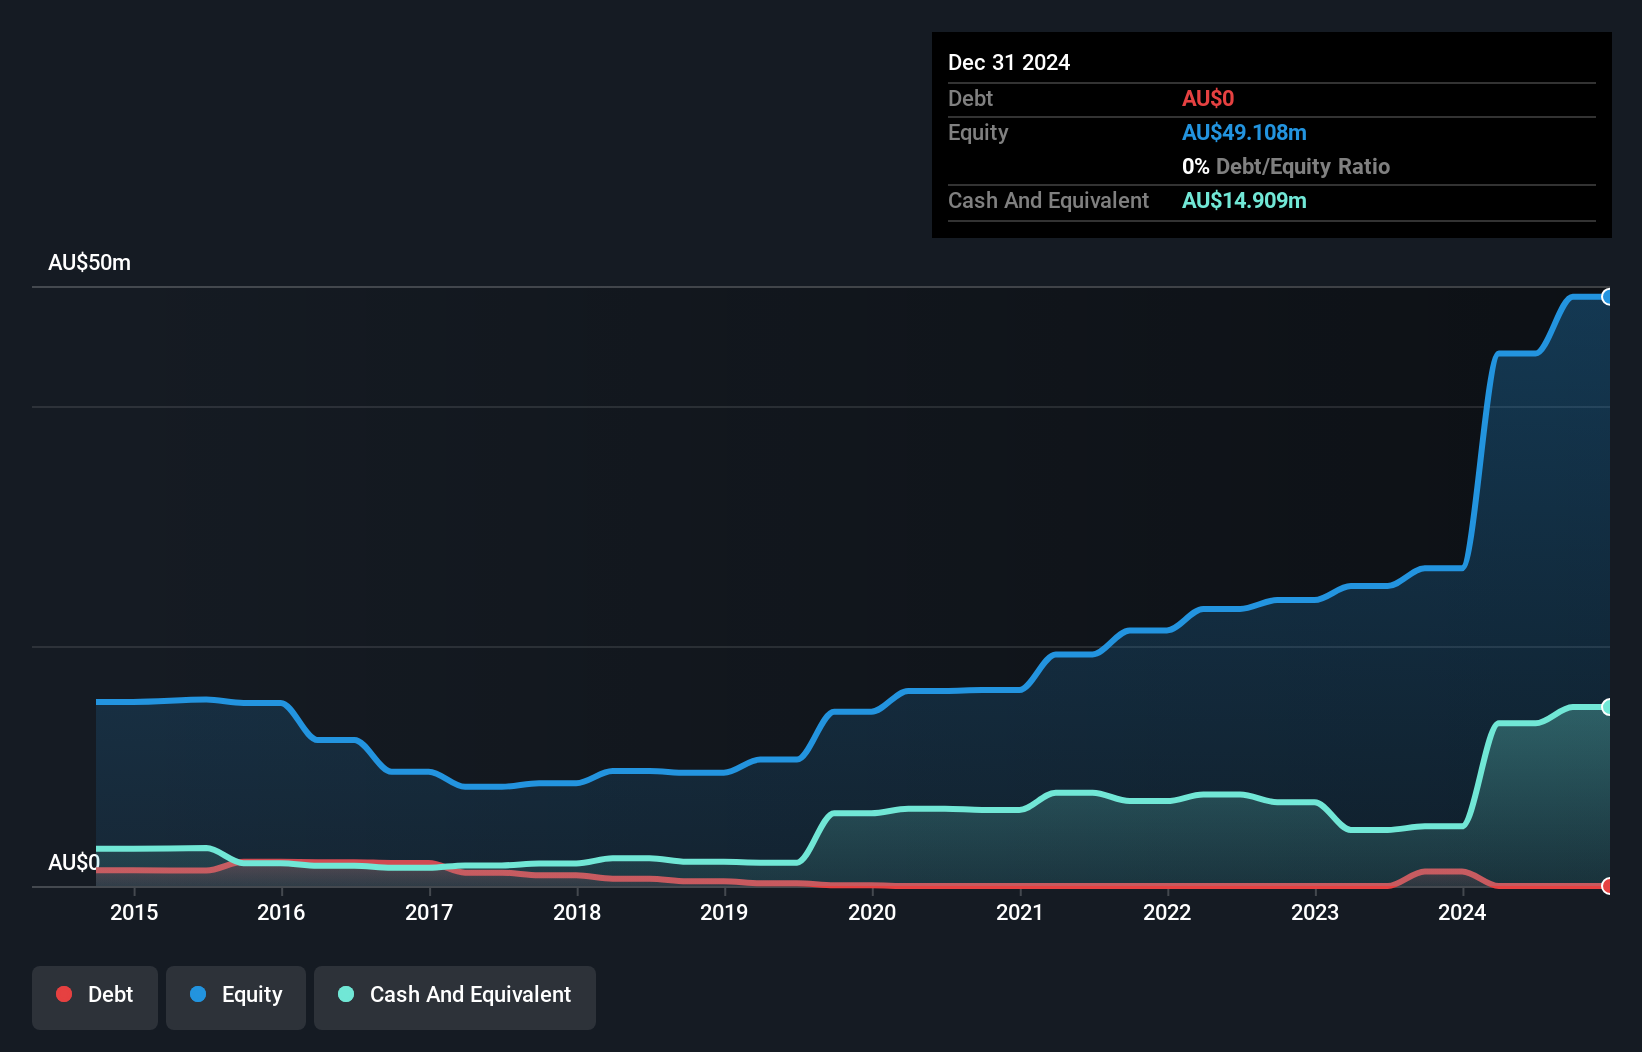
Austco Healthcare Limited, with a market capitalization of A$93.69 million, shows promising potential in the penny stock segment. The company reported significant revenue growth to A$94.24 million for the year ending June 30, 2026, up from A$81.41 million previously, indicating robust demand for its healthcare communications solutions across key markets like Australia/New Zealand and North America. Earnings grew by 51.8% over the past year and net profit margins improved to 9.6%. Austco is debt-free with strong short-term asset coverage over liabilities and no shareholder dilution in the past year, enhancing its financial stability profile for investors seeking value opportunities.
- Dive into the specifics of Austco Healthcare here with our thorough balance sheet health report.
- Examine Austco Healthcare's earnings growth report to understand how analysts expect it to perform.
Nanosonics (ASX:NAN)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Nanosonics Limited manufactures and commercializes infection control and decontamination products and related technologies across various regions including Australia, North America, Europe, the United Kingdom, the Middle East, and Asia Pacific with a market cap of A$854.89 million.
Operations: The company generates revenue from its Healthcare Equipment segment, which amounted to A$203.89 million.
Market Cap: A$854.89M
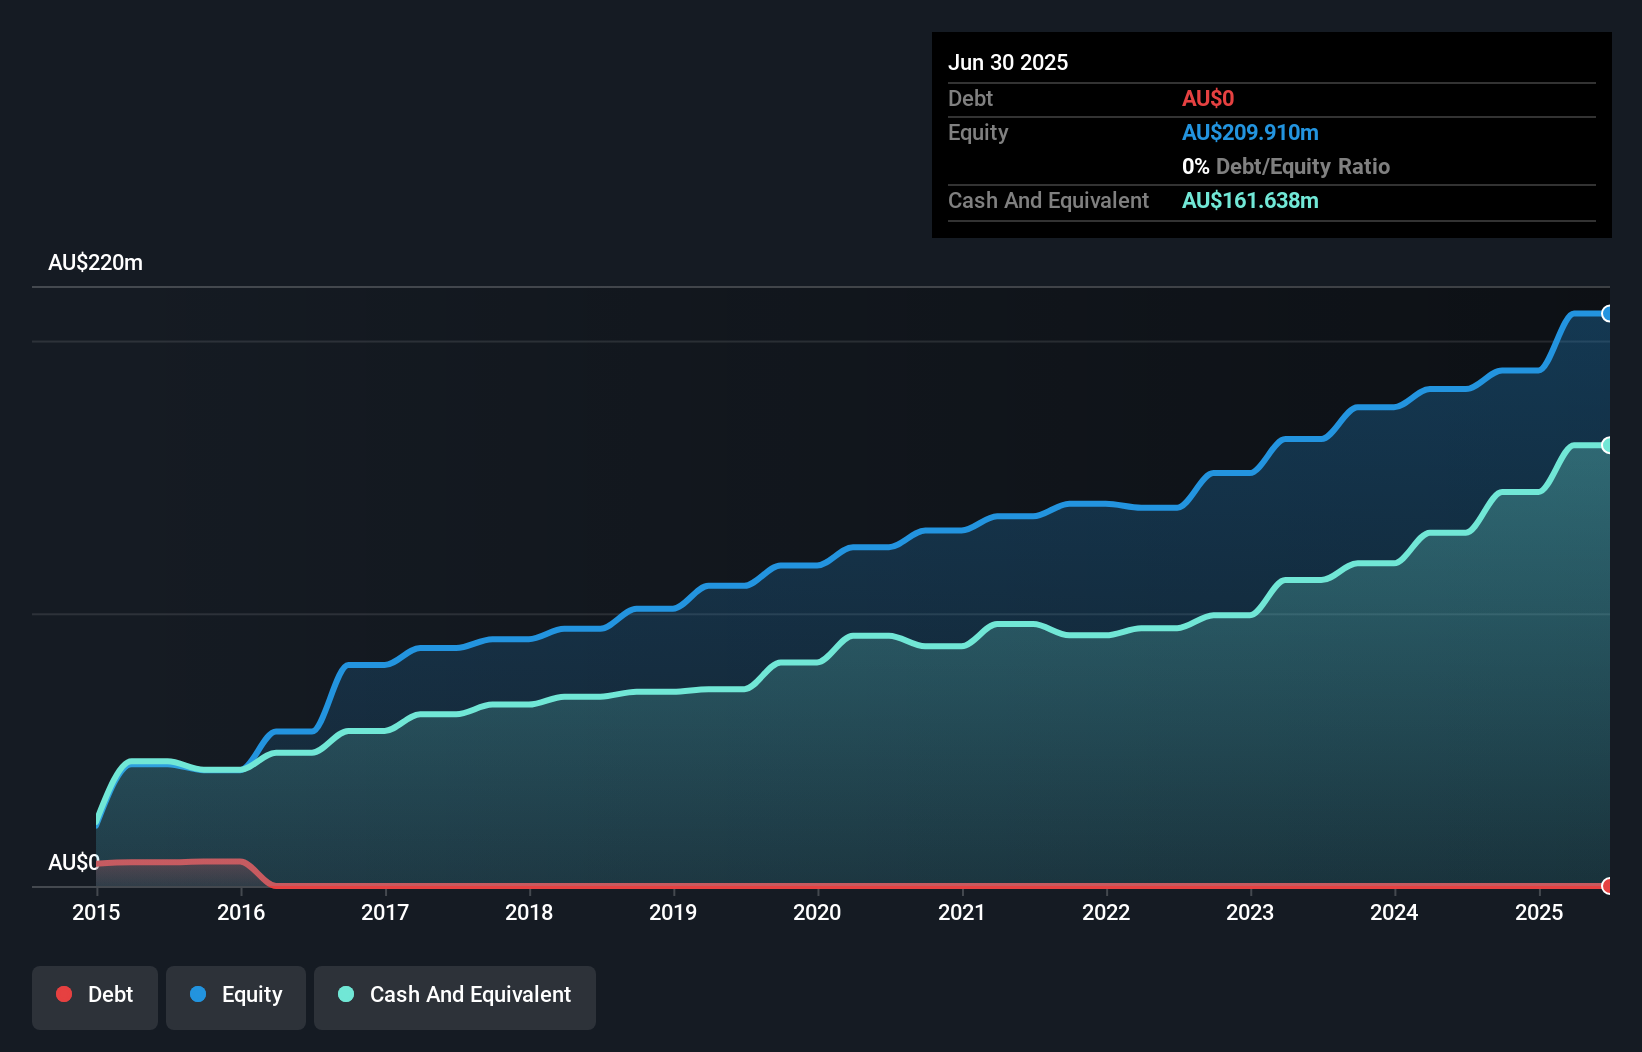
Nanosonics Limited, with a market capitalization of A$854.89 million, demonstrates stability in the penny stock arena through consistent revenue generation and strategic financial management. The company reported sales of A$203.89 million for the fiscal year ending June 30, 2026, with net income at A$17.84 million despite a decline from the previous year. Nanosonics is debt-free and maintains strong asset coverage over liabilities, which supports its capital management strategy including a share buyback program worth up to $40 million valid until 2027. However, recent negative earnings growth poses challenges against industry benchmarks and past performance trends.
- Jump into the full analysis health report here for a deeper understanding of Nanosonics.
- Evaluate Nanosonics' prospects by accessing our earnings growth report.
Oneview Healthcare (ASX:ONE)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Oneview Healthcare PLC develops and sells software services for the healthcare sector across Ireland, the United States, Australia, the Middle East, and Asia with a market cap of A$117.53 million.
Operations: The company generates revenue from its Patient Engagement Solution for the Healthcare Sector, totaling €11.14 million.
Market Cap: A$117.53M
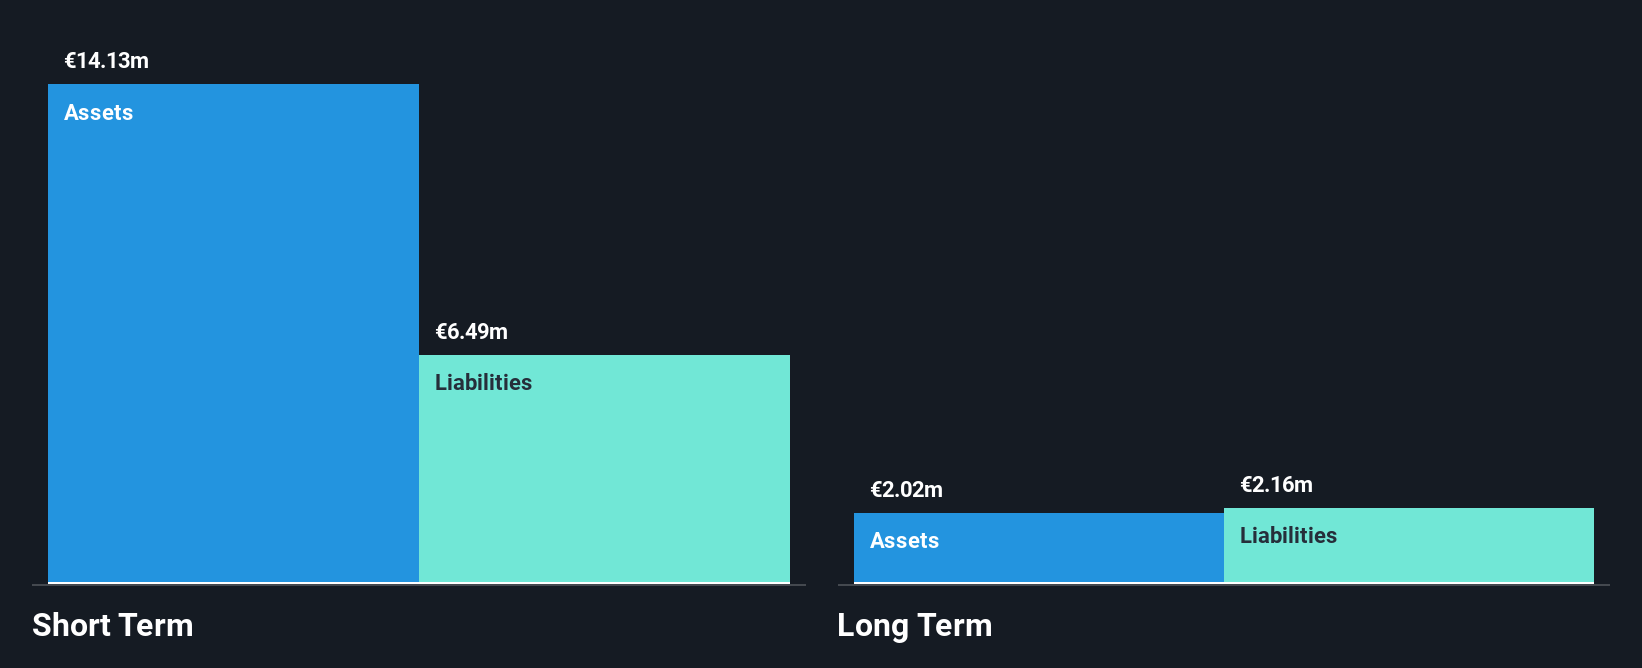
Oneview Healthcare PLC, with a market cap of A$117.53 million, operates in the healthcare software sector but faces challenges typical of penny stocks. The company reported half-year sales of €5.49 million, a decrease from the previous year, and remains unprofitable with net losses narrowing slightly to €5.49 million. Despite being debt-free and having short-term assets exceeding liabilities, Oneview's negative return on equity and less than one year of cash runway highlight financial vulnerabilities. Recent removal from the S&P/ASX All Ordinaries Index underscores its volatile position within the market landscape as it seeks to stabilize earnings growth forecasts at 75.84% annually.
- Click to explore a detailed breakdown of our findings in Oneview Healthcare's financial health report.
- Gain insights into Oneview Healthcare's future direction by reviewing our growth report.
Next Steps
- Get an in-depth perspective on all 414 ASX Penny Stocks by using our screener here.
- Contemplating Other Strategies? Uncover 24 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com