
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dicker Data (ASX:DDR) And Its Dell AI Factory Deal As Valuation Questions Grow
Dicker Data (ASX:DDR) is drawing attention after teaming up with Dell to deliver what is described as Australia’s first AI factory, highlighting a push into AI infrastructure and related solutions across Australia and New Zealand.
Recent trading reflects that shift in focus. Dicker Data’s share price has climbed 29.7% over the past 90 days and its year to date share price return of 52.6% sits alongside a 1 year total shareholder return of 54.8%. This suggests momentum has been building into news like the Dell AI factory partnership rather than fading away.
Scan other companies riding the same AI infrastructure wave as Dicker Data by reviewing the hand picked 55 AI infrastructure stocks, which are trying to position for similar demand across the region.
The share price now sits only about 4% below the A$16.13 analyst target, while intrinsic value estimates point to a premium. Is the recent AI driven surge already pricing Dicker Data ahead of itself, or is the caution misplaced?
Most Popular Narrative: 2% Undervalued
The most followed narrative currently places Dicker Data’s fair value at A$15.86, just above the A$15.49 last close. This frames a tight valuation gap and puts the focus squarely on whether its AI and cybersecurity initiatives can justify that premium.
Fast-growing cybersecurity demand is translating into significant recurring software revenue growth (23% YoY in 1H FY25), now bolstered by the recent CrowdStrike partnership. This is expected to support sustained double-digit growth in high-margin software and security segments as regulatory and threat landscapes intensify and customer requirements become more sophisticated.
See why 42 investors see Dicker Data as 2% undervalued.
Result: Fair Value of A$15.86 (UNDERVALUED)
Still, the Dicker Data story could change quickly if large AI infrastructure deals prove one off, or if New Zealand growth remains constrained and margins stay under pressure.
Find out about the key risks to this Dicker Data narrative.
Another View On Dicker Data’s Valuation
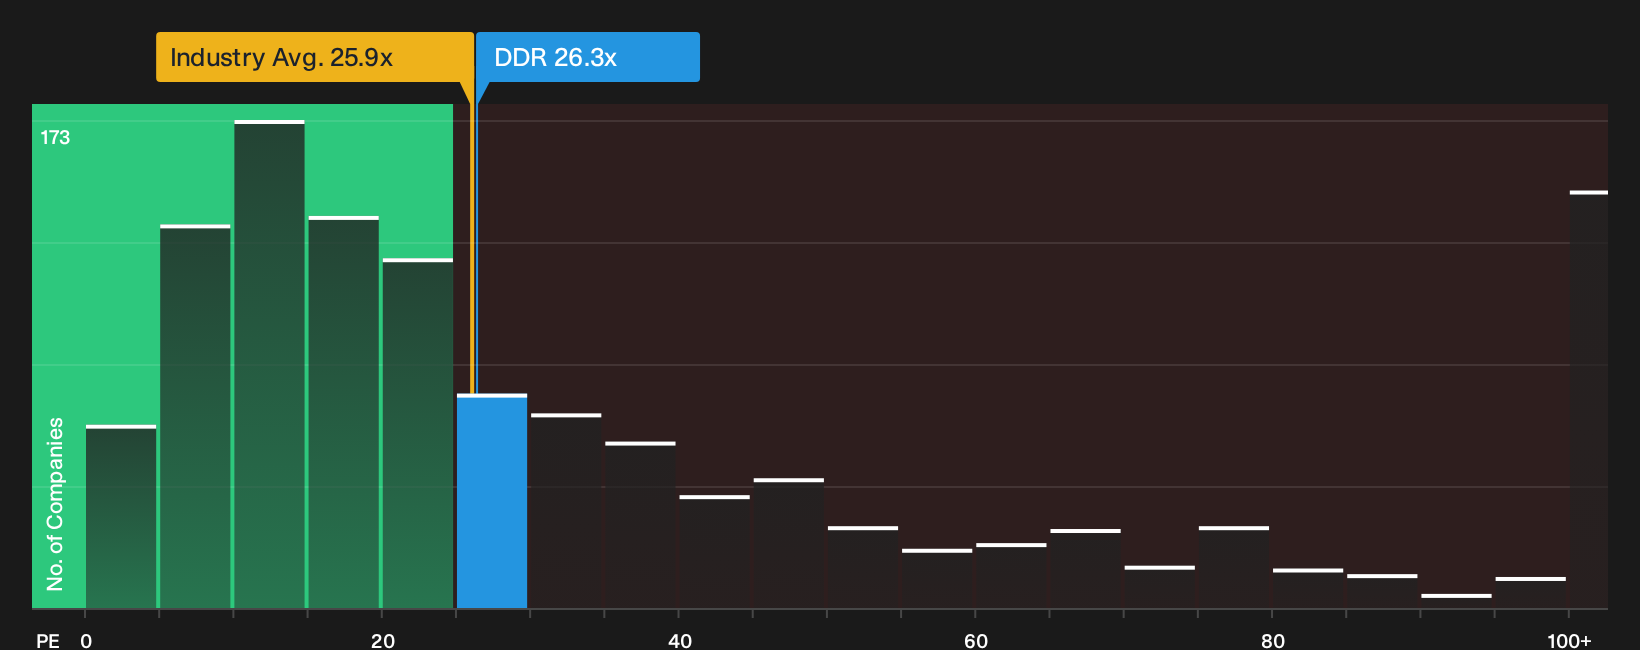
A different lens on Dicker Data comes from its P/E ratio. The stock trades on 26.3x earnings, which is slightly higher than both the Global Electronic industry at 25.9x and the peer average at 25.6x, yet still below an estimated fair ratio of 33.8x. That mix of a mild premium now and potential room to move toward the fair ratio raises a simple question: Are you comfortable paying more today on the chance the market edges closer to that higher multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Dicker Data’s AI, cybersecurity and valuation story make this a moment to look closer and move with intent. Take a few minutes to review both sides of the ledger and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Dicker Data?
If Dicker Data has sharpened your interest in tech and infrastructure themes, broaden your watchlist with a few targeted stock ideas that match different priorities.
- Hunt for mispriced quality by checking companies on the 5 high quality undervalued stocks that combine solid fundamentals with prices that lag their underlying metrics.
- Build a steadier income stream by reviewing dividend payers in the 4 dividend fortresses that focus on higher yields with an emphasis on resilience.
- Sleep easier at night by scanning the 6 resilient stocks with low risk scores to find businesses screened for stronger balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com