
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BNP Paribas Stock And French Bond Stress What Investors Are Watching
French streets are on fire and bond traders are watching every headline. When protests and politics start to reshape borrowing costs for a country as large as France, pricing in European financials can move quickly and sometimes bluntly. For investors, that can create mispricings, not just pain. This article walks through 3 stocks from our French sovereign risk screener that appear positioned to benefit from this turmoil.
The 3 stocks below are just a starting sample, since the full French sovereign risk screen surfaced 40 more European financials with equally compelling stories that are not covered here.
If you want to identify and analyze the broader opportunity set tied to French government bond moves, head straight into the European Financials Exposed to French Sovereign Risk screener.
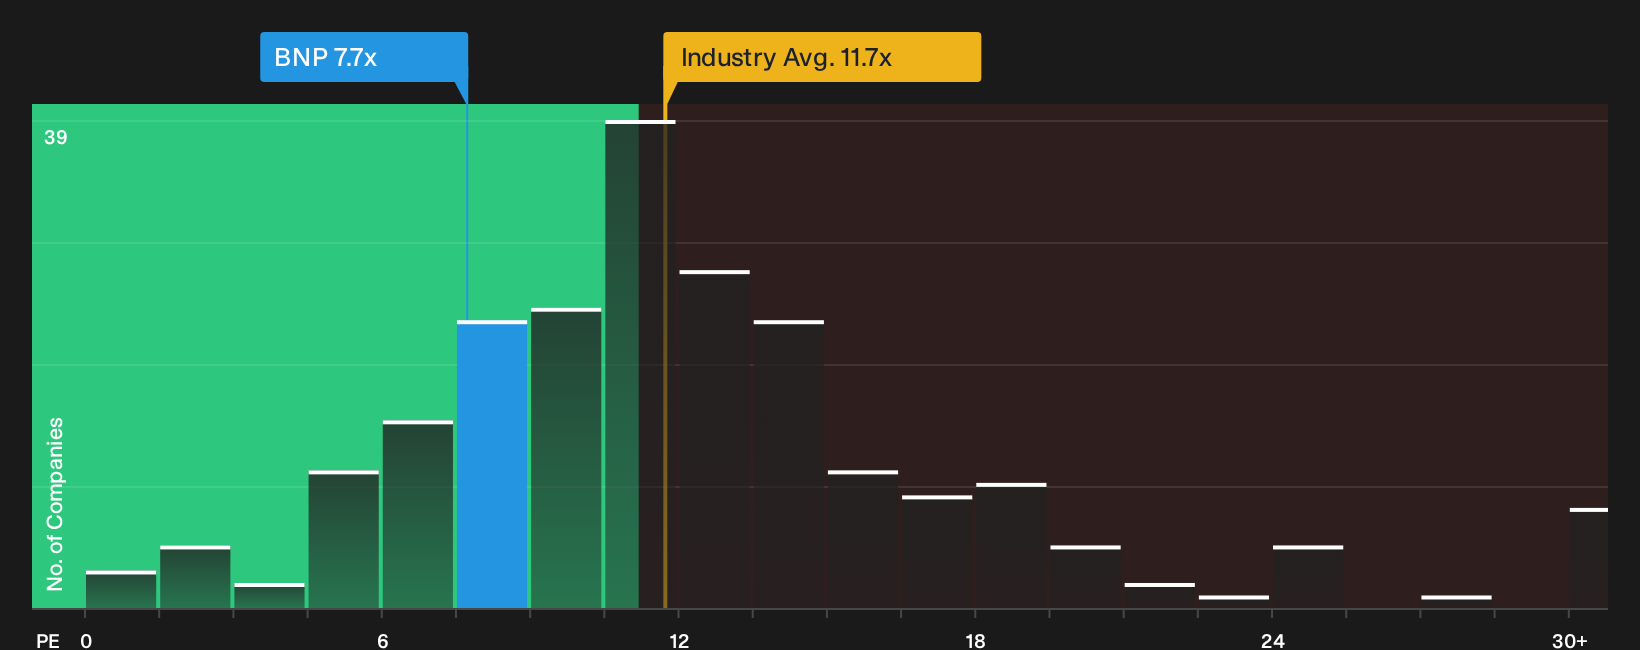
BNP Paribas (ENXTPA:BNP)
Overview: BNP Paribas is a large French universal bank based in Paris that provides retail banking, corporate banking, markets and insurance services worldwide, and is tightly linked to French government bond markets.
Operations: The group generates most of its revenue from Corporate and Institutional Banking at €19.1b, eurozone commercial and personal banking at €13.3b, and specialised businesses at €7.4b, with smaller contributions from other segments.
Market Cap: €98.1b
BNP Paribas is closely exposed to French sovereign risk, yet its size, diversification and capital position provide it with significant shock-absorber potential when OAT markets move.
"The group’s CET1 ratio already at 13%, with continued quarterly capital generation and a stated minimum 60% payout policy from 2027, alongside potential use of capital above 13% for additional distributions, creates room for higher shareholder returns that can support earnings per share growth even if revenue growth moderates."
There is a question of how a single unexpected pressure on French funding spreads might test the strength of that cushion in protecting earnings and dividends.
If that capital cushion is what you are focused on, read the full narrative for BNP Paribas to see how BNP Paribas could react if spreads really accelerate.
AXA (ENXTPA:CS)
Overview: AXA is a Paris based insurer and asset manager that sells protection, savings and retirement products worldwide and invests heavily in euro area sovereign bonds, including French OATs. This links its balance sheet directly to moves in French government yields.
Operations: AXA generates most of its €95.8b business revenue from Europe at €37.3b and France at €25.1b, with AXA XL contributing €19.4b and Asia, Africa & EME LATAM adding €14.0b.
Market Cap: €86.9b
AXA matters in this French sovereign risk screen because its insurance liabilities and large euro area bond portfolios sit right in the path of any sharp move in OAT yields. Its scale and digital push give it more tools than many peers to respond.
"Strong momentum in digitalization, AI adoption and streamlined direct distribution, including the wider rollout of AI ready applications and direct platforms such as Prima and Direct Assurance, is expected to keep improving customer acquisition, address more price sensitive and underserved segments and support higher future revenue growth and net margins for AXA."
What happens to those margin ambitions if one unseen pressure on how AXA prices long term protection contracts starts to bite more sharply?
When that pressure starts to bite, the full narrative for AXA maps how AXA’s digital momentum could still translate into accelerating value creation for long term holders.

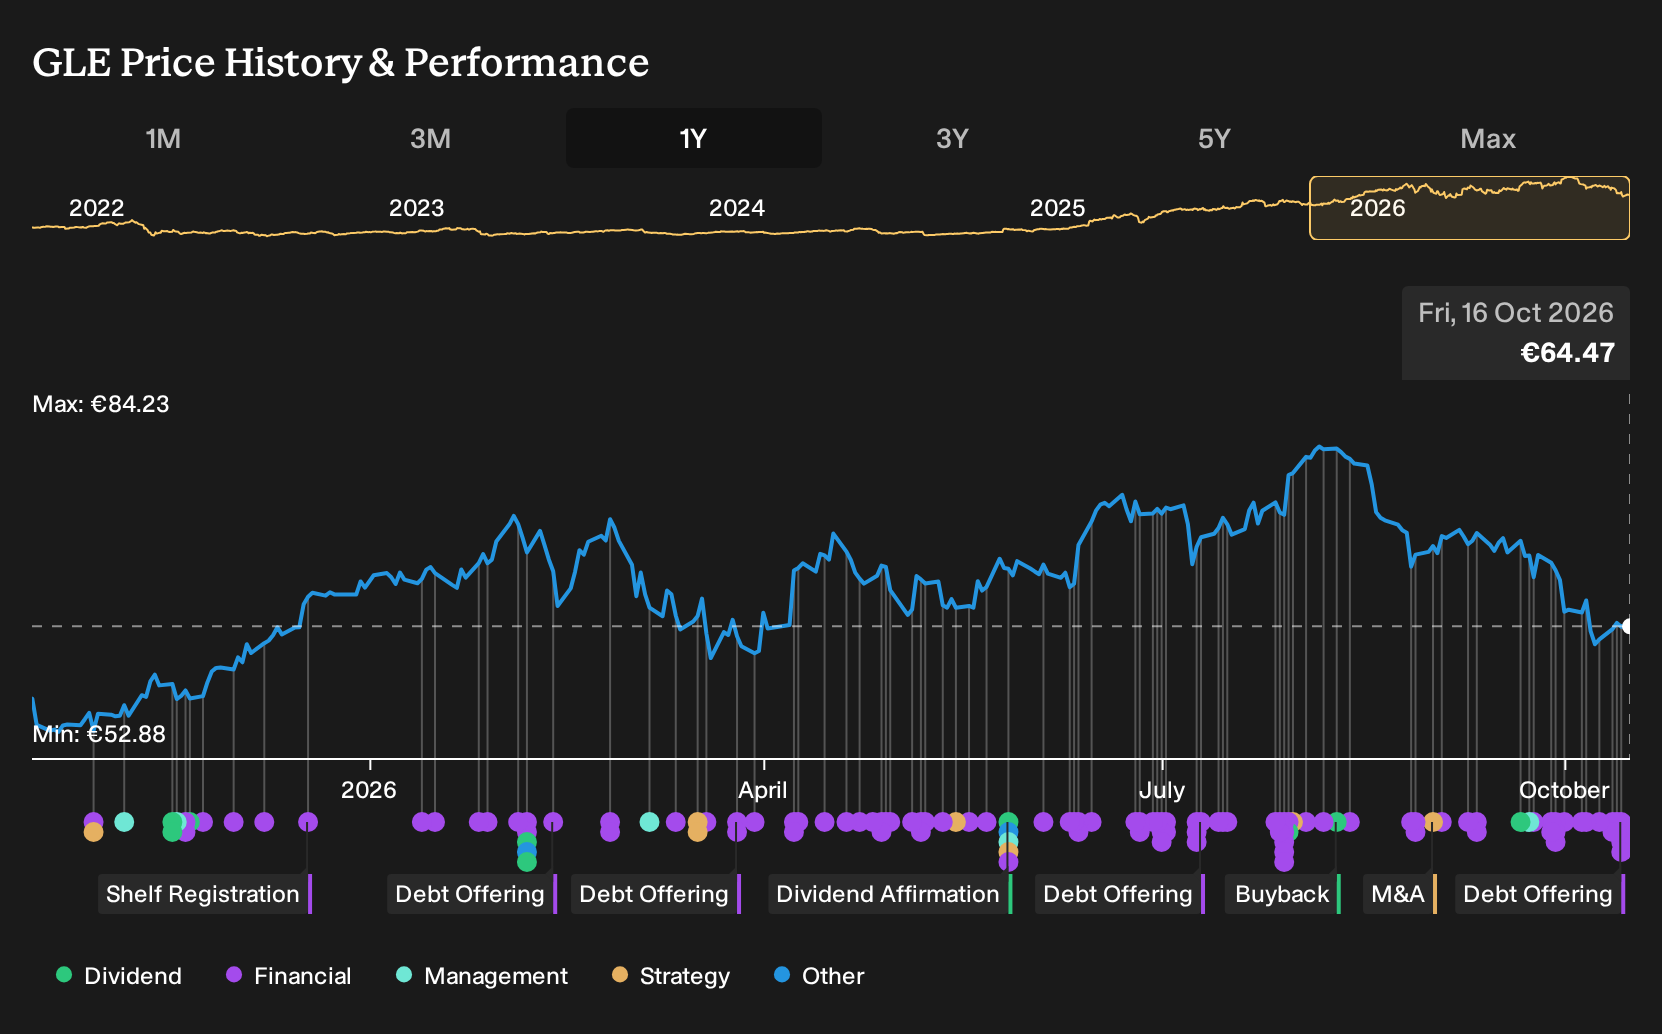
Société Générale Société anonyme (ENXTPA:GLE)
Overview: Société Générale Société anonyme is a large French bank headquartered in Paris that channels French savings into loans, markets and government bonds, making its earnings tightly linked to French sovereign funding conditions.
Operations: Société Générale Société anonyme generates most of its income from French Retail and Private Banking at €8.2b and Global Markets and Investors Services at €6.6b, with additional contributions from Mobility and Financial Services at €3.8b and International Retail Banking at €3.4b.
Market Cap: €46.3b
Société Générale Société anonyme is one of the purest ways to play French sovereign risk in this screen, since its trading books, domestic lending and funding costs all react quickly when OAT yields jump or ease.
"Although Société Générale has already delivered sizeable cost savings and targets €1.9b of further gross savings by 2029, management now indicates that the easiest efficiency wins are largely taken. Any shortfall or delay in deeper IT simplification, procurement discipline and headcount attrition would leave operating costs closer to current levels and restrict improvement in the cost to income ratio and net margins."
The real swing factor is what happens if a single assumption in Société Générale Société anonyme’s long term cost saving and capital return plan breaks.
If that assumption is what you care about, read the full narrative for Société Générale Société anonyme to see how cost cuts, capital plans and French sovereign risk could be quietly decoupling.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time headlines catch up, early entries can already be flying. Scan these under the radar opportunities while it matters and get in early.
- Spot resilient compounding potential by scanning a curated 232 resilient stocks with low risk scores that aims to keep drawdowns contained while momentum elsewhere is dropping.
- Ride structural power demand by checking a focused 42 power grid technology and infrastructure stocks curated around businesses tied to grid upgrades before that theme gains full crowd momentum.
- Track the AI hardware build out through a targeted 55 AI infrastructure stocks that highlights companies supplying the backbone of data centers while many investors stay distracted.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com