
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can BlueFirst Bookings Change The Case For JetBlue (JBLU) Stock?
- JetBlue Airways recently opened bookings for its new BlueFirst domestic first class on more than 30 routes and launched daily nonstop Fort Lauderdale to Cali service, while also securing FAA approval to acquire 22 LaGuardia slots from Spirit.
- The combination of a higher-yield premium cabin, deeper Latin American reach from Fort Lauderdale, and scarce LaGuardia access is reshaping how JetBlue balances revenue mix, network breadth and capital discipline.
- This analysis explores how JetBlue's new BlueFirst premium cabin influences the wider investment narrative around growth, costs and demand resilience.
Scan JetBlue Airways’ latest premium push against a curated group of carriers by reviewing list of solid balance sheet and fundamentals (25 results) that may be better positioned to fund route and cabin upgrades without stretching their finances.
JetBlue Airways Investment Narrative Recap
To own JetBlue Airways, an investor needs to believe this carrier can turn premium products, tighter network focus and cost control into a path toward smaller losses, and eventually, sustainable profits. The short term story still hinges on stabilising unit revenue and filling planes despite heavy competition and close in booking patterns.
Recent moves into BlueFirst and more Latin America flying may help ticket mix and loyalty, but they do not change the biggest near term swing factor, demand and pricing on core U.S. routes. The main risk stays the same. Rising labor and fuel costs could outpace any revenue benefit from these product upgrades.
The announcement with the clearest link to that catalyst is BlueFirst’s rollout on more than 30 routes. A dedicated first class cabin, new fare families and upgrade certificates give JetBlue Airways more ways to sell higher yielding seats without adding aircraft, which directly ties into the focus on capital light revenue opportunities.
Execution risk is real. Premium cabins need consistently strong uptake to justify extra space and service costs. If close in bookings soften or competitors discount hard, BlueFirst could struggle to cover its cost per seat. That would leave JetBlue still reliant on returning grounded jets and cost cuts to narrow its reported US$886.0m loss.
JetBlue Airways' analyst narrative points to revenues of US$12.7b and earnings of US$708.7m by 2029, based on an assumed yearly revenue growth rate of 10.1% and an earnings change of about US$1.6b from a current loss of US$886.0m to the forecast earnings level.
Uncover why JetBlue Airways' fair value indicates a 56% potential upside to its current price, which could narrow quickly.
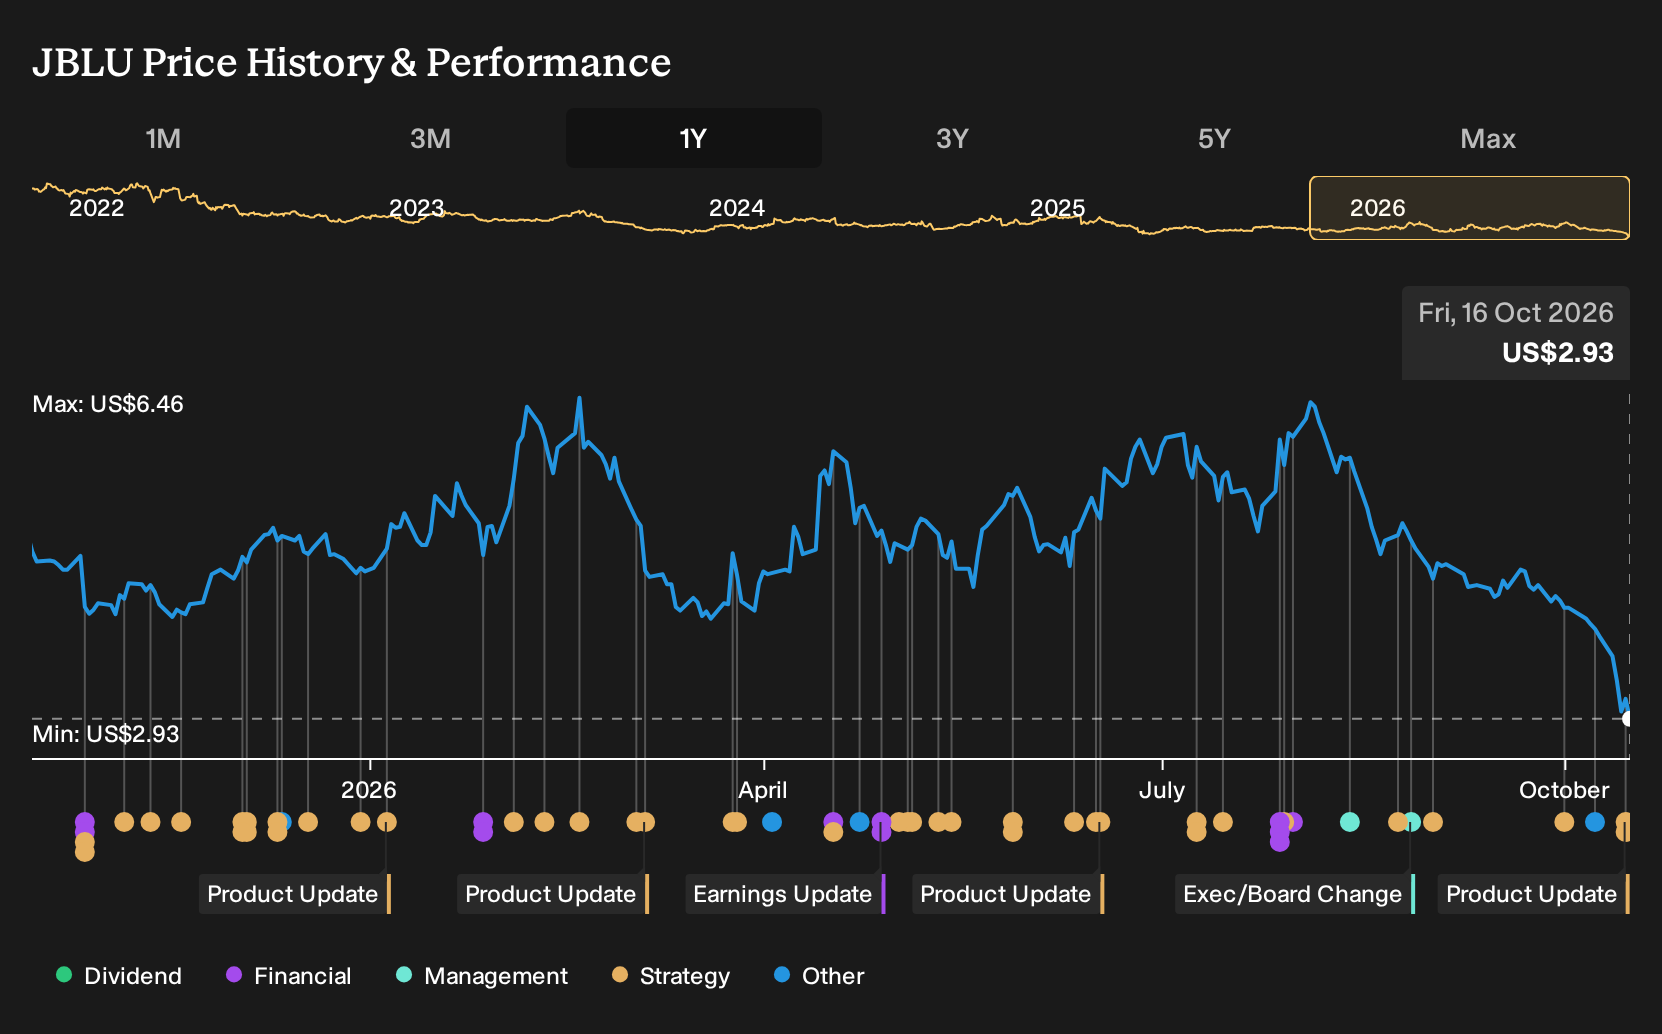
Exploring Other Perspectives
One alternate angle focuses on JetBlue Airways’ partnership and ancillary revenue story rather than premium cabins. The most optimistic analysts were already penciling in revenue of about US$13.2b and earnings of roughly US$421.4m by 2029. Those forecasts came before the BlueFirst launch and new Fort Lauderdale to Cali flying, so views on upside could shift meaningfully.
Explore 2 other JetBlue Airways fair value estimates, including one that suggests as much as 1911% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your JetBlue Airways research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JetBlue Airways. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JetBlue Airways' overall financial health at a glance.
Looking for more investment ideas beyond JetBlue Airways?
If JetBlue Airways sits on your watchlist, it can help to compare its profile with other businesses that have different risk, income, or balance sheet characteristics. The Simply Wall St Screener lets you scan the market quickly and focus on groups of companies that better match your own priorities.
- If capital preservation ranks high for you, consider scanning a set of resilient candidates through the 32 resilient stocks with low risk scores that may offer steadier fundamentals.
- Income focused investors might prefer companies with stronger cash returns, so it can be useful to review the 8 dividend fortresses for ideas with higher yields.
- Those hunting for future standouts before they are widely followed could start with the 20 high quality undiscovered gems and see which smaller businesses still fly under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com