
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Honeywell International (HON) Still Below Fair Value After Its Forge Cognition Launch?
Honeywell International (HON) just pushed deeper into physical AI with Forge Cognition, a new facility operations platform that relies on NVIDIA and Dell Technologies to run AI agents and real-time digital twins.
Recent trading suggests interest is picking up again in Honeywell International. The share price has risen 2.40% over the past month after a period where the 90 day share price return fell 6.53%, while the 1 year total shareholder return sits at 7.54%. This points to moderate gains for longer term holders and hints that product launches like Forge Cognition are arriving as momentum is trying to rebuild.
Scan other physical AI and automation opportunities that echo the Honeywell International story by reviewing our handpicked 91 robotics and automation stocks for your next round of ideas.
Honeywell International now trades at about US$211 while analyst targets cluster closer to US$255 and some intrinsic models sit well below the screen. Where does a fair anchor point in that spread actually lie?
Most Popular Narrative: 34% Undervalued
Against Honeywell International's last close of $211.41, the most followed narrative points to a fair value closer to $320.19. This frames the current price as a discount while tying that gap to a very specific automation and energy transition story.
HON RemainCo is a pure-play industrial automation and energy technology compounder with a confirmed June 29 catalyst, $19B+ in contracted backlog, a sold-out LNG order book, a global SAF technology licensing position, a recurring revenue platform transition underway via Forge, and an embedded position on both sides of the energy transition, all trading at a conglomerate discount that disappears in 53 days.
See why 67 investors see Honeywell International as 34% undervalued.
Result: Fair Value of $320.19 (UNDERVALUED)
Still, the Honeywell International story relies on RemainCo achieving its organic growth goals and on the market assigning a pure-play automation premium.
Find out about the key risks to this Honeywell International narrative.
Another View On Honeywell International's Valuation
The popular community thesis pegs Honeywell International around $320 per share, which frames the stock as undervalued. Our DCF model tells a different story. On that approach, the estimated future cash flow value is closer to $138, which implies the shares screen as expensive rather than cheap.
This kind of gap between narrative fair value and a cash flow based estimate often comes back to simple questions. Do you trust long term growth and margin assumptions more than the cash generation profile baked into our DCF model, or do you not yet have enough conviction to lean on them?
Look into how the SWS DCF model arrives at its fair value.
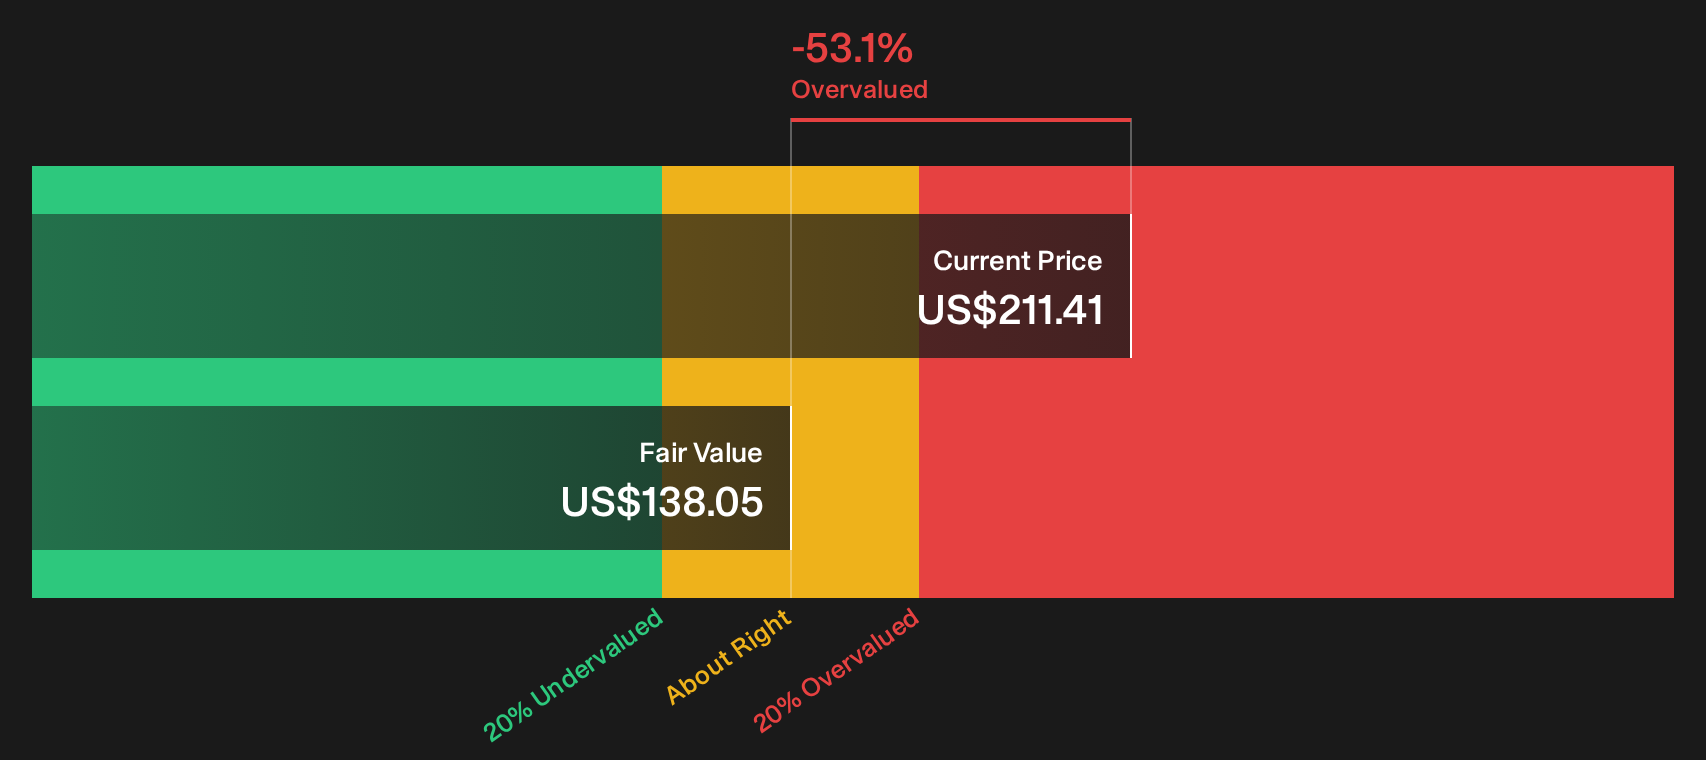
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages so far on Honeywell International, right. For a clearer view, consider both the potential advantages and the concerns by checking 4 key rewards and 3 important warning signs.
Looking for more Honeywell International style investment ideas?
If you like how Honeywell International blends industrial heft with clear catalysts, broaden your watchlist by scanning focused stock lists built to surface targeted opportunities quickly.
- Spot potential mispricings early and review companies that currently screen as 33 high quality undervalued stocks before attention crowds in.
- Target income-focused opportunities and assess businesses that show up as 8 dividend fortresses for steadier cash distribution potential.
- Prioritize resilience and capital preservation by checking out our 32 resilient stocks with low risk scores that filters for sturdier balance sheets and more defensive profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com