
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
The Bet Vesuvius Holders Made
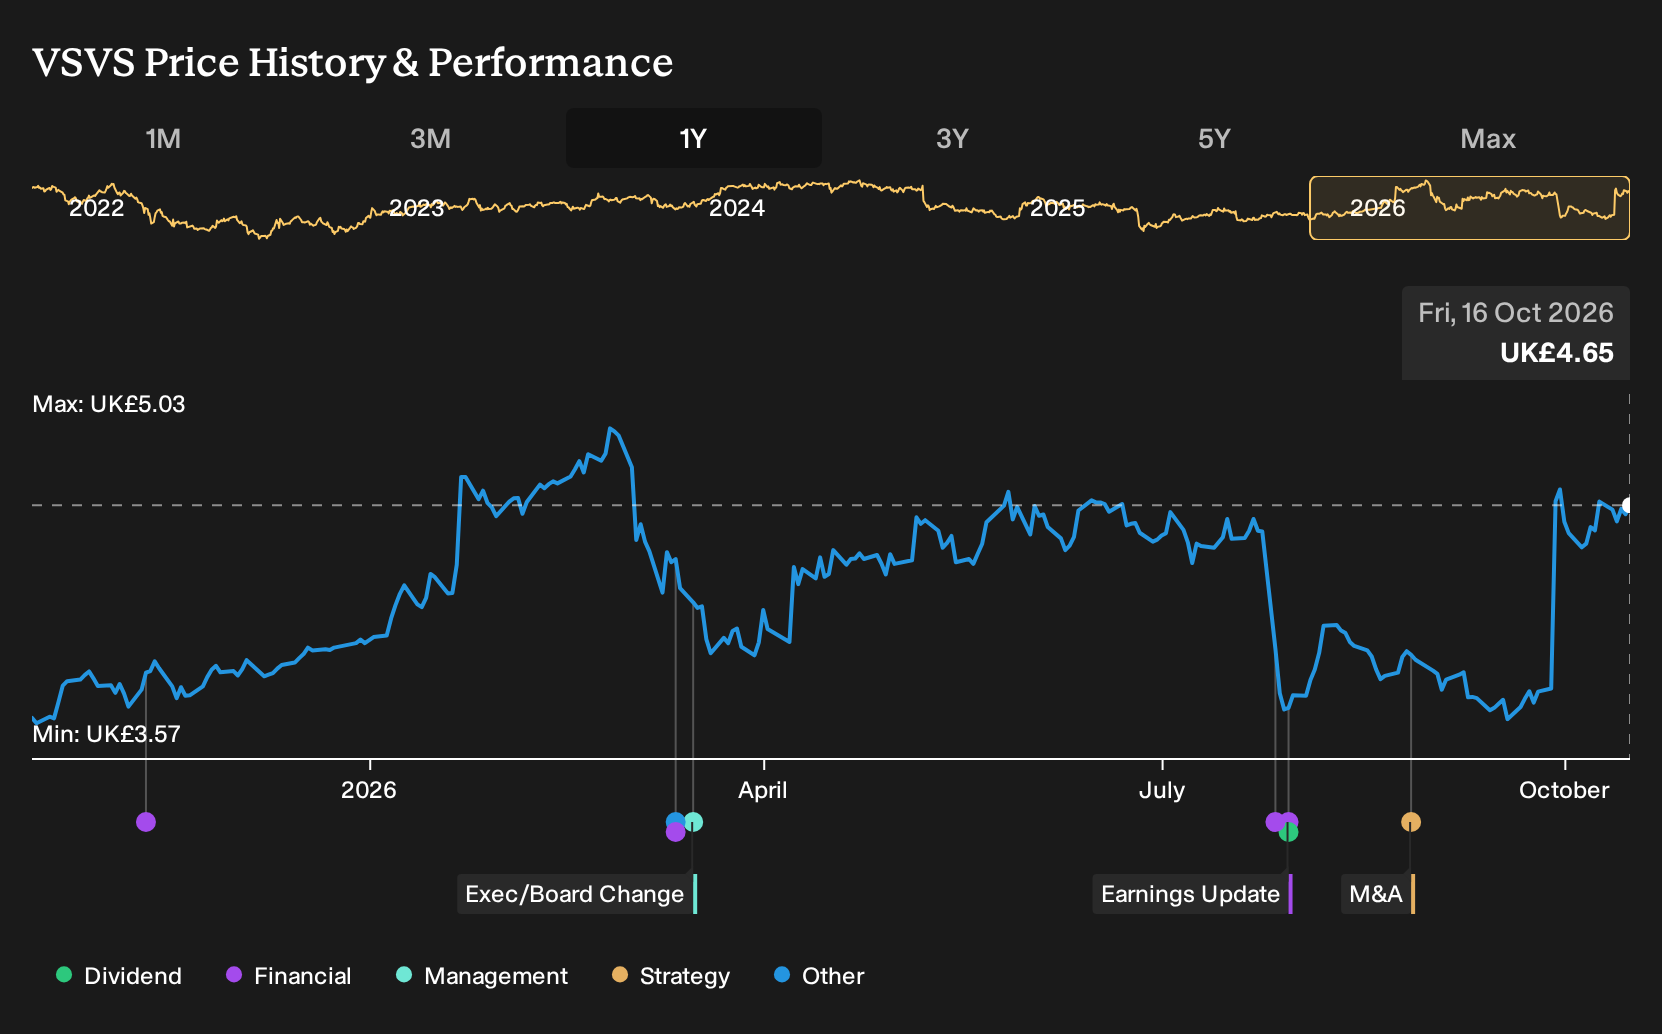
If you only glanced at Vesuvius’s latest results, the picture looked mixed, with higher revenue but a lower net margin in H1 2026 compared with H1 2025. Holding Vesuvius over the past year would have returned 37.5%, including dividends. If you had been weighing the bullish India growth story against concerns about decarbonization and electric arc furnaces back in October 2025, what really justified taking that risk?
Vesuvius has already moved. Pinpoint other ways to investigate the theme among 32 best rare earth metal stocks.
The Argument You Would Have Been Weighing On Vesuvius
The shares cost £3.60 at the start of the period, and anyone looking at Vesuvius then had to decide which story felt more convincing.
The bullish view put fair value at £4.38, a price that would only make sense if the optimistic assumptions played out, built on strong India infrastructure and renewable demand supporting higher margins and cash generation. This case leaned on Indian operations carrying higher profitability and an expanding share of overall sales.
The bearish narrative pointed to a fair value of £3.30, again simply the price implied if its more cautious earnings path proved accurate, and focused on electric arc furnace adoption shrinking demand for traditional refractory products and pressuring long term revenue potential.
What The Results Changed For The Vesuvius Debate
What actually turned up in the period was pressure on profitability. Vesuvius reported H1 2026 revenue of £922.9m versus £907.5m in H1 2025, while net income slipped from £30.9m to £16.9m and net margin moved from 3.4% to 1.8%. That pattern, higher sales with thinner margins, leaned toward the cautious case that questioned the durability of earnings power.
The useful takeaway is simple. When a story leans on margin expansion, check whether extra revenue is turning into extra profit. Track net income and margin together, not just top line, any time you weigh a similar argument at another cyclical industrial group.
What Vesuvius’s Price Now Asks You To Believe
Today Vesuvius trades at £4.65, after a 37.5% total return over the past year. The selected Narrative’s Fair Value sits below the current price, which frames today’s level as already baking in a lot of execution success.
The Narrative focuses less on end market decline and more on whether footprint changes, MMS integration and robotics adoption really deliver the hoped for uplift. A buyer today effectively assumes those projects hit management targets, so the question is how the concrete risks around cost savings and plant moves might affect that outcome.
"The main thing that has to go right is that Vesuvius completes its planned footprint rationalisation, cost savings and integration of the MMS crucible business so that recurring savings and foundry profits reach the levels management is targeting. The current valuation implies that Vesuvius shares already price in successful execution on structural cost savings, recovery in steel production outside China and further profit contribution from new products and robotics."
One Narrative disagrees with today's price. → See where this Narrative says Vesuvius should trade
After Vesuvius, One Step Away
Vesuvius asks you to think about heavy industry upgrading old assets. The next question is who keeps the power side of that story moving.
Steel plants, data centers and electrified transport all need dependable electricity. Not just more power, but power that can be dispatched when required.
Another industrial player focuses on that grid and generation puzzle. It supplies equipment that produces electricity, then manages how it is moved and stored.
Service contracts on those assets can run for decades, tied to constant maintenance and upgrades. If electricity demand keeps shifting, that service mix may matter even more.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 38% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com