
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Moderna (MRNA) Stock May Still Look Stretched Despite Cancer Vaccine News
Moderna has logged very strong gains over the past year, and the sharp move now puts a spotlight on a simpler question for investors who care about valuation: Is the current share price still grounded in what the business is generating from its sales?
- Over the past 12 months, Moderna has delivered a return of roughly 7x, which puts a lot of weight on whether the revenue base can carry that kind of re-rating.
- Recent news around personalized cancer vaccines and new manufacturing capacity suggests investors are weighing how future mRNA product sales may support the current market value and any further capital spending needs.
- Your read on Moderna is one view; the desks covering it have another. See what analysts think Moderna's shares could be worth.
The issue now is whether Moderna's present valuation can be explained by its sales once you strip away the headline share price moves.
If Moderna's 7x one year move has you thinking more about mRNA and related biotech opportunities, a focused stock screen is a clear next step. You can start with 33 healthcare AI stocks.
Has Moderna Run Too Far on Sales?
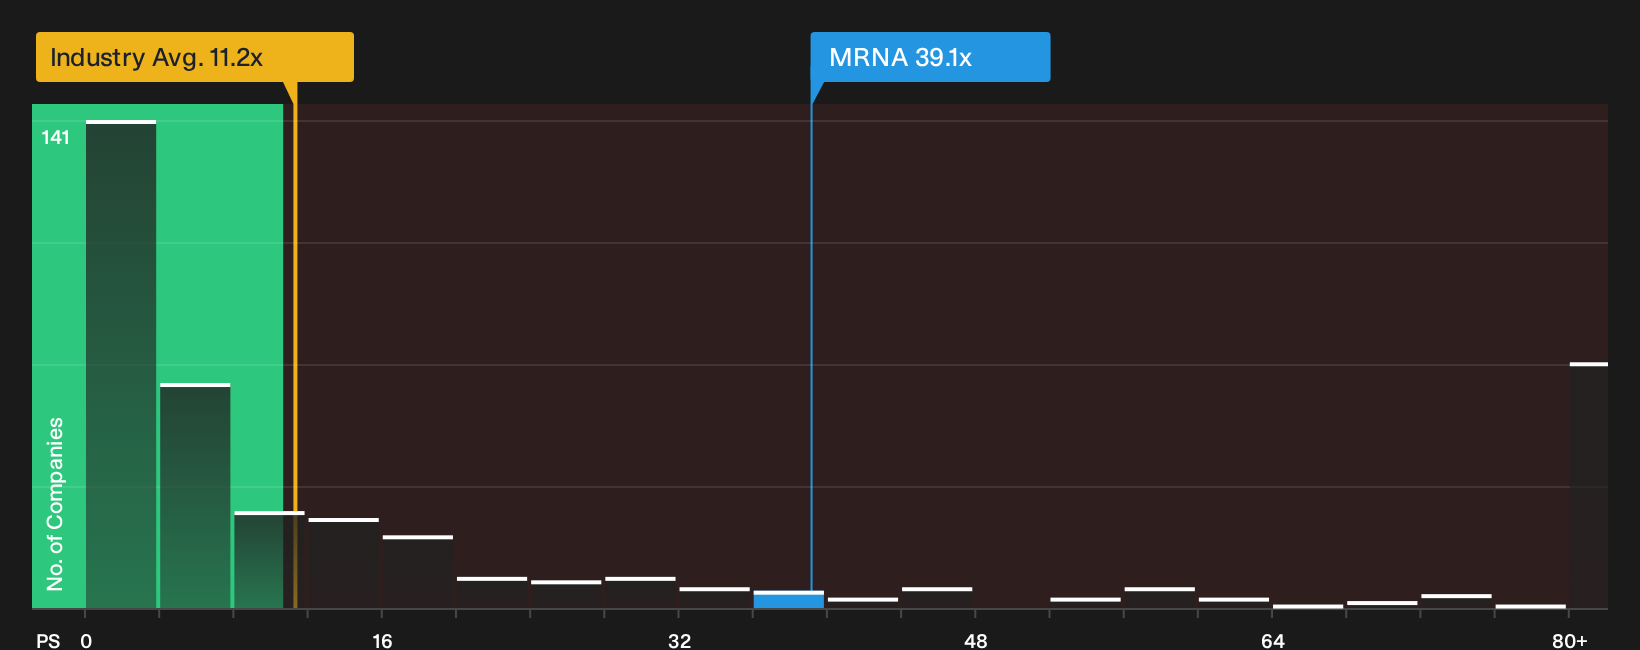
P/S is a natural fit for Moderna because the business is still working through volatile earnings while revenue remains the clearer anchor for valuation. On this yardstick, the stock trades on a P/S of 39.1x, compared with roughly 11.2x for the broader biotech industry and about 7.2x for peers in the same space. That puts the Moderna share price on a much richer revenue tag than many comparable biotech companies, even before getting into profitability.
The tailored fair multiple that blends Moderna's growth profile, margins, scale and risk comes out far lower than where the current 39.1x P/S sits. The wide gap suggests the model is heavily penalising recent losses and the quality and concentration of current sales. Despite the recent lift from the NIH cancer vaccine initiative and optimism around Moderna's personalized oncology pipeline, the stock still screens as overvalued on this framework rather than near any calibrated midpoint. Explore the numbers behind Moderna's P/S valuation.
The Moderna Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Moderna's valuation puzzle leaves off by spelling out what growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than today. These Narratives sit on the Community page. Each one frames fair value as a thesis about Moderna's business that you can track over time rather than a single static number, which helps you see how the story holds up as new information comes through.
One of the top community narratives on Moderna: 78% overvalued
"Several firms, including large banks such as Goldman Sachs, have lifted price targets into a US$120 to US$200 range and shifted ratings up the spectrum…"
Discover why this Narrative puts Moderna at 78% overvalued.
Before you move on Moderna, there is still a final piece to weigh
Valuation only tells part of the Moderna story, because separate checks have already highlighted specific business risks that deserve a closer look before you anchor on the current multiples. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com