
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Halozyme Therapeutics (HALO) Undervalued On Its Expanded Argenx Licensing Deal?
Why Halozyme Therapeutics Just Drew Fresh Attention
Halozyme Therapeutics (HALO) is back in focus after expanding its global collaboration and license agreement with argenx. The revised deal adds two more ENHANZE targets, increasing argenx's exclusive access from six to eight.
Recent trading has been strong. Halozyme Therapeutics has a 7 day share price return of 10.34% and a 90 day move of 58.05%. The 1 year total shareholder return of 81.77% and 3 year total shareholder return of about 2.5x indicate sustained momentum rather than just a short term reaction to the argenx news.
Spot 20 high quality undiscovered gems that, like Halozyme Therapeutics, are using partnerships and licensing deals to turn specialized technology platforms into scalable royalty and milestone streams.Halozyme Therapeutics has run hard, yet the share price now sits above the average analyst target while some intrinsic value estimates sit much lower. Where does a fair entry point realistically fall within that range?
Most Popular Narrative: 19.8% Undervalued
According to Teg's narrative, Halozyme Therapeutics screens as undervalued, with an indicative fair value of $151.83 versus a last close of $121.84. This puts recent price strength in a different light for anyone focused on long term royalty potential rather than short term analyst targets.
Most investors view Halozyme Therapeutics through a single lens: ENHANZE®. That perception made sense several years ago, when ENHANZE® was the company's primary growth engine and the overwhelming source of value. Today, however, management's vision appears far broader. Halozyme is no longer building around one platform. It is attempting to create a portfolio of drug-delivery technologies that could eventually support multiple royalty streams across different therapeutic modalities.
See why 3 investors see Halozyme Therapeutics as 20% undervalued.
Result: Fair Value of $151.83 (UNDERVALUED)
Still, Halozyme Therapeutics needs partner-led products and platform rollouts to stay on track, and any setback in ENHANZE or Hypercon adoption could quickly challenge this thesis.
Find out about the key risks to this Halozyme Therapeutics narrative.
Another View: What Multiples Say About Halozyme Therapeutics
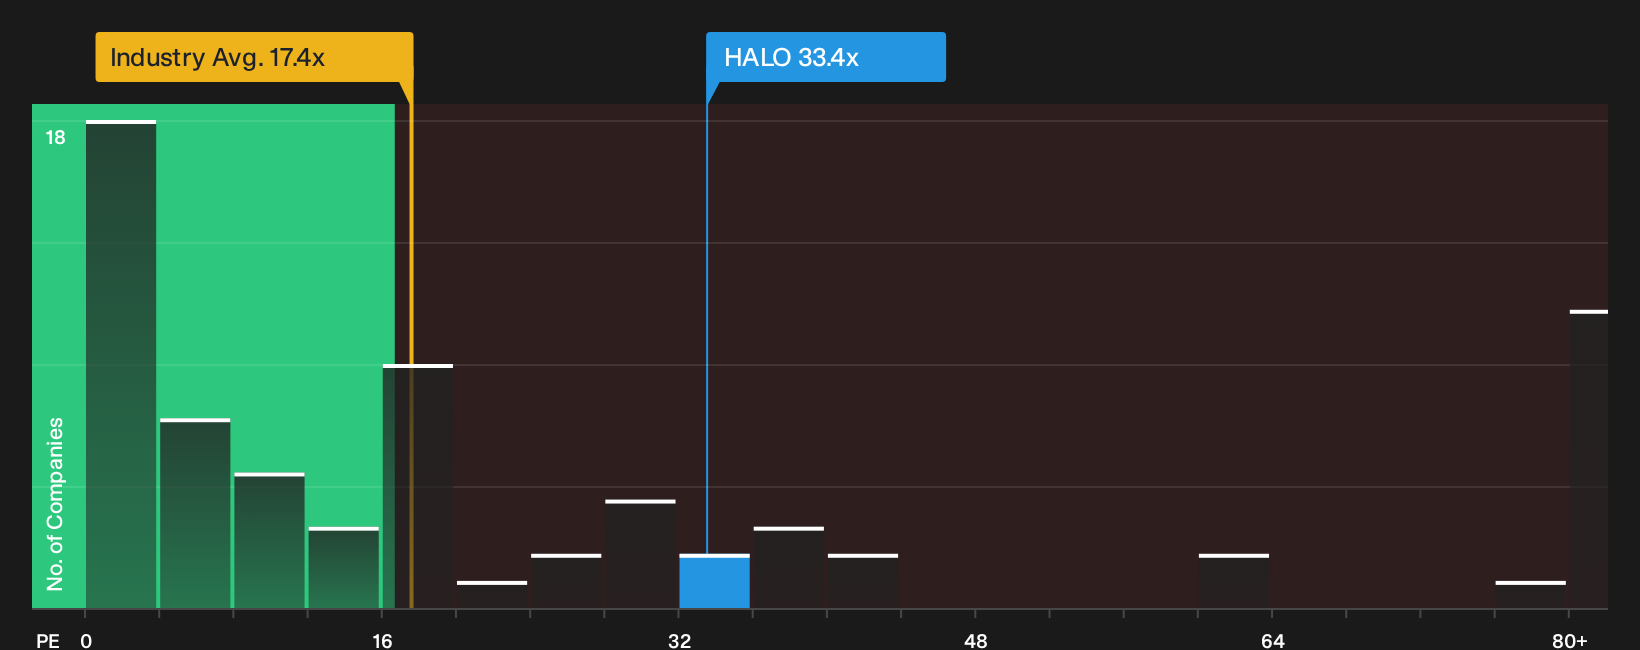
The story changes when you swap the royalty model for a simple earnings yardstick. Halozyme Therapeutics trades on a P/E of 33.4x, which is almost double the US Biotechs average of 17.4x and well above a fair ratio of 22.7x. That gap points to richer pricing on current earnings, so how comfortable are you paying up today for a thesis built on future platforms rather than current profit?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Halozyme Therapeutics so far. If you want to move before sentiment shifts again, pull up the data directly and weigh the 2 key rewards and 3 important warning signs.
Looking for more Halozyme Therapeutics style ideas?
If Halozyme Therapeutics caught your attention, do not stop here. Use fresh data backed shortlists to keep spotting setups before the crowd reacts.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) for companies that can better handle shocks when conditions change.
- Hunt for strong businesses priced below intrinsic estimates by reviewing the 33 high quality undervalued stocks that combine quality metrics with compressed valuation multiples.
- Prioritise stability and capital preservation by checking the 32 resilient stocks with low risk scores where lower risk scores help you avoid fragile stories that can quickly unravel.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com