
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Centrus Energy Stock In Focus After $900 Million Nuclear Fuel Contract
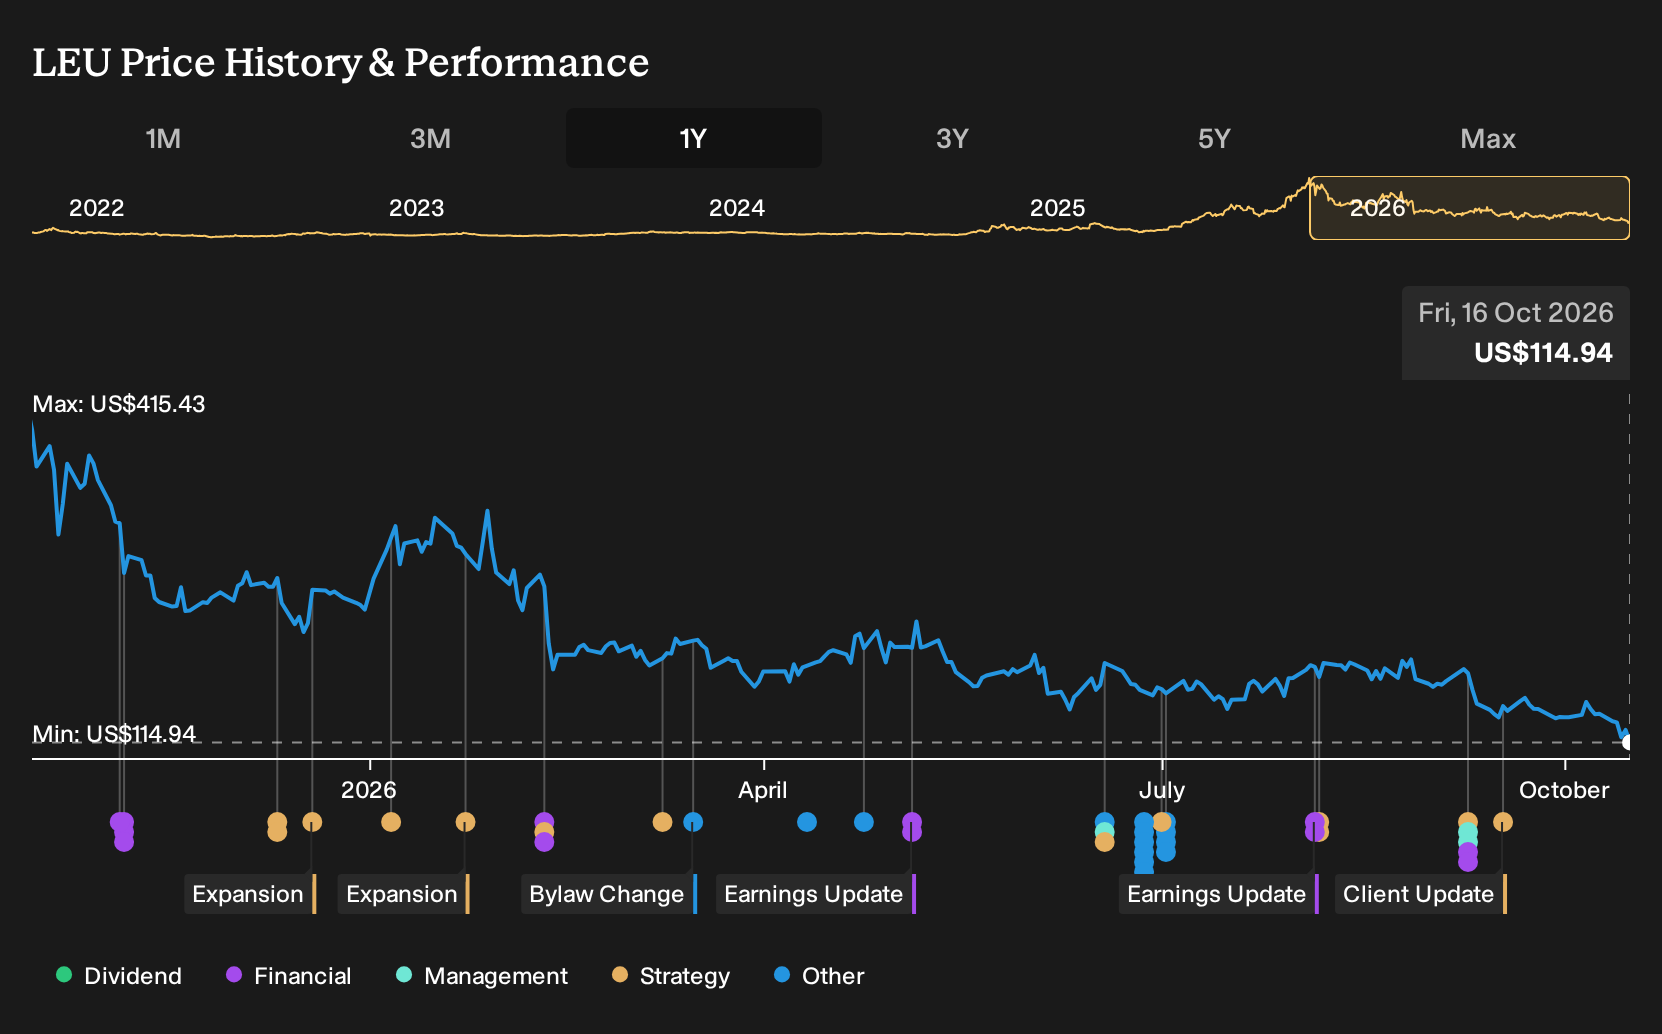
- Centrus Energy secured a US$900 million Department of Energy contract for high-assay low-enriched uranium and was added to the S&P SmallCap 600, reinforcing its role in advanced nuclear fuel supply.
- The new HALEU award and index inclusion highlight Centrus Energy’s unique positioning. At the same time, rising sales coincide with weaker net income and slimmer margins that pressure the earnings profile.
- We will now assess how Centrus Energy’s investment narrative could shift given the US$900 million HALEU contract from the Department of Energy.
Scan other nuclear fuel and reactor-focused opportunities that are moving on similar catalysts with the curated 16 nuclear energy infrastructure stocks.
Centrus Energy Investment Narrative Recap
For any shareholder in Centrus Energy, the core belief is that demand for enriched fuel, including HALEU, turns the current backlog and technical capabilities into durable, profitable work. The US$900 million Department of Energy award supports that idea by extending revenue visibility. In the short term, the key catalyst remains execution on enrichment capacity and contract delivery rather than new headlines alone.
The biggest near term risk is that weaker net income and slimmer 10.2% margins, compared with 24% last year, persist even as sales expand. If costs tied to ramping enrichment and compliance stay elevated, the contract wins could add volume without meaningfully improving profitability.
The US$900 million HALEU contract is the announcement that matters most here. It directly relates to Centrus Energy’s role as a US based enricher and connects to expectations around multi year government and utility commitments. The award gives more clarity on future work, which fits into that US$3.6b backlog narrative.
It also ties into the main execution swing factors. The contract still needs efficient capacity build out, careful cost control and timely funding flows to avoid periods of underused assets that pressure returns. If those pieces align, the HALEU award can support backlog conversion and temper concerns about recent earnings volatility and share price swings.
Centrus Energy's analyst narrative points to forecast revenue of US$487.7 million and expected earnings of US$50.7 million by 2029. Earnings are projected to move up by about US$2.2 million from US$48.5 million today, while revenue is assumed to remain fairly flat over that period.
Uncover how Centrus Energy's fair value indicates a 111% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
You are not the only one wondering if the US$900 million HALEU contract changes the story. The most optimistic Centrus Energy analysts were already penciling in US$677.3 million of revenue and US$107.7 million of earnings by 2029, far above consensus, and treating efficient Piketon and Oak Ridge build outs as the real swing factor. Those views came before this announcement, so opinions and forecasts may shift as new information filters through. Use that spread in expectations as a reminder to compare several narratives before deciding how this stock fits your own portfolio.
Explore 5 other Centrus Energy fair value estimates, including one that suggests as much as 431% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Centrus Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Centrus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centrus Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Centrus Energy?
Once you have a handle on Centrus Energy, it can help to set it against a broader watchlist of potential opportunities using the Simply Wall St Screener so you can see where it truly fits in your portfolio.
- If you care most about resilient balance sheets and steady fundamentals, start with a curated list of solid balance sheet and fundamentals (25 results) that can anchor the more volatile parts of your holdings.
- For those hunting for pricing that looks appealing relative to quality, scan the 33 high quality undervalued stocks to spot companies where fundamentals and market expectations appear out of sync.
- Income focused investors who want cash returns as well as potential capital gains can review a targeted 8 dividend fortresses to source ideas with higher yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com