
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BioMarin Pharmaceutical (BMRN) Flags 13 ASBMR Studies, Is It 25% Undervalued?
BioMarin Pharmaceutical (BMRN) just flagged a busy clinical calendar, with 13 study readouts on deck at ASBMR 2026 and fresh regulatory moves around VOXZOGO in achondroplasia and hypochondroplasia.
For shareholders watching the tape, BioMarin Pharmaceutical’s clinical drumbeat has been running against a softer trading backdrop. The share price is at US$54.68 after declining 14.5% over the past month and 8% year to date. The 1 year total shareholder return is slightly positive at 2.6%, but the 3 and 5 year total shareholder returns of 33.4% and 25.9% in decline indicate that longer term momentum has faded.
Spot fresh catalysts at work by comparing BioMarin Pharmaceutical's VOXZOGO pipeline story with a curated 20 high quality undiscovered gems list of companies that are also pushing under-followed therapies toward key regulatory and clinical milestones.The recent slump in BioMarin Pharmaceutical’s share price sits against rising revenue and net income. Is this mostly changing sentiment, or has the business reset enough to justify a different valuation?
Most Popular Narrative: 25.2% Undervalued
On the narrative view, BioMarin Pharmaceutical’s fair value sits at $73.10 compared with the recent $54.68 share price, which frames a sizeable valuation gap that investors have been debating all year.
Business: focus on enzyme replacement therapies for ultra-rare genetic diseases, special medical knowledge, few patients/limited sales potential per drug globally (no blockbusters), established world wide distribution, complex production, orphan drugs patent protection
The Amicus Therapeutics end 2025 acquisition has understandable strategic fit and adds two US- and EU-approved rare-disease therapies, accretive after closing, commitment to deleveraging
See why 0 investors see BioMarin Pharmaceutical as 25% undervalued.
According to PKU, that assessment uses a 9% discount rate and arrives at a $73.10 fair value, which implies BioMarin Pharmaceutical trades at a 25.2% discount to that estimate. The focus on ultra rare conditions, long treatment durations and orphan drug protection sits at the center of that thesis. The planned Amicus Therapeutics deal is framed as reinforcing the rare-disease focus rather than changing it.
For readers who give weight to this kind of business-first narrative, the implied upside rests on a mix of exclusive know-how, complex manufacturing and pricing power in life-long conditions rather than on chasing broad blockbuster markets. Those are qualitative pillars, so it is important to cross-check them against your own assessment of BioMarin Pharmaceutical’s pipeline risk, debt profile, and the pressure that can come from payers on high-cost rare-disease therapies.
Result: Fair Value of $73.10 (UNDERVALUED)
Still, the BioMarin Pharmaceutical story could be knocked off course if rare disease pricing comes under pressure or if the planned Amicus Therapeutics acquisition timeline slips.
Find out about the key risks to this BioMarin Pharmaceutical narrative.
Another View: BioMarin Pharmaceutical Through The P/E Lens
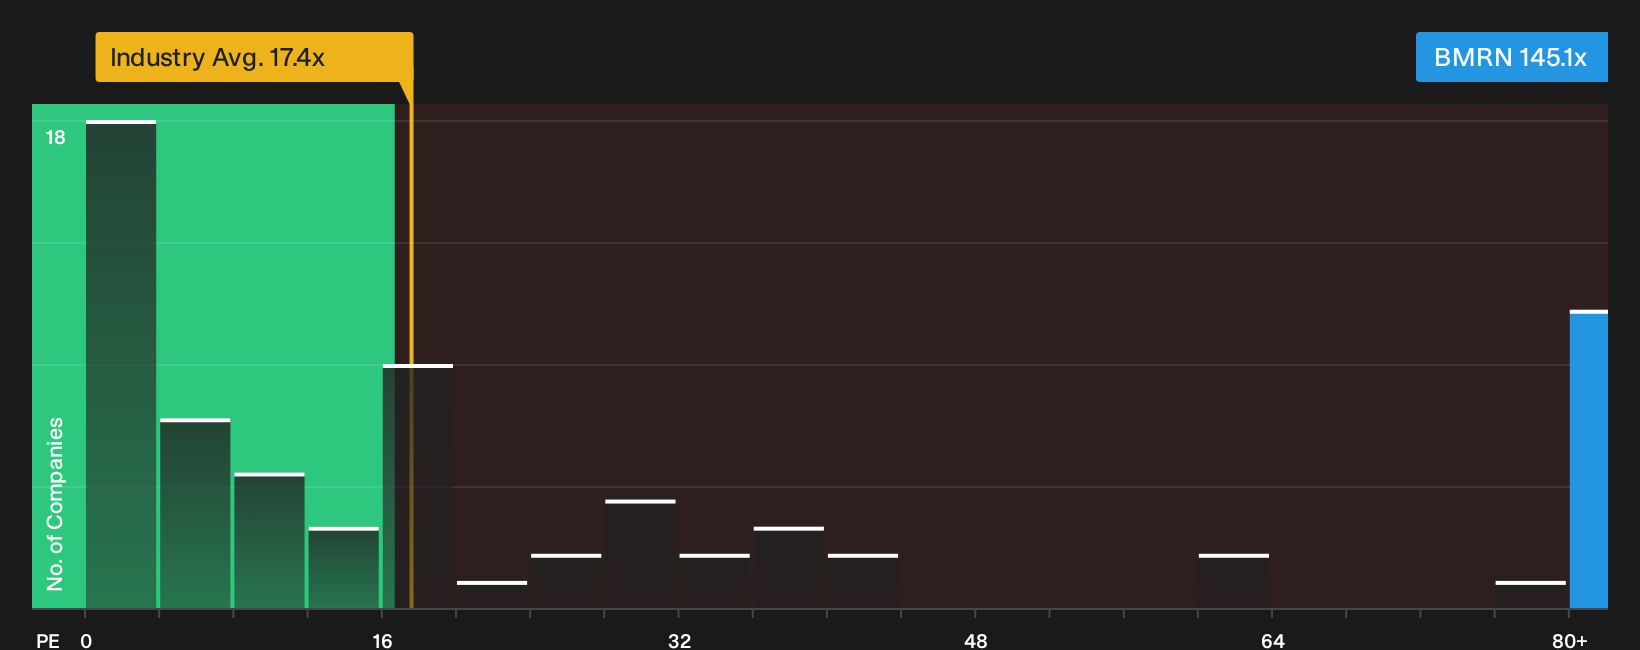
The DCF work paints BioMarin Pharmaceutical as undervalued, yet the market is charging a very different price when you use earnings as the yardstick. At a P/E of 145.1x, compared with 17.4x for the US biotech industry, 55x for peers and a fair ratio of 32x, the stock carries clear valuation risk if future profits do not live up to expectations.
See what the numbers say about this price gap and how the market could move toward that fair ratio in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone of BioMarin Pharmaceutical’s valuation story leaves you on the fence, that is a cue to review the underlying data yourself and act while the market is still debating the thesis. Start with the 2 key rewards and 4 important warning signs.
Looking for more BioMarin Pharmaceutical sized ideas?
If BioMarin Pharmaceutical has you rethinking where you put fresh capital, do not stop at one ticker. Let the best ideas come to you.
- Target resilient value by scanning a 33 high quality undervalued stocks group of companies that pair quality fundamentals with prices that still look reasonable on key metrics.
- Prioritize sleep-at-night holdings through a 32 resilient stocks with low risk scores set of businesses with sturdier balance sheets and fewer red flags in their risk profile.
- Hunt for tomorrow's quiet outperformers with a 20 high quality undiscovered gems collection of under-followed stocks that already show solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com