
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lattice Semiconductor (LSCC) Shares Slid, So What Is Behind The Fresh Attention?
Lattice Semiconductor (LSCC) just launched the Secure Control and Management Plane workstream at the 2026 OCP Global Summit, introducing an open, vendor-neutral architecture aimed at standardizing secure control and management across AI data center infrastructure.
For context, Lattice Semiconductor shares closed at US$103.65 after a sharp 7 day share price decline of 17.77% and a 90 day share price return that is down 17.45%. Yet the year to date share price return is 31.79% and the 1 year total shareholder return is 47.73%. This points to strong longer term momentum even as recent volatility and the fresh shelf registration filing suggest investors are reassessing both growth potential and funding flexibility around these new AI data center security launches.
Spot opportunities around Lattice Semiconductor by scanning a curated set of AI infrastructure stocks, starting with 55 AI infrastructure stocks, that are tightly linked to data center security, compute, and control.
Lattice Semiconductor now trades well below the average analyst target and slightly above some intrinsic value estimates. After this pullback, where does a reasonable fair value range actually cluster for the stock today?
Most Popular Narrative: 37% Undervalued
On the most followed narrative, Lattice Semiconductor screens as undervalued, with a fair value of $164.54 against a last close of $103.65. This view anchors that gap in AI centric growth and margin assumptions rather than short term sentiment.
The expected ramp of robotics, humanoids and broader physical AI systems starting late next year, where management points to multiple FPGA sockets per system and recovering industrial demand, gives Lattice Semiconductor a second major usage driver that can broaden revenue and earnings beyond data center AI spend.
The planned scale up of operations through expanded assembly and test capacity, integration of a high margin AMI business and the use of term debt with a target to bring leverage below 2x EBITDA by 2027 is intended to support a larger revenue base while maintaining high corporate margins and cash generation.
See why 28 investors see Lattice Semiconductor as 37% undervalued.
Result: Fair Value of $164.54 (UNDERVALUED)
Still, the bullish Lattice Semiconductor story can crack if assembly and test bottlenecks persist, or if new tariffs bite into costs and squeeze already thin net income.
Find out about the key risks to this Lattice Semiconductor narrative.
Another View: Lattice Semiconductor Looks Pricey On Sales
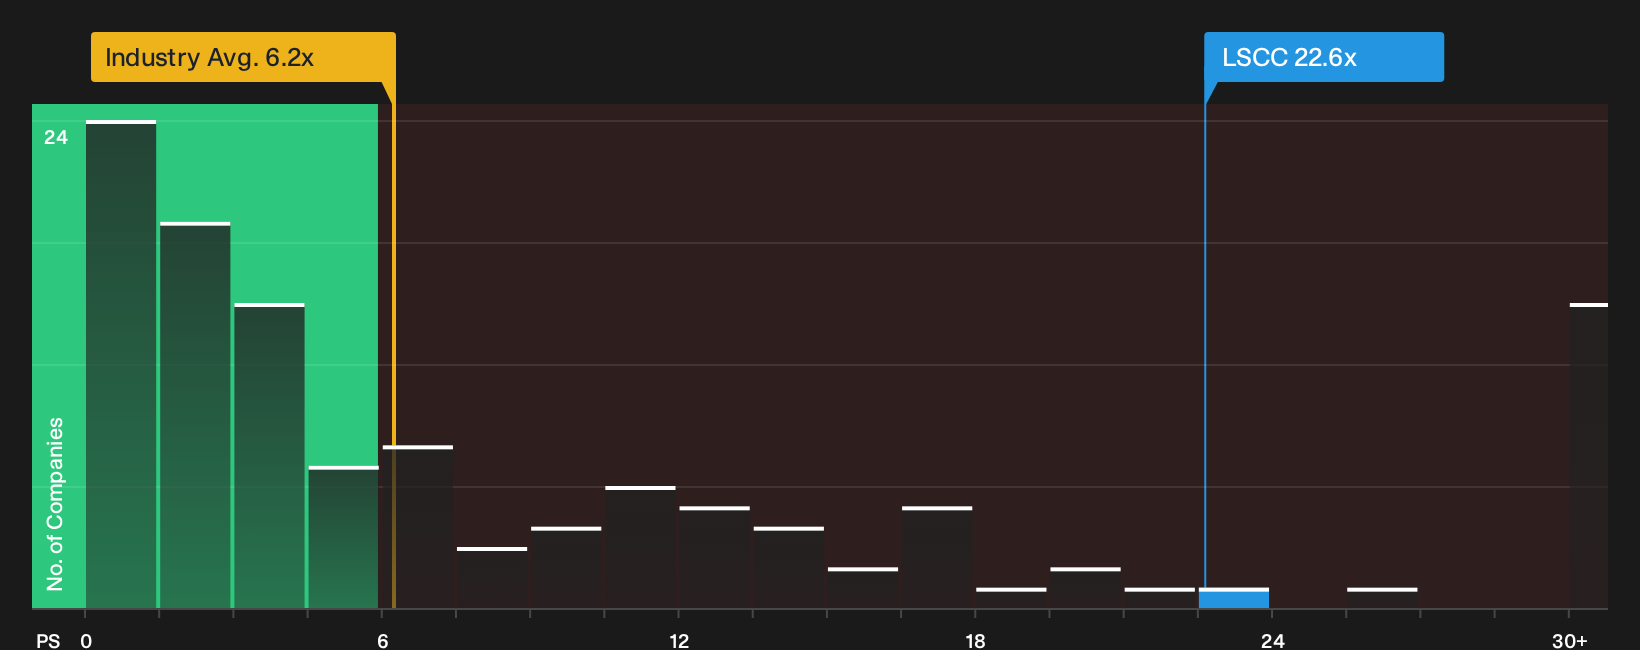
On a story driven lens, Lattice Semiconductor screens as materially undervalued. On a simple P/S check, it looks stretched. The current P/S of 22.6x is far above the US Semiconductor industry at 6.2x and the peer average at 5.5x, and even sits well ahead of a fair ratio of 13.3x that our model suggests the market could move toward. That gap points to meaningful downside risk if sentiment on growth cools. The question for investors is which yardstick to rely on more when the next bout of volatility hits.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Lattice Semiconductor after that kind of pullback and valuation split? Act quickly, stress test the upside and downside, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Lattice Semiconductor?
Use the same energy you brought to understanding Lattice Semiconductor to hunt for fresh opportunities with a focused stock screener that filters by quality, value, and resilience.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that filters for financial strength and cleaner funding profiles.
- Hunt for pricing gaps by running through a 33 high quality undervalued stocks that filters for quality businesses trading below intrinsic estimates.
- Prioritise sleep-at-night stability by working through a 32 resilient stocks with low risk scores designed to surface stocks with lower risk scores and sturdier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com