
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Canadian Natural Resources (TSX:CNQ) Faces A 5% Premium After Earnings Beat
Canadian Natural Resources (TSX:CNQ) has just posted quarterly results that surpassed consensus forecasts on both earnings per share and revenue, drawing fresh attention to the stock’s valuation, risk profile, and dividend appeal.
The stronger quarter seems to have fed straight into momentum. Canadian Natural Resources’ share price is up 3.2% over the past day and has a 30 day share price return of 9.7%. The 1 year total shareholder return of 88% and 5 year total shareholder return of about 2.7x suggest gains have been building rather than fading.
Scan beyond Canadian Natural Resources and size up other energy players with 5 high quality undervalued stocks that have solid fundamentals but may still be flying under the radar.
Canadian Natural Resources now trades just above the average analyst target, yet sits at a sizeable discount to one fair value estimate. Where does that leave the stock on pure valuation grounds?
Most Popular Narrative: 5% Overvalued
Canadian Natural Resources closed at CA$76.10 compared with a narrative fair value of CA$72.57. The most followed thesis sees limited upside from here and depends on how the asset base and capital return policy develop.
The updated free cash flow allocation policy, which now directs 75% of free cash flow to shareholders once net debt falls below $16b and 100% once it reaches $13b, sets up a framework in which future cash generation is increasingly tied to dividends and buybacks, with potential implications for earnings per share and equity valuation.
See why 215 investors see Canadian Natural Resources as 5% overvalued.
Result: Fair Value of CA$72.57 (OVERVALUED)
Still, the narrative can break if large oil sands expansions remain on hold for longer, or if crude price swings keep compressing Canadian Natural Resources’ valuation multiple.
Find out about the key risks to this Canadian Natural Resources narrative.
Another View: Canadian Natural Resources Through Earnings Multiples
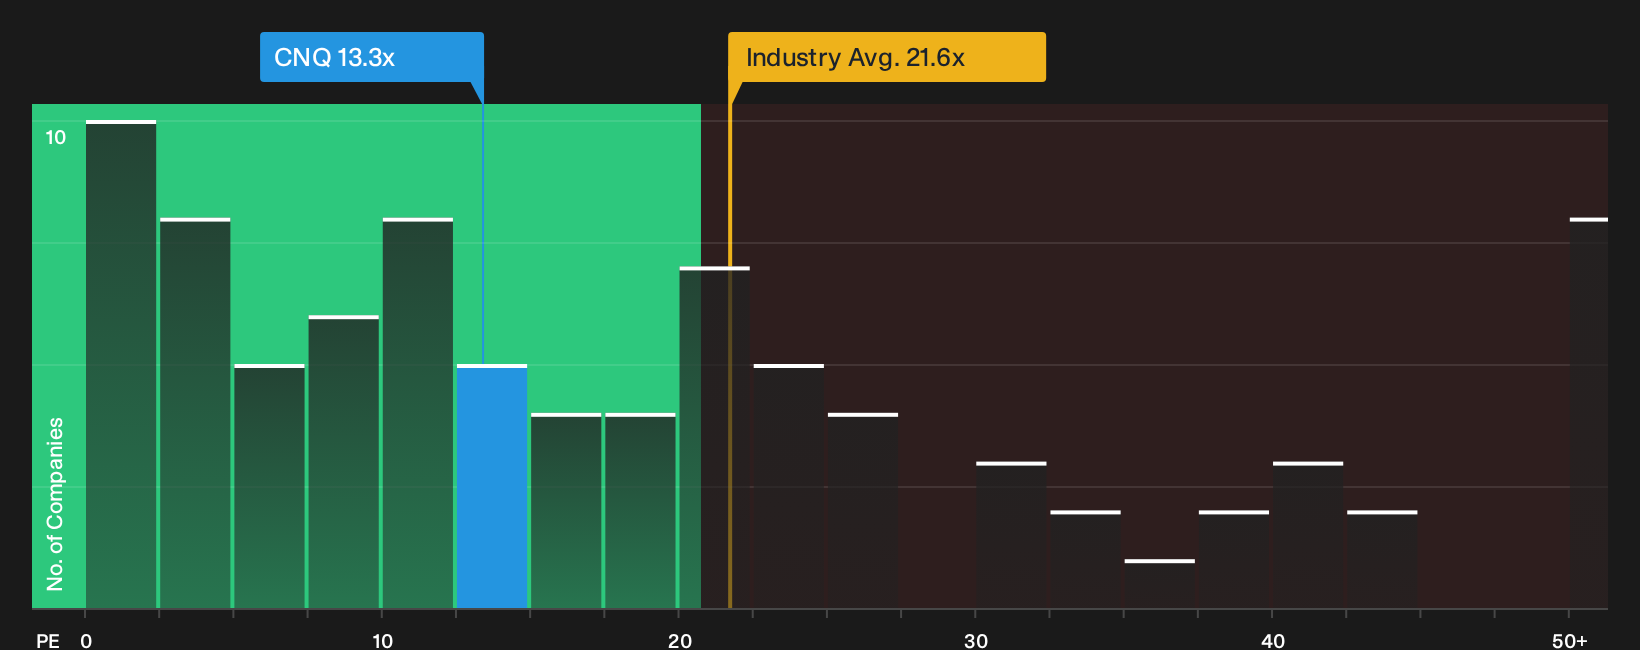
Analyst narratives point to Canadian Natural Resources as about 5% overvalued versus a CA$72.57 fair value, yet the current P/E of 13.3x tells a different story. The stock trades well below the Canadian Oil and Gas industry at 21.6x and under its own fair ratio of 14.5x, which suggests the market could eventually shift closer to that benchmark. Is this a warning that the narrative is too cautious, or a sign that earnings risk still sits in the background?
For a closer look at how those earnings ratios stack up, see what the numbers say about this price in the valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There have been mixed messages on Canadian Natural Resources so far. If you want your view grounded in the actual numbers rather than the headlines, start by weighing both the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Canadian Natural Resources?
If you only stick with familiar tickers, you risk missing strong balance sheets, steady income streams, and quality opportunities quietly gaining traction on professional screens.
- Target staying power by scanning for resilient companies on the 8 resilient stocks with low risk scores that aim to combine durable cash flows with measured risk profiles.
- Build income potential by hunting for reliable payers screened as 3 dividend fortresses that may offer meaningful yields backed by underlying fundamentals.
- Spot future contenders by reviewing the 10 high quality undiscovered gems that pair financial strength with limited current attention from the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com