
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sysco (SYY) Ends LA Strike On A Narrative That Still Looks Undervalued
Sysco (SYY) has just settled its labor dispute with Teamsters Locals 630 and 848 in Los Angeles, ending a strike that had disrupted warehouse activity and delivery routes across the region.
Sysco shares are trading at $82.22, with a 7 day share price return of 5.22% and a 30 day share price return of 4.01%. This suggests momentum has picked up around recent headlines that include the Los Angeles strike resolution and sizeable October debt issuance to fund the JRD Unico and Warehouse Realty acquisition. Over a longer stretch, a 1 year total shareholder return of 5.87%, a 3 year total shareholder return of 36.48%, and a 5 year total shareholder return of 19.44% point to a steadier, income and dividend focused story rather than a fast moving stock.
Scan how Sysco compares with other large, cash generative operators by reviewing a curated pool of 33 high quality undervalued stocks that combine balance sheet strength with investor-friendly fundamentals.
Sysco has cleared a major labor hurdle and the share price has already reacted. The real tension now is whether the current valuation still compensates you for the extra leverage and execution risk just taken on.
Most Popular Narrative: 9% Undervalued
Sysco is trading at $82.22 against a widely followed fair value estimate of $90.31, so the prevailing view is that investors are paying less than the narrative suggests the business could be worth when its key projects and acquisitions are fully reflected.
The planned acquisition of Jetro Restaurant Depot, which produced about US$16 billion of revenue, US$2.1 billion of EBITDA and nearly US$2 billion of free cash flow, is expected to add roughly 20% to combined revenue, about 45% to EBITDA and about 55% to free cash flow, which would lift overall EBITDA margins and earnings power once integrated.
See why 69 investors see Sysco as 9% undervalued.
Result: Fair Value of $90.31 (UNDERVALUED)
Still, the story around Sysco can change quickly if higher leverage from the Restaurant Depot deal worries investors or if AI projects fail to deliver the hoped for savings.
Find out about the key risks to this Sysco narrative.
Another View: What Sysco’s P/E Is Really Saying
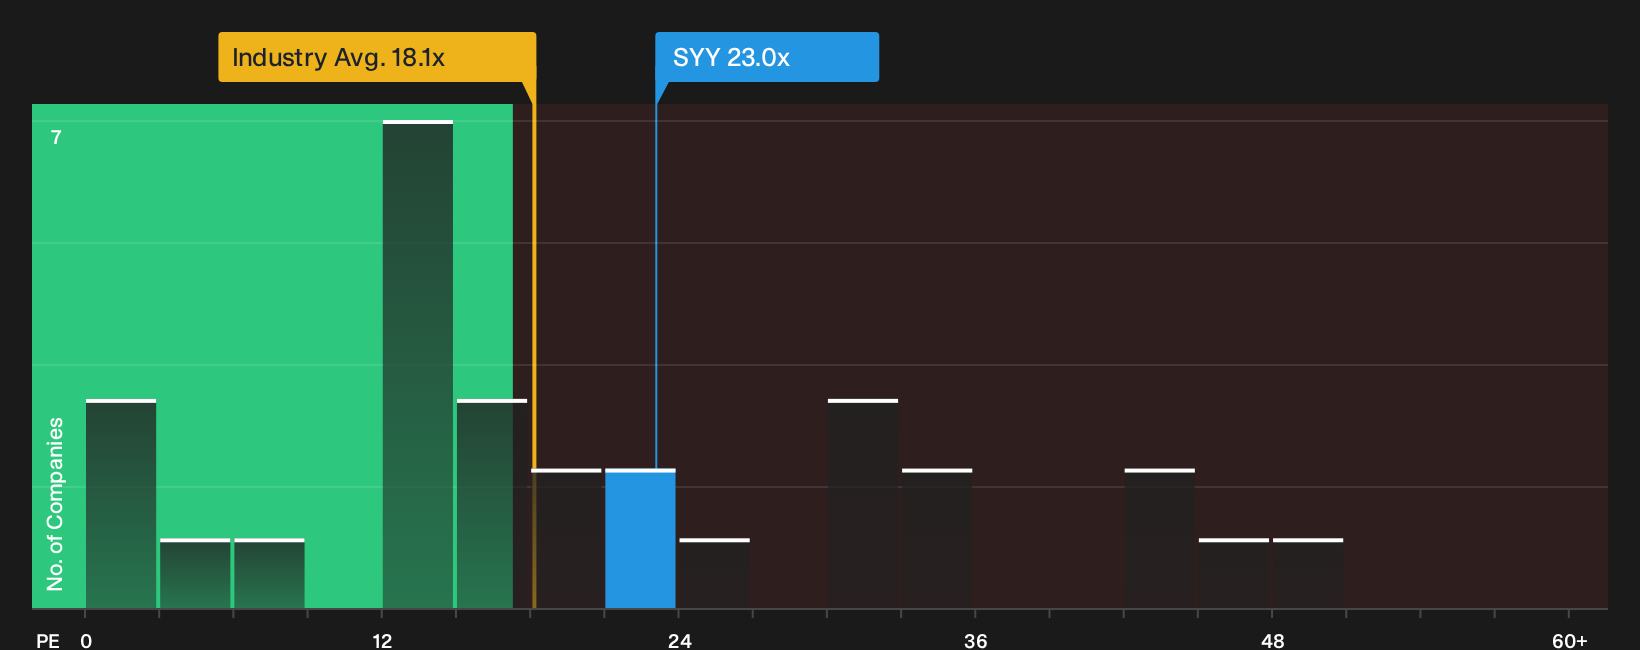
The story looks different when you focus on the price tag investors are paying today. Sysco trades on a P/E of 23x, above the US Consumer Retailing average of 18.1x, yet below both its peer group on 39.5x and a fair ratio estimate of 31x that our work suggests the market could lean toward over time.
That mix of richer pricing than the sector but cheaper terms than peers and the fair ratio hints at real valuation risk if sentiment cools, but also room for the multiple to stretch if the upbeat narrative on earnings power holds up in the numbers investors care about.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sysco after the strike and acquisition talk. Move quickly to review the full picture for yourself with 3 key rewards and 1 important warning sign
Looking for more Sysco sized investment ideas?
Sysco may fit your watchlist today, but your next strong idea could be sitting in plain sight inside a focused screener built around the traits you care about most.
- Target dependable compounding potential by reviewing a shortlist of 8 dividend fortresses that prioritize income strength alongside business quality.
- Hunt for mispriced opportunities by scanning a focused universe of 20 high quality undiscovered gems with solid fundamentals that fewer investors are watching closely.
- Prioritize resilience and aim to sleep better at night by filtering for 32 resilient stocks with low risk scores that seek to keep volatility and risk scores in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com