
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Murphy Oil (MUR) Could Be 4% Overvalued As New Wells Lift Sentiment
Why Murphy Oil Stock Is Back On Investors’ Radar
Murphy Oil (MUR) just reported a string of new well results, including successful appraisal work offshore Côte d’Ivoire, fresh discoveries offshore Vietnam, and new output online in the Gulf of America.
Investors have reacted quickly to these drilling and production updates. Murphy Oil’s 1-day share price return of 4.74% and 7-day share price return of 7.91% add to a 28.47% year-to-date share price gain. Over a longer window, the energy producer’s 55.88% 1-year total shareholder return contrasts with an essentially flat 3-year total shareholder return of 0.29%, suggesting that momentum has picked up more recently than it has over the broader period.
Scan beyond Murphy Oil and see which other energy producers are showing fresh drilling momentum in our hand-picked list of 33 high quality undervalued stocks.
After a 1 year total return of 55.88% and a market value of about US$6b, the question around Murphy Oil now is simple. Is the bigger upside still ahead, or has most of it already played out in the share price, based on what you are paying today?
Most Popular Narrative: 4% Overvalued
Murphy Oil last closed at $41.74 while the most followed narrative pegs fair value around $40.21, so the current pricing leans slightly ahead of that model and puts more weight on recent project success.
The main thing that has to go right is that higher capital spending, especially on Bubale appraisal and the Eagle Ford ramp, converts into commercially attractive offshore volumes without eroding the balance sheet or dividend capacity.
See why 14 investors see Murphy Oil as 4% overvalued.
Result: Fair Value of $40.21 (OVERVALUED)
Still, Murphy Oil’s heavier US$1.55b capital plan and rising Bubale well costs could squeeze free cash flow and weaken the case for a premium price.
Find out about the key risks to this Murphy Oil narrative.
Another View: Murphy Oil Through A Cash Flow Lens
Price based metrics label Murphy Oil as expensive, with a 20.3x P/E versus 10.2x for peers and a 16.4x fair ratio. Our DCF model presents a different perspective. On that framework, the stock trades at a steep discount to an estimated future cash flow value of $130.06. Which signal appears more informative?
For a closer look at how those projected cash flows translate into that $130.06 figure, Look into how the SWS DCF model arrives at its fair value.
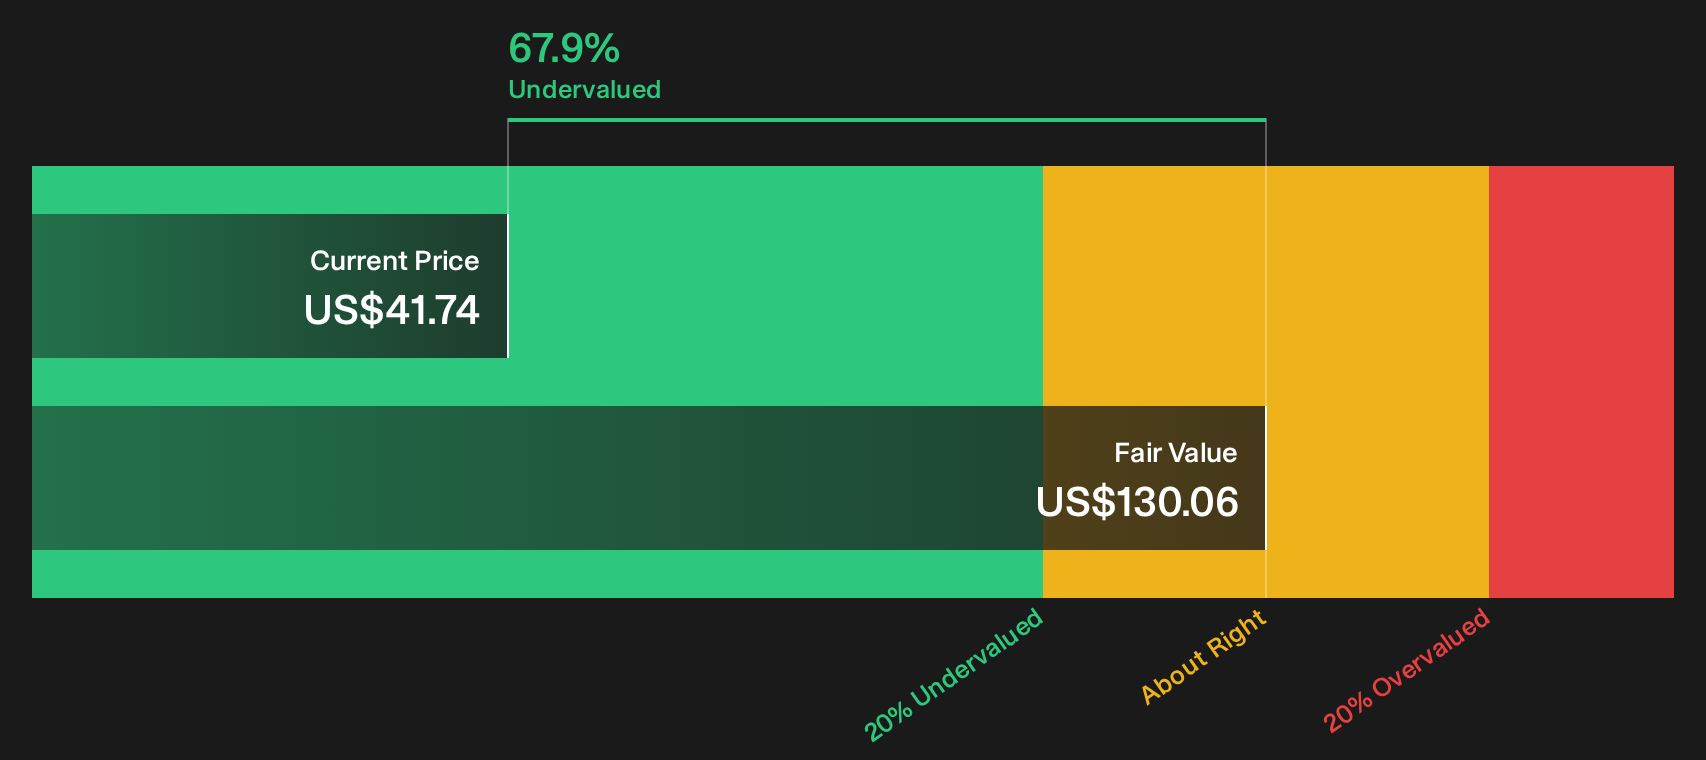
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murphy Oil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of risk and reward around Murphy Oil feels finely balanced, do not wait for clarity to magically appear. Study the data directly and pressure test your own thesis against the 3 key rewards and 1 important warning sign.
Looking For More Murphy Oil Style Investment Ideas?
Do not stop your research with Murphy Oil. Broaden your watchlist now with focused screeners that surface opportunities you might otherwise miss in plain sight.
- Target potential mispricings by scanning a curated 33 high quality undervalued stocks that combines quality fundamentals with attractive entry points.
- Strengthen portfolio resilience by focusing on companies with conservative leverage and healthy liquidity using our list of solid balance sheet and fundamentals (25 results).
- Spot future market leaders early by filtering for under the radar opportunities in the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com